October 1st, 2021 | 12:05 CEST
JinkoSolar, Memiontec, Encavis - How to profit from the Federal election
Since the Federal election on September 26, it seems clear that the Greens will be in the government. Whether a traffic light or Jamaican coalition, without the Greens, only the GroKo remains, and that is as good as impossible with the CDU as a junior partner. Annalena Baerbock has already made it clear that her party wants to push through demands regarding sustainability. Germany will therefore have to increase its efforts once again. Renewable energies will continue to be promoted, while CO2 emissions will be penalized. This approach can be observed almost everywhere in the world. Reason enough to take a closer look at three companies that are committed to sustainability.
time to read: 3 minutes | Author: Armin Schulz
ISIN: JINKOSOLAR ADR/4 DL-00002 | US47759T1007 , Memiontec Holdings Limited | SGXE56008290 , ENCAVIS AG INH. O.N. | DE0006095003
Table of contents:
Author
Armin Schulz
Born in Mönchengladbach, he studied business administration in the Netherlands. In the course of his studies he came into contact with the stock exchange for the first time. He has more than 25 years of experience in stock market business.
Tag cloud
Shares cloud
JinkoSolar - IPO of the subsidiary holds potential
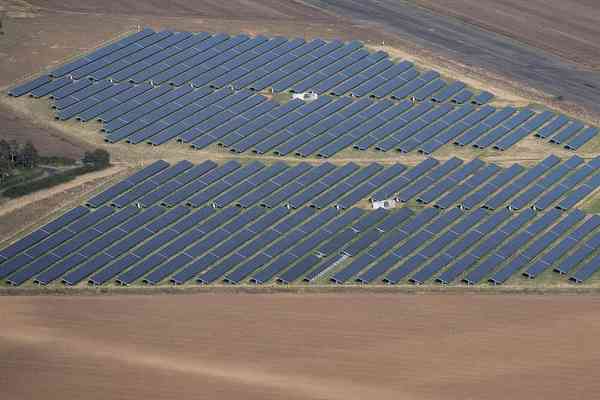
JinkoSolar is known to be one of the largest photovoltaic suppliers worldwide. While Germany was considered a pioneer in solar energy for a long time, Chinese companies are now leading the way. Solar power is an essential element in the energy transition, as there are plenty of spots on earth where the sun shines almost all day. So the prospects for the future are excellent. Nevertheless, JinkoSolar is also suffering from margin pressure in the industry.
The last quarterly figures surprised analysts positively. Expectations were exceeded, only the outlook looked a little worse, as the gross margin in the third quarter could fall from around 17% to 12%. The high raw material prices and also the chip crisis play a role here. Nevertheless, the Company is investing USD 500 million in Vietnam to build another production facility with up to 7 gigawatts.
The rumors about an IPO of the subsidiary Jiangxi Jinko seem to be confirmed. The filing was made back in June, and the subsidiary has already provided estimates for the first nine months of the year. Sales are around USD 3.6 billion and profits are expected to be about USD 99 million. Most recently, the subsidiary was valued at a market value of USD 1.7 billion, while the parent JinkoSolar is currently valued at just USD 2.1 billion. An IPO would significantly increase the value of JinkoSolar. Currently, the share is at USD 41.85. Above USD 44.26, the chart picture is slowly clearing up.
Memiontec - Water is valuable
Memiontec is currently mainly active in Singapore, Indonesia and China. The Company is a specialist for water solutions of all kinds and has been active in the market for almost three decades. A milestone was reached in 2016 when the first BOOT and TOOT projects were landed. These contracts run for up to 25 years and guarantee recurring revenues. In addition to these projects, which are mainly concluded with municipalities, the Company has well-known customers such as Nike, Singapore Airlines, Danone Aqua, Pepsico, and Micron.
On August 30, the Company won two tenders in Singapore with a total volume of SGD 12.7 million. Part of the contract was awarded by the Public Utilities Board, which had already awarded a SGD 21.7 million contract to Memiontec in April. So customers are very happy with their partner. The order book thus climbs to SGD 91.6 million. The management expects some large tenders for various water treatment plants and waterworks in the coming years.
Memiontec can cover the complete value chain of the water industry and already has all necessary licenses to participate in these tenders. Due to the first successful projects and the resulting contacts, the Company can look forward to the tenders with confidence. The share price has more than doubled since the beginning of August. As an interested investor, one should wait for a setback to enter. The Company is even already paying a dividend.
Encavis - Launches new fund
The German Encavis could benefit directly from the government participation of the Greens because, as already mentioned, investments in renewable energies will then be ramped up. Since Germany, unlike other industrialized countries, cannot rely on nuclear power to reduce CO2 emissions, the only option is to invest in wind and solar power. Here Encavis is very well positioned. 75% of the electricity generated comes from solar energy, and 25% is wind power.
Last Monday, it was announced that Encavis Asset Management, a wholly-owned subsidiary, has acquired 5 wind farms in France, all of whose wind turbines are equipped with new modern turbines, giving them a capacity of 74.5 megawatts. The special fund EIF II provided financing for the transaction, which was launched together with BayernLB and provided with EUR 480 million in capital in December last year. This fund is aimed exclusively at credit institutions. Due to the zero interest rate policy, demand was huge. Now the next fund is being launched, as the Company announced on September 29. This time, EUR 500 million is to be raised. The fund promises an average 5% annual payout.
Management has reiterated annual targets of EUR 320 million in sales and EUR 240 million in adjusted operating profit. Shareholders currently receive a dividend yield of around 1.8%, although it should be noted that the company has steadily increased the dividend in recent years. The stock has been running sideways in a EUR 3 range since early June. Some time ago, corporate bodies bought shares at about this level. This is usually a good sign.
All companies are ultimately working toward greater sustainability. JinkoSolar is providing customers with the appropriate solar systems. Memiontec is trying to reduce water waste as much as possible and give the people access to drinking water. Encavis supplies its customers with green electricity. Should the Greens become part of the government, this is likely to be the area with the most potential.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may in the future hold shares or other financial instruments of the mentioned companies or will bet on rising or falling on rising or falling prices and therefore a conflict of interest may arise in the future. conflict of interest may arise in the future. The Relevant Persons reserve the shares or other financial instruments of the company at any time (hereinafter referred to as the company at any time (hereinafter referred to as a "Transaction"). "Transaction"). Transactions may under certain circumstances influence the respective price of the shares or other financial instruments of the of the Company.
Furthermore, Apaton Finance GmbH reserves the right to enter into future relationships with the company or with third parties in relation to reports on the company. with regard to reports on the company, which are published within the scope of the Apaton Finance GmbH as well as in the social media, on partner sites or in e-mails, on partner sites or in e-mails. The above references to existing conflicts of interest apply apply to all types and forms of publication used by Apaton Finance GmbH uses for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and etc. on news.financial. These contents serve information for readers and does not constitute a call to action or recommendations, neither explicitly nor implicitly. implicitly, they are to be understood as an assurance of possible price be understood. The contents do not replace individual professional investment advice and do not constitute an offer to sell the share(s) offer to sell the share(s) or other financial instrument(s) in question, nor is it an nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but rather financial analysis, but rather journalistic or advertising texts. Readers or users who make investment decisions or carry out transactions on the basis decisions or transactions on the basis of the information provided here act completely at their own risk. There is no contractual relationship between between Apaton Finance GmbH and its readers or the users of its offers. users of its offers, as our information only refers to the company and not to the company, but not to the investment decision of the reader or user. or user.
The acquisition of financial instruments entails high risks that can lead to the total loss of the capital invested. The information published by Apaton Finance GmbH and its authors are based on careful research on careful research, nevertheless no liability for financial losses financial losses or a content guarantee for topicality, correctness, adequacy and completeness of the contents offered here. contents offered here. Please also note our Terms of use.