June 22nd, 2021 | 15:02 CEST
JinkoSolar, Defense Metals, Gazprom: Values for the yield kick
The fight against climate change is an ideological issue in many places. That is why there are bitter opponents of the measures. But clean energy should be in everyone's interest - at least if it is profitable to produce. Many people rightly have reservations about pushing technology onto the market solely based on subsidies. History has shown that this creates the wrong incentives and even restricts the development of technology that could become established in the long term.
time to read: 3 minutes | Author: Nico Popp
ISIN: US47759T1007 , CA2446331035 , US3682872078
Table of contents:
Author
Nico Popp
At home in Southern Germany, the passionate stock exchange expert has been accompanying the capital markets for about twenty years. With a soft spot for smaller companies, he is constantly on the lookout for exciting investment stories.
Tag cloud
Shares cloud
JinkoSolar: How investors can act now
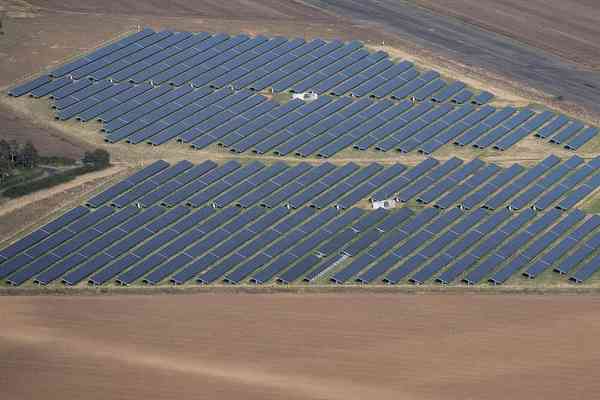
A good example of misguided subsidies around renewable energy is the German solar boom more than ten years ago. At the time, companies like SolarWorld and Q-Cells were making a splash, and thanks to government-guaranteed minimum prices, many people were plastering low-efficiency solar panels on their roofs. But then the Chinese came along and were cheaper and, after a while, better. The result: many German solar pioneers slid into insolvency. Today, solar cells are preferably built in Asia, such as by JinkoSolar. The development of the government measures in Germany: There is practically no German solar industry. Nothing but expenses.
However, today's solar giants benefited Indirectly: German technology advanced the industry, and the Chinese were also inspired by it. But those days are over. Only recently, JinkoSolar received awards for the effectiveness and durability of its solar cells. At the same time, the Company is competitive and has made it to market leader. The share recently lost 13% in just five trading days, but it also rose sharply before that. In German trading, it will be necessary for the share to sustainably overcome the EUR 38.20 mark. Then the value should get back into better waters. However, those who believe in the technology can already use the current level for cautious position building.
Defense Metals: Rare earths in Canada
To cautiously get a foot in the door, the shares of Defense Metals could also be an option at the given time. The Company operates the Wicheeda rare earths project, an exciting deposit centered around critical metals in Canada. The Company reports that the project contains 4.9 million tons of rock with an average grade of 3.02% light rare earth metals. In addition, there are inferred resources of 12.1 million t. at an average grade of 2.9%. Most recently, Defense Metals raised CAD 5 million to advance further exploration.
The Company is looking to strike near-surface in particular and is targeting the drilling program accordingly. The Wicheeda Rare Earth project is integrated into existing infrastructure and could offer production costs below the industry average. Near-surface deposits would even reinforce these cost advantages. The stock has been good for rallies in the past. Due to the financing, the share price has settled at EUR 0.20. Due to the strategic importance of rare earths, whose market is largely controlled by China, the project in Canada is promising. In addition, there is the prospect of sustainable production, which is especially important to companies with ESG profiles. Defense Metals' stock has settled down a bit - which is precisely why investors can take a look at the value.
Gazprom: Top dog with risks
The Russian Company Gazprom also claims to have an ESG profile: On its website, Gazprom refers to CO2 saved. But if you look at independent ESG ratings, Gazprom's risk is high. How should investors deal with such information? In the short term, the relatively weak ESG rating should have no impact on the share price. In the long term, however, Gazprom could well fall behind. However, this is offset by the low production costs with which the Company shines. So there is potential to invest in more sustainability if necessary.
Gazprom is currently building the Nord Stream 2 pipeline, and despite the political controversies surrounding the mega-project, Gazprom is well-positioned. If Europe does not want Russian gas, the Asians should already be standing and providing Gazprom with secure sales. The stock also shines with a dividend yield of more than 6%. Gazprom is a massive company with a good cost structure and existing growth. However, this is offset by political as well as ESG risks. The stock is also unlikely to stage another rally. However, the stock can be used as a solid dividend investment in case of weakness.
Which stock provides the yield kick?
Similar to JinkoSolar, Gazprom is also well-positioned and can be considered a market leader. Defense Metals is a different story. The Company is only developing its rare earth project. While the signals are already positive, any investment must be considered speculative. In return, the Company, which is currently valued at only EUR 13.5 million, can also more easily stage a brilliant price rally. Investors need to add stocks like Defense to their portfolio according to their personal risk profile. Then they can also play an important role in the portfolio - for example, as a yield kick in times of rising prices.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may in the future hold shares or other financial instruments of the mentioned companies or will bet on rising or falling on rising or falling prices and therefore a conflict of interest may arise in the future. conflict of interest may arise in the future. The Relevant Persons reserve the shares or other financial instruments of the company at any time (hereinafter referred to as the company at any time (hereinafter referred to as a "Transaction"). "Transaction"). Transactions may under certain circumstances influence the respective price of the shares or other financial instruments of the of the Company.
Furthermore, Apaton Finance GmbH reserves the right to enter into future relationships with the company or with third parties in relation to reports on the company. with regard to reports on the company, which are published within the scope of the Apaton Finance GmbH as well as in the social media, on partner sites or in e-mails, on partner sites or in e-mails. The above references to existing conflicts of interest apply apply to all types and forms of publication used by Apaton Finance GmbH uses for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and etc. on news.financial. These contents serve information for readers and does not constitute a call to action or recommendations, neither explicitly nor implicitly. implicitly, they are to be understood as an assurance of possible price be understood. The contents do not replace individual professional investment advice and do not constitute an offer to sell the share(s) offer to sell the share(s) or other financial instrument(s) in question, nor is it an nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but rather financial analysis, but rather journalistic or advertising texts. Readers or users who make investment decisions or carry out transactions on the basis decisions or transactions on the basis of the information provided here act completely at their own risk. There is no contractual relationship between between Apaton Finance GmbH and its readers or the users of its offers. users of its offers, as our information only refers to the company and not to the company, but not to the investment decision of the reader or user. or user.
The acquisition of financial instruments entails high risks that can lead to the total loss of the capital invested. The information published by Apaton Finance GmbH and its authors are based on careful research on careful research, nevertheless no liability for financial losses financial losses or a content guarantee for topicality, correctness, adequacy and completeness of the contents offered here. contents offered here. Please also note our Terms of use.