September 7th, 2022 | 12:18 CEST
Minimum risk, maximum opportunity: Thyssenkrupp, Saturn Oil + Gas, BioNTech
The energy price hammer, possible gas rationing in winter, and then there was the pandemic - but which issues end up impacting share prices? Are the risks around energy shortages already adequately priced into the industry? Are energy companies even fairly valued? And what opportunities can BioNTech still offer? We look at three stocks and provide an overview of opportunities and risks.
time to read: 4 minutes | Author: Nico Popp
ISIN: THYSSENKRUPP AG O.N. | DE0007500001 , BIONTECH SE SPON. ADRS 1 | US09075V1026 , Saturn Oil + Gas Inc. | CA80412L8832
Table of contents:
Author
Nico Popp
At home in Southern Germany, the passionate stock exchange expert has been accompanying the capital markets for about twenty years. With a soft spot for smaller companies, he is constantly on the lookout for exciting investment stories.
Tag cloud
Shares cloud
ThyssenKrupp - Better than feared
Stocks like Thyssenkrupp suffered this year. The more Putin turned the gas tap, the more nervous the market became. At times there was even talk of the collapse of entire industries. The steel sector is traditionally very energy-intensive and, therefore, in trouble. Nevertheless, Thyssenkrupp did quite well in the third fiscal quarter: sales climbed 26% to around EUR 11 billion, and the Company also increased its operating earnings. Rationalization measures took effect above all in the steel business. By contrast, disrupted supply chains weighed more heavily on Thyssenkrupp's auto business, which contributes only around 13% of the Company's total sales. By comparison, steel is responsible for more than a quarter of sales. Only the materials services sector is even more important.
Another little-noticed aspect of Thyssenkrupp is that the Company has a small but significant business unit, Marine Systems, which could benefit from more investment in armaments. Just a while ago, Thyssenkrupp bought the MV Werften shipyards in Wismar. The electrolysis business also has a future and may even be floated separately on the stock market. The division's potential would then become visible, and the steel giant would raise capital for further growth in the hydrogen sector. At Thyssenkrupp, short-term risks and long-term opportunities come together. If Germany comes through the winter well and the stock becomes even cheaper, opportunities could arise here. As a cyclical stock, however, Thyssenkrupp is of little interest at present.
Saturn Oil & Gas: Stock market value = 2023 cash flows
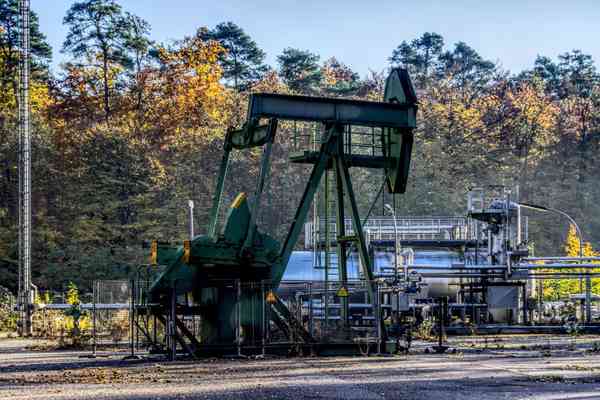
The Saturn Oil & Gas share is also known as a cyclical stock. However, the figures speak a different language - the share should be strong right now. Saturn generated a record cash flow of CAD 14.5 million in the fiscal quarter just ended. Compared to the same period last year, that is an increase of 400%. For analysts at Velocity Trade Capital, however, it is just the tip of the iceberg, as cash flow is expected to rise to more than CAD 100 million in the ongoing second half alone. The reasons for this are two acquisitions Saturn has made in recent years, which are now also making themselves felt in the figures. Most recently, Saturn secured an additional 2,782 barrels of oil at a minimum of USD 100, making the business even more stable. For analysts, the current valuation is roughly in the range of the EBITDA expected for 2023 - which would make Saturn enormously favorably valued. In addition, there is growth potential.
While Saturn operated just one project years ago, today, there is more room to seize growth opportunities and control production thanks to its three properties. Also, as a mid-sized producer, finding service providers on good terms should be more accessible. Saturn Oil & Gas' share price is currently still suffering from dilution in the wake of the acquisitions. It should be noted that the majority of the acquisitions were made with debt capital. In this context, the name of a large US family office keeps circulating in relevant forums and YouTube videos, but the Company has never confirmed this. Thanks to the high cash flows, the share of borrowed capital should be more than halved by next year. If outstanding warrants at CAD 3.20 are called in June and July of next year, Saturn would even be debt-free by mid-2023. Such a high cash flow cries out for shareholders to participate in the profits. The fact that Saturn could already pay a dividend in the medium term is also underscored by the candidacy of Deutsche Rohstoff AG Supervisory Board Chairman Thomas Gutschlag for the Supervisory Board. The experienced manager and long-time CEO of the Mannheim-based company has in the past realized favorable acquisitions under challenging market conditions and, at the same time, established a dividend policy that is attractive to shareholders. The chances are good that the market will recognize the new potential of Saturn Oil & Gas - the company from Saskatchewan has the energy in the ground and is currently producing extremely profitably.
BioNTech: The market already has cancer in its sights
BioNTech also has great potential - patents and technology promise high returns in the long term. But how ambitiously is the share valued? If you look at BioNTech's price-earnings ratio, you will find a figure of around 3, which is really only known from companies in uncertain jurisdictions. Why is that? The market assumes that the excessive profits BioNTech made with its vaccines during the pandemic years are not sustainable. While mRNA technology offers all the possibilities, including against cancer, there is still a risk inherent in these plans that the cancer vaccines may not work out so well after all. Although the vaccine variants against pancreatic cancer and so-called CAR-T cells, which sensitize the immune system to cancer cells, are considered promising, success has yet to be achieved. So despite its rise, BioNTech's stock has not become a cash cow but remains an almost pure-play biotech in the long run. Investors need to be aware of this.
If fall and winter bring a pandemic comeback, BioNTech should also rise again. In the long term, however, the market will focus on the new products - the biotech motto "Top or Flop" applies here. Investors who want to invest conservatively in business models that work should take a closer look at the shares of Saturn Oil & Gas. The Company generates 2023 cash flows in the amount of the current stock market valuation, operates in Canada and has a crystal clear ESG orientation. The research portal researchanalyst.com took a detailed look at the latest figures a few weeks ago. An investment here seems much more predictable than with short-term vulnerable industrial stocks such as Thyssenkrupp or biotech bets such as BioNTech - even if both companies mentioned could also offer prospects again in the medium term.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.