December 21st, 2022 | 08:46 CET
The best cards for 2023: Amazon, Aspermont, flatexDEGIRO, TUI - Which stock will take off?
Crisis, crisis, crisis - we do not want to hear any more about it at Christmas time. After the relief rally, the stock markets have gone back to sleep. It was turbulent until September, and then the correction was over for the time being. But how much "good" is already priced in for next year? Will there be a quick end to the war, can the inflation rate also fall, and what will interest rates do in 2023? Many unanswered questions that will likely only be answered gradually. The shares have to achieve a fair valuation from this mixed situation - perhaps that is why the correction is not quite over yet. Where are the best opportunities for investors?
time to read: 5 minutes
|
Author:
André Will-Laudien
ISIN:
AMAZON.COM INC. DL-_01 | US0231351067 , TUI AG NA O.N. | DE000TUAG000 , FLATEXDEGIRO AG | DE000FTG1111
Table of contents:
Author
André Will-Laudien
Born in Munich, he first studied economics and graduated in business administration at the Ludwig-Maximilians-University in 1995. As he was involved with the stock market at a very early stage, he now has more than 30 years of experience in the capital markets.
Tag cloud
Shares cloud
Amazon - Prospects for a conciliatory Christmas
The Amazon share has accumulated a whole minus 46% since the beginning of the year. Meanwhile, there had been a split in the middle of the year, which usually provides for price fantasy. However, the so-called FAANG shares had also risen exorbitantly by the end of 2021. So a certain deflation should not be a disappointment. Fundamentally, the agreement with the EU provides some relief because the current antitrust proceedings could have ended worse for the e-commerce giant. Amazon has now made concessions to the EU over allegations about the treatment of third-party sellers on its platform. The proceedings have reportedly been terminated, and the US group will not have to pay a fine. Under the settlement, the group must, among other things, commit to changing certain anti-competitive business practices for up to 7 years.
Amazon has now relented but is still contesting some of the EU's accusations regarding its business practices. At least there is now a settlement that allows the US company to continue doing business in the EU. That was probably the minimum goal of the lawyers from Seattle. After earnings per share are likely to be negative in 2022, the plan is to return to USD 4.20 by 2025. This means that after a market value loss of almost USD 800 billion in the current year, the stock will again be available at a P/E ratio of around 20 in 2025. The Bezos share has not been this "cheap" for 3 years.
Aspermont Ltd - How it may fare in 2023
After years of rapid growth and 25 consecutive quarters of revenue growth, Australian mediatech company Aspermont introduced itself to a larger European investor audience in September. The Company's value grew by a full 50% thanks to new prospective investors who were excited by the business model. Aspermont's successful transformation could have come out of a textbook. In just a few years, the Australians have transformed from a venerable publishing house to a modern XaaS provider with a database of more than 8 million high-level contacts in business and finance. The Company's services scale well as it grows because of the strong complementary needs of its customers.
The digital services and B2B media in the mining, energy and agriculture sectors help participants in the network view significant information and formulate financing needs simultaneously. The intelligent platforms match the audience's desires and bring interested parties together in the best possible way. With its Anything-as-a-Service (XaaS) model launched in 2017, Aspermont distributes high-quality content to a growing audience via a subscription model. Premium models are also available, increasing the amount of relevant content and targeting requests. Overall, Aspermont thus generates recurring revenue, and the revenue share per customer grows continuously. The three integrated business models of content, data and services are highly scalable and can now be extended to new sectors, other countries and languages. Growth is programmed to continue.
For the full year 2022, the Australians reported total revenue of AUD 18.7 million, up 17% from FY2021, with a gross margin of 64% resulting in a gross profit of AUD 12 million. Operating profit (EBITDA) remains at AUD 2.8 million, which can be significantly increased with the restarted "live events" after COVID-19 in the coming year. The share is currently trading at a low EUR 0.014; the high for the year was around 50% higher. Meanwhile, the debt-free company has more than AUD 7 million in cash and cash equivalents. The research house GBC sees opportunities for a significant increase to AUD 0.11 in the next 12 to 24 months. Highly interesting!
flatexDEGIRO and TUI - It can always get worse!
Two fallen angels are worth taking a closer look at. They are the broker stock flatexDEGIRO and the largest European travel provider TUI.
flatexDEGIRO had recently received a reprimand from BaFin. The Company had grown very strongly and, at the same time, had paid too little attention to its regulatory obligations. In November, the online broker received the result of a special audit by the financial supervisory authority BaFin, which criticized deficiencies in the organization and corporate governance of the start-up. At the same time, the business forecast for the current year was lowered again, and the dividend that had been put on the table will probably not be paid. As a result, the share price dipped to a new low of EUR 5.61. With sales of just under EUR 400 million in 2022, the Company is now only valued at a P/E ratio of 7 and a P/S ratio of 1.3. Customer assets under custody have tripled to about EUR 42 billion since 2019. If flatex solves its organizational problems, a doubler could beckon from today's level.
Travel provider TUI is still fighting the consequences of balance sheet deterioration from the COVID-19 days. Debt went through the roof, and it was necessary to carry out some capital increases to strengthen equity. The share price diluted so much that at EUR 1.55, there is still a 74% loss gap to the pre-pandemic period. In 2023, the new Group CEO, Sebastian Ebel, wants to tackle the repayment of state aid with which the German government had saved the tourism giant from going under. The expected profits from the travel business are insufficient because the Group has not yet returned to the black in the past fiscal year (September 30). However, thanks to a significant increase in bookings, the net loss shrank by almost 90% to EUR 277 million on tripled sales of EUR 16.5 billion. After a loss of more than EUR 2 billion in 2021, the Hanover-based company at least achieved an adjusted EBIT of EUR 409 million. Shareholders are now to inject billions of euros in fresh money once again and accept a capital cut. If the new capital injection succeeds, TUI could become a hot turnaround candidate for 2023. Stand ready!
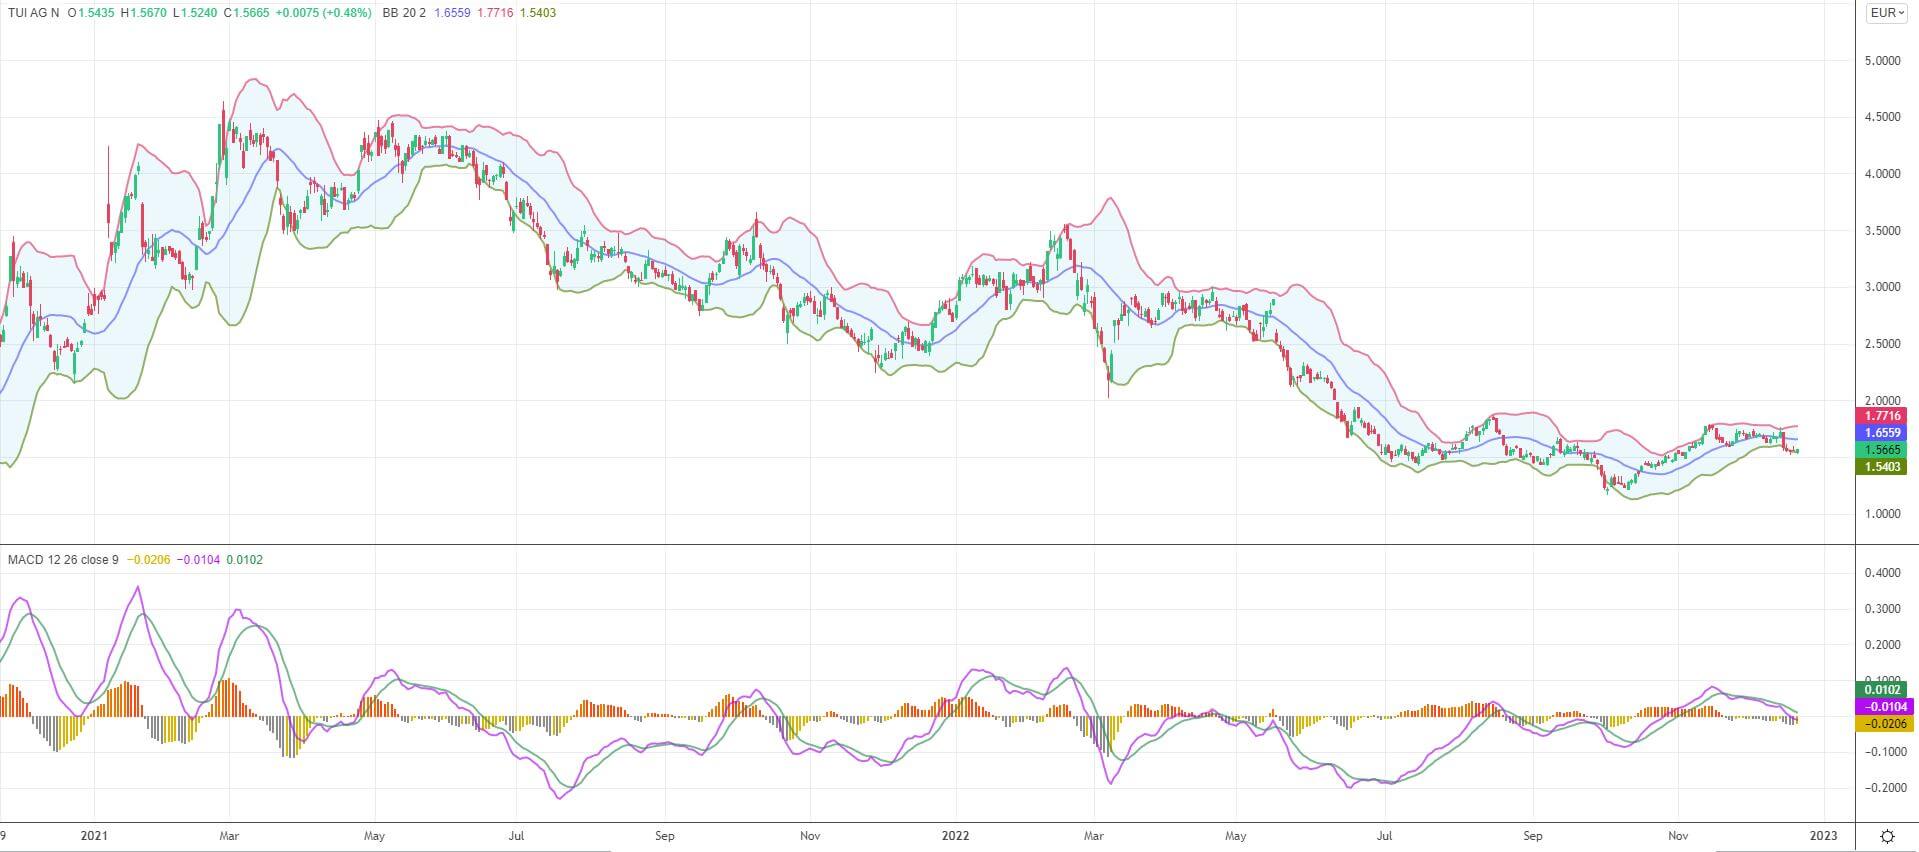
The year-end rally is slowly coming to an end, but in the next upward movement, selection is the trump card. Many stocks have lost disproportionately, but the numbers are gradually improving. Amazon, flatexDEGIRO and TUI appear attractive as turnaround stocks. Aspermont is well positioned with its platforms for resuming capital market business at the beginning of the year.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.