January 16th, 2023 | 15:27 CET
BP, Saturn Oil + Gas, Shell - Is a new price cap for Russian oil coming?
The price cap of USD 60 for a barrel of Russian oil has been in place for just over a month. According to high-ranking diplomats from both countries, Poland and Lithuania already want to lower the current maximum price once again. It is not yet clear whether the sanctions will actually have any effect. Russian Deputy Prime Minister Novak said Russia had no export problems despite the sanctions. Positive signals for oil came from the US, as inflation continues to weaken and inflation expectations also fell for the fourth month straight. In addition, according to energy traders, demand from China and Europe is picking up. We, therefore, take a closer look at three oil producers.
time to read: 4 minutes | Author: Armin Schulz
ISIN: BP PLC DL-_25 | GB0007980591 , Saturn Oil + Gas Inc. | CA80412L8832 , Shell PLC | GB00BP6MXD84
Table of contents:
Author
Armin Schulz
Born in Mönchengladbach, he studied business administration in the Netherlands. In the course of his studies he came into contact with the stock exchange for the first time. He has more than 25 years of experience in stock market business.
Tag cloud
Shares cloud
BP - Transformation progresses
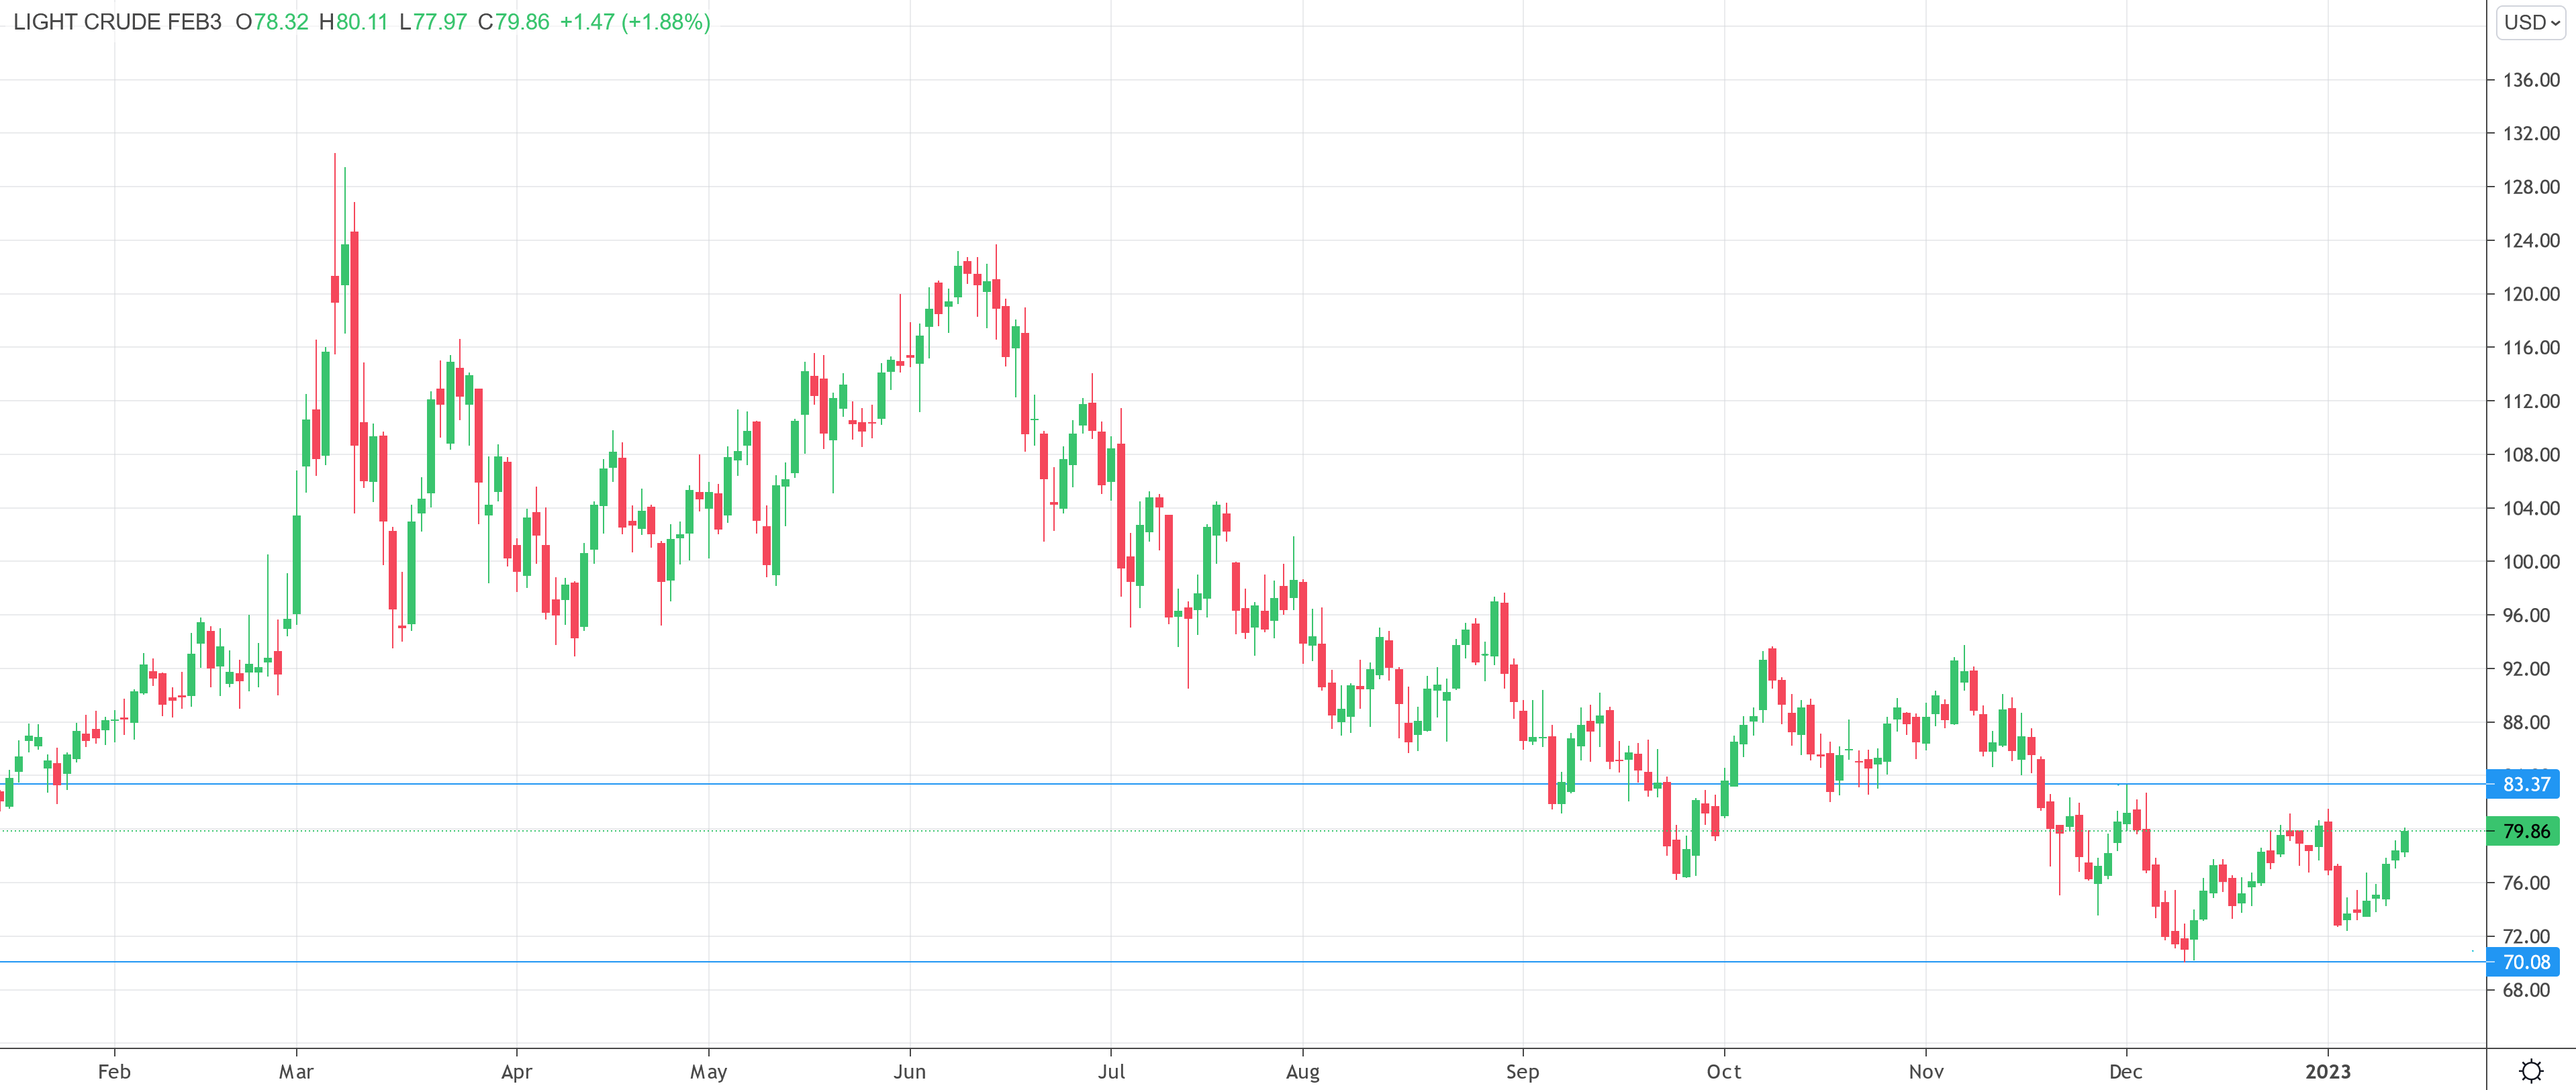
Last week, the oil price almost recovered its losses of the previous week, supporting reports of rising demand. This is good news for the oil multinational BP, which generates a large part of its profits from fossil fuels. But the Group wants to move away from that in the long term and is trying to reshape its business units. The high cash flow that oil and gas sales bring into the Company's coffers is helping. In the third quarter, the biogas business expanded with the acquisition of Archaea Energy for USD 4.1 billion in the US, as well as the formation of Azule Energy.
By 2030, BP aims to be able to supply about 70,000 barrels of biogas per day via pipelines. Another growth market for the Group is electric charging stations. In North America, it has gained a well-known partner in Hertz to set up charging solutions for e-cars. In Germany, cooperation with REWE was intensified. In the hydrogen sector, the Group secured a 40.5% stake in AREH, a center for renewable energy and green hydrogen. Despite the high investments in the new markets, the Company aims to keep dividends stable.
In addition, the share buyback program is an attempt to additionally increase value for shareholders, while at the same time, the Company believes that the stock is undervalued. In the past three years, debt has been gradually reduced, even though free cash flow has grown. The oil price has been volatile recently and has fallen since June 2022, yet the stock has gained almost 30%. On Friday, it exited Xetra trading at EUR 5.456. The dividend yield is currently around 4%.
Saturn Oil & Gas - Buy recommendation with a target of CAD 6.30
Significantly smaller is Saturn Oil & Gas. Daily production since Q1 2021 has increased by 5,365% to 12,500 barrels, and no oil multinational can keep up. Acquisitions played a significant role in this. Most recently, the Viking property was acquired at an unhedged 4,000 barrels for CAD 260 million. This transaction increased production by 50% and revenue by 53% and adjusted EBITDA by 179% in Q3. Much of the production was hedged above USD 102 for 2022 and is around USD 92 for 2023. In subsequent years, the hedged production and price will decline, ensuring that the Company can pay off all debt - no matter where the oil price moves.
On January 11, First Berlin Equity Research published an update on Saturn Oil & Gas. Analyst Simon Scholes projects that the full-year contribution from the Viking acquisition and continued drilling on the Oxbow and Viking properties will result in a 60% increase in EBITDA to CAD 261 million in 2023. That is above the Company's guidance of CAD 252 million. In addition, Saturn is expected to have completely paid off its debt of CAD 232 million by the end of 2025 and will then have net liquidity of CAD 177 million. The analyst recommends a buy but has reduced his target from CAD 7 to CAD 6.30 due to the recent drop in oil prices.
As a result, the stock, which was last quoted at CAD 2.46, offers an upside of over 150%. The opportunities also clearly outweigh the risks. Production is largely hedged, so there is no longer such a strong dependence on the oil price. Currently, there are 59.8 million shares. Fully diluted, there are 102.6 million shares. Based on the assumption that the Company meets its forecasts, EBITDA per share would be CAD 4.21. If all options and warrants are exercised, the price would be CAD 2.45, effectively the same as the current share price. If the share price remains below CAD 3.20 until July 7, 27 million warrants will expire. If the share price rises above this level and all warrants are drawn, Saturn could be virtually debt-free by the end of next year.
Shell - New CEO takes over
Since January 1, Shell's new CEO, Wael Sawan, has been at the helm. In the first published interview, he talked about being incredibly excited but also intimidated by the big challenges. Not what shareholders want to hear from the new CEO. However, the May 2021 ruling hangs over the group, stating that the Company must reduce its carbon emissions by 45% by 2030. Shell has appealed that ruling on the grounds that it cannot be held accountable for its customers' emissions.
This could be one of the reasons why Shell's stock has underperformed its competitors despite the high oil price. There is at least the latent danger that the group will have to part with assets if the decision stands. Since the competition knows that Shell will have to sell, there could be valuation markdowns, which could negatively impact shareholders and the Company. But currently, this is not an issue. In the first 9 months, cash flow was around USD 30 billion.
A large part of this went to shareholders. Almost EUR 0.95 was distributed per share, corresponding to a dividend yield of 3.4%. In addition to the dividends, the same amount was put into a share buyback program. While BP was able to gain almost 30%, Shell has to be content with a plus of 22%. Since the beginning of December, the share has moved in the range between EUR 25.72 and EUR 28.27 and is currently available for EUR 27.58. On January 12, the downward trend line was broken.
Even if the oil price has recently dropped, oil producers are earning very well across the board. BP currently seems to have the edge in Europe. Saturn Oil & Gas is on a strong growth path and will be debt-free for the foreseeable future. The stock is currently undervalued. Under its new CEO, Shell must now show it is up to the big challenges. The appeals process in the Netherlands will certainly take years.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.