February 18th, 2026 | 07:20 CET
Nearly 200% upside potential! RENK, Nordex, and Power Metallic Mines shares under analyst review!
Analysts at Noble Capital Markets believe that Power Metallic Mines shares could rise by almost 200%. This is based on the Nisk project, which has developed from a nickel project into a world-class multi-metal project. Recent nearby drilling results suggest even greater potential. The planned IPO in the US could be an additional driver. Nordex shares are recommended as a "Buy" by mwb research. Although analysts are optimistic and see the wind turbine manufacturer on track operationally, the price target is disappointing. At RENK, the recent analyst call by management appears to have been convincing. Expectations for Q4 and the full year 2025 are likely to be met, unlike recently at Rheinmetall.
time to read: 4 minutes
|
Author:
Fabian Lorenz
ISIN:
RENK AG O.N. | DE000RENK730 , NORDEX SE O.N. | DE000A0D6554 , POWER METALLIC MINES INC. | CA73929R1055
Table of contents:
Author
Fabian Lorenz
For more than twenty years, the Cologne native has been intensively involved with the stock market, both professionally and privately. He is particularly passionate about national and international small and micro caps.
Tag cloud
Shares cloud
Power Metallic Mines: Nearly 200% upside potential
Noble Capital Markets has assigned a price target implying nearly 200% upside. Ahead of the planned IPO on Wall Street, analysts at the US broker see plenty of potential for the Canadian resource explorer. They put the fair value of the stock at CAD 3.65. The stock is currently trading at CAD 1.30.
Unsurprisingly, Noble's experts now also classify the former Nisk nickel project as a high-grade system containing copper, platinum, nickel, gold, and silver. According to their assessment, both the scale and continuity of the deposit continue to improve. In addition to precious metals, the metals present are considered essential for electrification and industrial manufacturing, with some even categorized as critical.
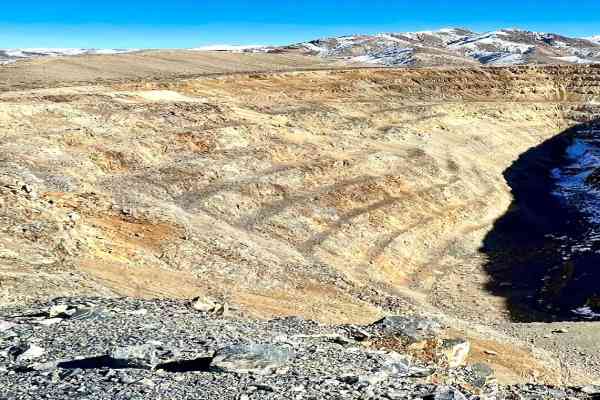
The key driver for the stock is the Lion Zone within the Nisk project. Among other things, this zone delivers exceptional grades of copper, palladium, and platinum. Follow-up drilling within the neighboring Tiger Zone would even suggest that the mineralization there is similar in strength to that at Lion. Due to the capital increase at the beginning of 2025, the company is fully financed for exploration in 2026. The plan is to drill approximately 65,000 meters in the current year.
It is also important to note that the Nisk project is located in a favorable mining jurisdiction. Mining activities in Canada and Québec benefit from substantial tax incentives that can offset a significant portion of exploration costs. In addition, there is access to environmentally friendly hydroelectric power.
Note: Those who would like to learn more about the prospects of Power Metallic Mines firsthand should register for the International Investment Forum ii-forum.com on February 25, 2026. CEO Terry Lynch will be presenting live.
Nordex: Analyst commentary and price target do not match
Next week, Nordex is set to report on its performance in the fourth quarter and for the full year 2025. mwb research advises buying the wind turbine manufacturer's shares before then. Analysts see the fair value of Nordex shares at EUR 36. The stock is currently trading at around EUR 33.50. Why the stock is a "Buy" is something only the analysts seem to understand.
mwb research sees several fundamental drivers. They expect Nordex to report a 9.2% increase in order intake for the fourth quarter and a 22.5% increase for the full year. Average sales prices should remain stable at around EUR 0.91 million per MW. For 2025 as a whole, analysts expect revenue of EUR 7.4 billion, which would be at the lower end of the company's forecast. With an EBITDA margin of 8%, Nordex should be able to meet consensus expectations.
Analysts attribute the interim decline in the share price of around 10% to profit-taking and discussions about the valuation. After all, Nordex shares have gained around 50% in the past six months, bringing the company's market capitalization to almost EUR 8 billion.
The operating outlook has improved in recent months. Following the 1 GW agreement in the US at the end of 2025, a 700 MW framework agreement was recently signed with VERBUND Green Power and further orders were added to the order book. It is now important that the Q4 figures confirm the positive development in margins and cash flow. Further upside for the stock could come from a positive outlook for 2026 or new medium-term targets. It all sounds very positive, but then the price target should also be somewhat higher.
RENK: Management convinces analysts
At RENK, "Buy" recommendations and price targets are more in line with each other. The share price of the specialist for tank transmissions is currently trading just below EUR 60. JPMorgan believes the stock is worth EUR 75 and rates it as "Overweight." The last call with management before the publication of the 2025 annual financial statements was positive. As a result, analysts raised their earnings estimates for the coming years slightly. From 2028 onwards, growth in the US could surprise on the upside. If the analysts are right, this would be very welcome, as order intake in Europe has not yet met the high expectations.
Jefferies also considers RENK shares to be fairly valued at EUR 75. The company is expected to at least meet expectations with its Q4 and full-year results. This is seen as particularly reassuring following the more cautious remarks recently made by Rheinmetall’s management.
Deutsche Bank is hardly less optimistic about RENK shares. Here, too, management came across positively during the conference call. The tank transmission manufacturer is scheduled to report on fourth-quarter developments and full-year 2025 results on March 5.
Power Metallic Mines is facing an exciting few months. In light of recent analyst comments, the stock appears anything but expensive. Anything other than continued strong drilling results would be a surprise. The US IPO may finally break the deadlock for the stock. The price target and rating by mwb research do not really fit together for Nordex. Operationally, the company appears to continue to have tailwinds, but the valuation is certainly not low. Business is also booming at RENK. The stock should benefit from this again.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.