June 18th, 2025 | 07:00 CEST
Almonty Industries: Analysts raise target price! 75% Upside Potential! CEO clearly backs Rheinmetall and Co. on CNBC
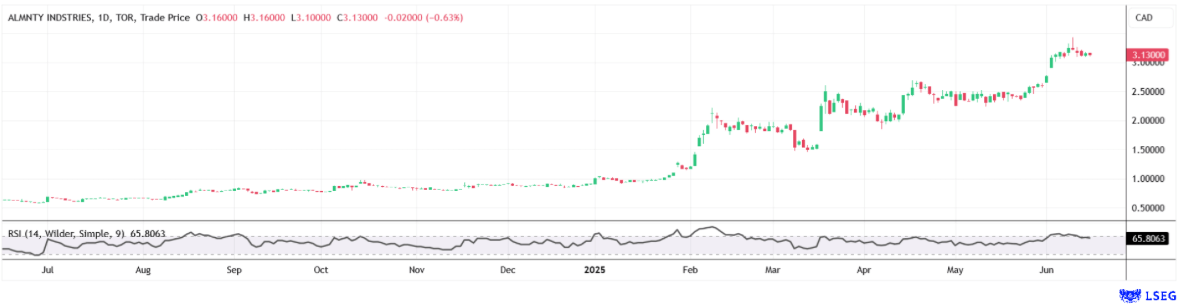
Anything other than further price increases for Almonty shares in the coming weeks would be a surprise. The tungsten gem is facing a hot summer. The main driver for the share price will be the commissioning of the mega mine in South Korea. Due to the increasing visibility of revenue and profit growth, analysts have significantly raised their price targets for the share. With its unique market position, the Company remains attractively valued compared to its peers. With the planned upcoming NASDAQ listing, the stock is expected to attract greater attention from US investors. That Almonty is gaining more visibility is underscored by CEO Lewis Black's recent interview with CNBC. In it, Black emphasized that Almonty already supplies 85% of its production to the defense sector. Rheinmetall, for example, needs tungsten to harden ammunition.
time to read: 3 minutes | Author: Fabian Lorenz
ISIN: ALMONTY INDUSTRIES INC. | CA0203981034 , RHEINMETALL AG | DE0007030009
Table of contents:
Author
Fabian Lorenz
For more than twenty years, the Cologne native has been intensively involved with the stock market, both professionally and privately. He is particularly passionate about national and international small and micro caps.
Tag cloud
Shares cloud
75% price potential: Analysts raise target
GBC Research has raised its price target for Almonty Industries shares from CAD 4.20 (EUR 2.69) to CAD 5.50 (EUR 3.52). The "Buy" recommendation was confirmed in a detailed research update.
The main reason for the price target increase is the improved visibility for the commissioning of the Sangdong mine in South Korea. The mega mine will make Almonty the largest tungsten producer in the Western world. Analysts report that construction work on the Sangdong mine was largely completed in the first quarter. The installation of the processing plant is in its final phase, and the last tranche of the project financing loan from KfW IPEX Bank for USD 75.1 million has been drawn down. The first ore processing is scheduled to take place in the second half of the year.
P/E ratio for 2027 below 5
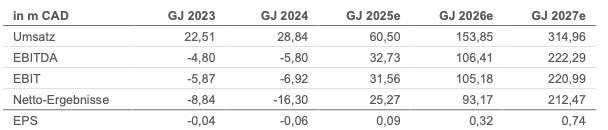
Revenue and earnings are expected to grow dynamically in the coming years. Analysts already expect revenue to double to around CAD 60 million this year. In 2027, revenue of CAD 314 million is expected to result in net income of CAD 212 million. This would give Almonty a strong net margin of 67.5%. With expected earnings per share of CAD 0.74 for 2027, the P/E ratio is currently below 5. This appears to be too cheap. GBC study available for download here
Almonty of strategic importance for the defense sector
With its resource base, high ore grades, and vertical integration extending to its tungsten oxide processing plant, Sangdong is becoming a strategically significant player in the global tungsten supply chain – and thus for the Western defense sector. This strategic importance was recently confirmed officially at the highest level by the US government. Almonty received an official letter from the US House of Representatives' Select Committee on the Strategic Competition between the United States and China. The Sangdong mine was recognized by the committee for its potential to become the largest tungsten producer outside China.
The committee intends to continue working with Almonty. Almonty could not only support the US defense industry but also potentially supplement national defense stocks with its tungsten. There has been no commercial tungsten production in the US since 2015.
CEO Lewis Black with clear words in CNBC interview
CEO Lewis Black emphasized Almonty's focus on supplying the defense industry in an interview with CNBC last Friday. According to Black, nearly 85% of current production - Almonty already operates a tungsten mine in Portugal - is already going to the defense sector. This focus will be maintained with the opening of the Sangdong mine. Black also explained the relocation of the Company's headquarters from Canada to the US – a move that had already been decided under the Biden administration – by saying that the Company wanted to be closer to its customers.
(link: https://youtu.be/g6pys3NNk44?si=zxQUtZgLcwciC29e
The fact that there is a lower price limit but no upper limit for the latest partnerships and purchase agreements shows that availability is more important to customers than price. The lower limit, in turn, gives Almonty important planning security.
Conclusion: Shares still worth buying
Overall, the lights are green for further price increases for Almonty shares. GBC Research's forecasts show that the stock is anything but expensive, even after tripling since the beginning of the year. This is also true when compared to companies like Rheinmetall, Germany's largest defense manufacturer, which, for example, requires tungsten for hardening ammunition, or the US raw materials company MP Materials. The comparison with MP Materials will likely come into sharper focus with the upcoming NASDAQ listing. By then at the latest, the share price should be heading towards GBC's price target. An entry at the current level appears to offer significant upside potential.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.