November 3rd, 2021 | 12:49 CET
Royal Dutch, BP, Saturn Oil + Gas: OPEC sends oil to 100 dollars!
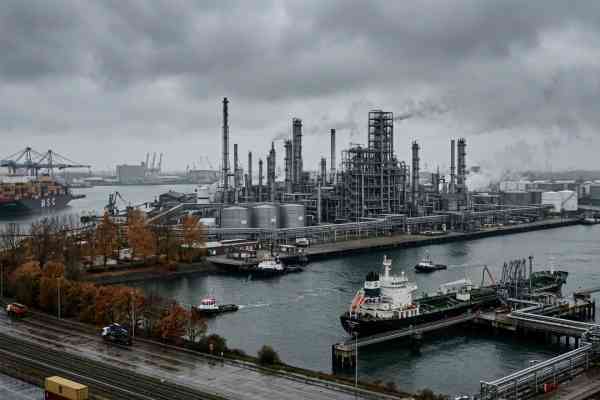
The oil rally continues! In October, the Brent and WTI grades recorded an increase of around 10%. Market observers justified the friendly month with the good mood on the stock markets. The risk appetite returned due to the turn of the markets at the beginning of October. More volatile asset classes such as commodities benefited from this. Time and again, reference is also made to fuel reserves in China, which had recently fallen sharply. The world's second-largest economy could now buy more on the oil market to strategically replenish its reserves. Tension is rising in the oil market. Which stocks can benefit in this environment?
time to read: 4 minutes
|
Author:
André Will-Laudien
ISIN:
ROYAL DUTCH SHELL A EO-07 | GB00B03MLX29 , BP PLC DL-_25 | GB0007980591 , Saturn Oil + Gas Inc. | CA80412L8832
Table of contents:
Author
André Will-Laudien
Born in Munich, he first studied economics and graduated in business administration at the Ludwig-Maximilians-University in 1995. As he was involved with the stock market at a very early stage, he now has more than 30 years of experience in the capital markets.
Tag cloud
Shares cloud
Royal Dutch Shell - Weak figures and pressure from hedge funds
In the last week of October, the A-share of Royal Dutch Shell (RDS) marked a new high for the year of EUR 21.70, but then the value went significantly downhill again. The reason was the slightly disappointing quarterly figures and the trouble with a new major investor from the hedge fund scene, who would like to split up the British-Dutch group.
The US hedge fund Third Point had recently acquired a stake worth EUR 643 million, making it one of the largest shareholders in the group. According to several media reports, Third Point is pushing for the oil and gas giant Shell to be split into two parts. One part of the Company is to continue to operate the traditional oil and gas business, but the renewable energy sector is to be spun off into a second division. The reason: Different investor interests repeatedly lead to strategic contradictions in the corporate strategy.
In the course of the current climate debate, this point cannot be dismissed entirely. Investors in RDS shares took cover for the time being and realized their lavish profits since the outbreak of the Corona Crisis, after all, by about 100%. Now oil fans are hoping for a turnaround with the upcoming OPEC date. The signs are good because the raw materials markets have been pointing upwards again for a few days. Fundamentally, the RDS share is trading at a 2022 P/E of 7.6, with a dividend yield of 4.6%. Buy in weakness!
Saturn Oil & Gas - Currently, there are many reasons to buy
The Canadian oil producer Saturn Oil & Gas from Saskatchewan is currently in very good shape. The WTI oil price has stabilized well above the USD 80 mark, which brings a lot of calm to Saturn's operating business. Far removed from the major political issues surrounding black gold, what is crucial for Saturn is its performance in its properties.
An important step in the share structure has now been taken in the past month of October. It is a consolidation of the shares in a ratio of 20:1, a so-called reverse split or rollback. In this context, the number of shares in circulation is reduced by a factor of 20. At the same time, the attributable price increases by the same ratio. As a result, the new Saturn share is now trading at over CAD 4.10, corresponding to an old share price of more than CAD 0.20. That is a strong performance of an even 100% since the acquisition of the Oxbow oil fields.
Saturn Oil is now producing about 6700 barrels of WTI in its new setup with revenues of CAD 520,000 per day. As a result, it will be relatively easy for the Company to pay off debt from the acquisition. According to current plans, Saturn will be debt-free in mid-2023 because, assuming a constant oil price over the next 18 months, it will flush a free cash flow of over CAD 260,000 into the books every day.
A strong buy argument for the stock, however, is its new unit size. Institutional investors find it challenging to invest in penny stocks; they need nominal share prices of over a dollar in addition to a capitalization of over CAD 100 million. However, this is now guaranteed - the current high turnover documents the increasing interest from large investors. If one now puts on the analytical glasses, one recognizes a complete deleveraging and a free cash flow valuation of about 1.5 on a view of 2 years. The P/E ratio puts itself on a cautious view at about 2 - to find a more favorable oil value on the price list should be very difficult.
British Petroleum (BP) - Good figures and a share buyback
Oil major BP has seen its quarterly profit well triple on the back of exceptional gas marketing, much higher oil prices and refining margins. Adjusted profit at replacement cost was USD 3.32 billion for the third quarter, a significant increase from USD 86 million for the same period in 2020. The increase is so dramatic because, in the wake of the Corona Crisis, oil prices had fallen as low as USD 35 in mid-2020. Oil demand has been rising strongly again in many countries since the falling Corona restrictions. Because the free cash flow has developed lushly upwards to a reasonable USD 6 billion, the Company now wants to put another billion amount into the share buyback.
However, BP recorded a special write-down due to outdated gas supply contracts and hedging transactions due to the rapid rise in gas prices. BP lost a handsome USD 6.1 billion before taxes in the derivatives sector, while the net loss attributable to shareholders still amounted to USD 2.5 billion after taxes. Officials said that the current disparity should subside again when spot prices for gas fall again and the planned volumes can be delivered. BP stands at EUR 4.10, around 7% below its 12-month high of EUR 4.40. Over the year, the oil and gas multinational is up 75%. Our multiple entry recommendations have worked out very well. Now hedge your holdings in BP shares with a raised stop at EUR 3.87 in the medium term.
Today, the investment in oil stocks is against the background of public efforts to achieve a phase-out of fossil energy. Currently, however, energy demand is going through the roof, and it does not look as if the demand side will weaken in the short term. Royal Dutch and BP are subject to many market volatilities. At the same time, the still small Saturn Oil & Gas from Canada can run a quiet and highly profitable business in the slipstream of the oil multinationals.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may in the future hold shares or other financial instruments of the mentioned companies or will bet on rising or falling on rising or falling prices and therefore a conflict of interest may arise in the future. conflict of interest may arise in the future. The Relevant Persons reserve the shares or other financial instruments of the company at any time (hereinafter referred to as the company at any time (hereinafter referred to as a "Transaction"). "Transaction"). Transactions may under certain circumstances influence the respective price of the shares or other financial instruments of the of the Company.
Furthermore, Apaton Finance GmbH reserves the right to enter into future relationships with the company or with third parties in relation to reports on the company. with regard to reports on the company, which are published within the scope of the Apaton Finance GmbH as well as in the social media, on partner sites or in e-mails, on partner sites or in e-mails. The above references to existing conflicts of interest apply apply to all types and forms of publication used by Apaton Finance GmbH uses for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and etc. on news.financial. These contents serve information for readers and does not constitute a call to action or recommendations, neither explicitly nor implicitly. implicitly, they are to be understood as an assurance of possible price be understood. The contents do not replace individual professional investment advice and do not constitute an offer to sell the share(s) offer to sell the share(s) or other financial instrument(s) in question, nor is it an nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but rather financial analysis, but rather journalistic or advertising texts. Readers or users who make investment decisions or carry out transactions on the basis decisions or transactions on the basis of the information provided here act completely at their own risk. There is no contractual relationship between between Apaton Finance GmbH and its readers or the users of its offers. users of its offers, as our information only refers to the company and not to the company, but not to the investment decision of the reader or user. or user.
The acquisition of financial instruments entails high risks that can lead to the total loss of the capital invested. The information published by Apaton Finance GmbH and its authors are based on careful research on careful research, nevertheless no liability for financial losses financial losses or a content guarantee for topicality, correctness, adequacy and completeness of the contents offered here. contents offered here. Please also note our Terms of use.