August 18th, 2026 | 07:30 CEST
Almonty Industries, Freeport McMoRan, and Albemarle: Commodity Fever Rises Due to Structural Shortages
A major storm is brewing in the commodity markets. It is being driven by the transition to climate-neutral energy, extremely high demand for artificial intelligence and the computing power it requires, and global geopolitical conflicts. This wave does not appear to be a temporary flare-up, but rather the beginning of a long-term megatrend, as supply deficits continue to widen. While spikes in demand often provided the boost in previous commodity cycles, this time it is global supply chain risks and decades of underinvestment in the development of new commodity projects. Today, we take a closer look at tungsten producer Almonty Industries, copper producer Freeport McMoRan, and lithium producer Albemarle.
time to read: 5 minutes | Author: Armin Schulz
ISIN: ALMONTY INDUSTRIES INC. | CA0203987072 | TSX: AII , NASDAQ: ALM , ASX: AII , FREEPORT-MCMORAN INC. | US35671D8570 , ALBEMARLE CORP. DL-_01 | US0126531013
Table of contents:
Author
Armin Schulz
Born in Mönchengladbach, he studied business administration in the Netherlands. In the course of his studies he came into contact with the stock exchange for the first time. He has more than 25 years of experience in stock market business.
Tag cloud
Shares cloud
Almonty Industries: Benefiting from the Geopolitical Shift
Tungsten has moved to the center of strategic considerations for governments and industries. What was once considered a niche product is now central to defense, aviation, semiconductor production, and energy infrastructure. Almonty Industries is one of the few notable Western producers outside of China's dominance. Its second-quarter financial results clearly underscore this. Revenue rose by nearly 500% to CAD 43 million. Adjusted EBITDA of CAD 17.6 million improved by more than CAD 22 million compared to the same period last year. However, the net income of CAD 181.8 million does not include non-operating, non-cash valuation effects from derivatives and warrants totaling CAD 173.1 million.
The company has secured additional growth through a USD 800 million convertible senior notes offering. Care was taken to limit dilution for existing shareholders to approximately 7% up to a share price of USD 41. The balance sheet now shows cash reserves of CAD 1.2 billion, which enables the simultaneous development of multiple projects. With the start of processing at the Sangdong mine in South Korea, the company has opened a new chapter. Approximately 120,000 metric tons of material with an average grade of 0.25% tungsten trioxide are available as stockpiled material and are being processed. In addition, there are 19,700 metric tons of newly mined ore.
The expanded offtake agreement with Global Tungsten & Powders also secures sales for the next two decades. The term was extended to 21 years, the total volume was increased by 40% to 4.41 million MTU, and the contractually agreed-upon price was improved by 6.3%. With this agreement, approximately 90% of Phase 1 production from Sangdong has been sold. This provides planning certainty. The company intends to focus entirely on NASDAQ trading in the future and the Frankfurt Stock Exchange and will delist from the TSX and ASX, given the recent very low trading volume on these exchanges. At the same time, the company is saving costs in this area. Since management considers the current share price to be too low, a USD 300 million share buyback program has been launched, under which up to 14.4 million shares can be repurchased.
Freeport McMoRan: Strong Results and Massive Investments
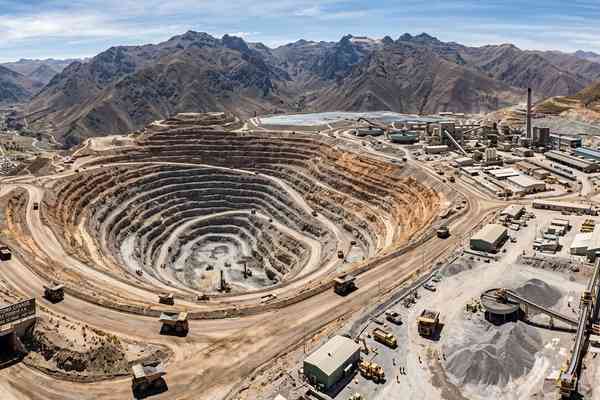
Freeport McMoRan's latest quarterly results show revenue of approximately USD 7 billion and earnings per share of USD 0.74. The US mines were particularly successful, quadrupling their operating contribution year-over-year. This resulted in a profit increase of about 65% in the first half of the year. One of the main drivers is the project in Indonesia. Production at the Grasberg Block Cave rose from 34,000 to 69,000 metric tons per day, exceeding even the company's own forecasts. The ramp-up is expected to continue. For the second half of the year, management is targeting a capacity utilization rate of around 65%. By mid-2027, this is expected to reach around 80%.
The outlook is certainly promising. For the coming year, the company expects copper sales to increase by over 20%. For gold, the increase is expected to be as high as 50%. The cost forecast for the current year is slightly lower than previously projected, which is a positive development. On the other hand, capital expenditures are enormous. The planned expansion in Bagdad, Arizona, is now expected to cost around USD 4.5 billion. That is one-third more than originally planned. The initial results from the new leaching process are promising and could have a positive impact.
Investors are currently paying a significant premium compared with many of its peers. The key question is whether the operational recovery and robust copper market justify this valuation. Share buybacks totaling more than USD 200 million suggest that management still considers the stock undervalued. One issue to keep an eye on is the extension of the Indonesian license, which is still pending. In addition, the stock is highly exposed to copper prices, which represents a key risk.
Albemarle: Between Pricing Power and Production Setbacks
Albemarle surprised even optimistic analysts in the second quarter. Revenue rose 31% to USD 1.74 billion. Adjusted earnings per share came in at USD 3.75, about 12% above the market consensus. Adjusted EBITDA doubled to USD 858 million. The 49% margin is impressive. The energy storage segment accounted for the lion's share of this growth. Here, revenue surged by a whopping 78% to USD 1.28 billion. It is worth noting that the average price of lithium climbed 60%, while the volume sold increased by only 11%. The lithium price was the real growth driver, not volume.
However, things will not continue quite so rosily. The CFO has already tempered the euphoria with a warning. The energy storage business is likely to suffer noticeably in the third quarter. He anticipates declining sales at lower prices. This is likely to put pressure on margins, especially since more expensive spodumene inventory will not be reflected in the figures until later. Compounding the problem is a fire at the Talison CGP3 plant. As a result, the ramp-up has been delayed until the first quarter of 2027. In addition, the conflict in the Middle East is causing supply chain disruptions that are estimated to cost Albemarle USD 70–90 million. RBC Capital subsequently lowered its Q3 EBITDA forecast from USD 763 million to USD 600 million.
Despite the short-term turbulence, the big picture continues to look good. Global lithium demand climbed 45% through May, and supply is barely keeping up. Stationary energy storage now accounts for about 30% of demand, bringing it close to the level of electric vehicles. There is also a lot happening on the technology front. Albemarle's La Negra DLE pilot plant in Chile is achieving recovery rates of over 90%. In terms of cost savings, the company is also on track to exceed its upper target of USD 150 million. One downside, however, remains the 2027 mandatory convertible bond, which is expected to result in a dilution of shareholders' equity of around 16%.
Commodity markets are facing a fundamental shift as supply chains must be secured. Almonty Industries is securing a key strategic role in tungsten outside of China through significant financing and long-term offtake agreements. Freeport McMoRan is delivering operational growth, but the high valuation and unresolved licensing issues in Indonesia remain risks. Albemarle impresses with strong margins but is struggling with short-term price declines. All three commodities remain exciting; discipline in execution is now the decisive factor for the companies' sustainable success.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.