March 18th, 2026 | 07:10 CET
Gold at USD 10,000? Analysts See Over 500% Upside Potential for Desert Gold
Will we see the price of gold reaching USD 10,000 per ounce in a few years? After JPMorgan CEO Jamie Dimon caused a stir last year with such a forecast, other prominent experts are now following suit. Among others, Ed Yardeni, President of Yardeni Research, Peter Schiff, Chief Strategist at Euro Pacific Asset Management, and Jefferies strategist Chris Wood also believe five-figure prices for the precious metal are possible in the coming years. Gold thus continues to promise investors glittering returns. Desert Gold could become a top performer in your portfolio as early as this year. Analysts see over 500% upside potential.
time to read: 3 minutes | Author: Fabian Lorenz
ISIN: DESERT GOLD VENTURES INC | CA25039N4084 | TSXV: DAU , OTCQB: DAUGF
Table of contents:
Author
Fabian Lorenz
For more than twenty years, the Cologne native has been intensively involved with the stock market, both professionally and privately. He is particularly passionate about national and international small and micro caps.
Tag cloud
Shares cloud
Multiple Catalysts
Regardless of the potential USD 10,000 per troy ounce, investors could soon experience golden times with Desert Gold. The company is among the most exciting gold stocks and could really take off in 2026. That is because there are several catalysts: the transition to production, significant exploration potential, and fresh capital in the coffers. Most recently, CEO Jared Scharf emphasized in an interview with Lyndsay Malchuk of the International Investment Forum that the recently completed financing of over CAD 7.2 million will allow the company to accelerate progress on multiple fronts. The funds are intended to bring the first phase of a gravity plant at the Mali project online. This could happen as early as June. Desert Gold is also using the funds to finance further drilling in Mali as well as initial work on the project in Côte d'Ivoire.
Fast, Cost-Effective Entry into Production
The strategy in Mali is particularly interesting. Scharf made it clear that the economic assessment to date captures only a small portion of the total potential. The PEA primarily refers to near-surface oxide mineralization and thus only to about 10% of the currently known resource of approximately 1.3 million ounces. Even at a gold price of just USD 3,000 per ounce, the internal rate of return (IRR) of the initial PEA stands at 57%. The net present value (NPV 10%) after taxes is over USD 61 million. This suggests potential upside relative to the current valuation. From management's perspective, this represents a rapid, cost-effective entry into production. The idea behind it is compelling. With a comparatively straightforward start to production, the aim is to generate cash flows to finance further exploration without unduly diluting shareholders. Furthermore, the start of production could attract new, financially strong partners to jointly ramp up production more quickly. It is precisely this combination of short-term monetization and long-term leverage from additional discoveries that makes the investment case particularly compelling.
Tiegba Gold Project Could Deliver Positive Upside
The company's second pillar in Côte d'Ivoire offers additional upside potential. There, Scharf sees the Tiegba Gold project as a potential surprise factor for the market. The area lies on a promising trend, covers around 300 sq km, and contains a geochemical anomaly several kilometers long that was previously delineated but never systematically drilled. Desert Gold has confirmed the anomaly and plans to test it specifically following a drone survey. This opens up a second opportunity for a significant new discovery alongside the advanced Mali project. It is precisely this combination of financing security, operational progress, production prospects, and additional exploration leverage that could make Desert Gold THE gold stock of 2026.
https://youtu.be/dd2rbdGuZDo?si=XHECivSVJKODatxg
The Stock Has Finally Broken Out
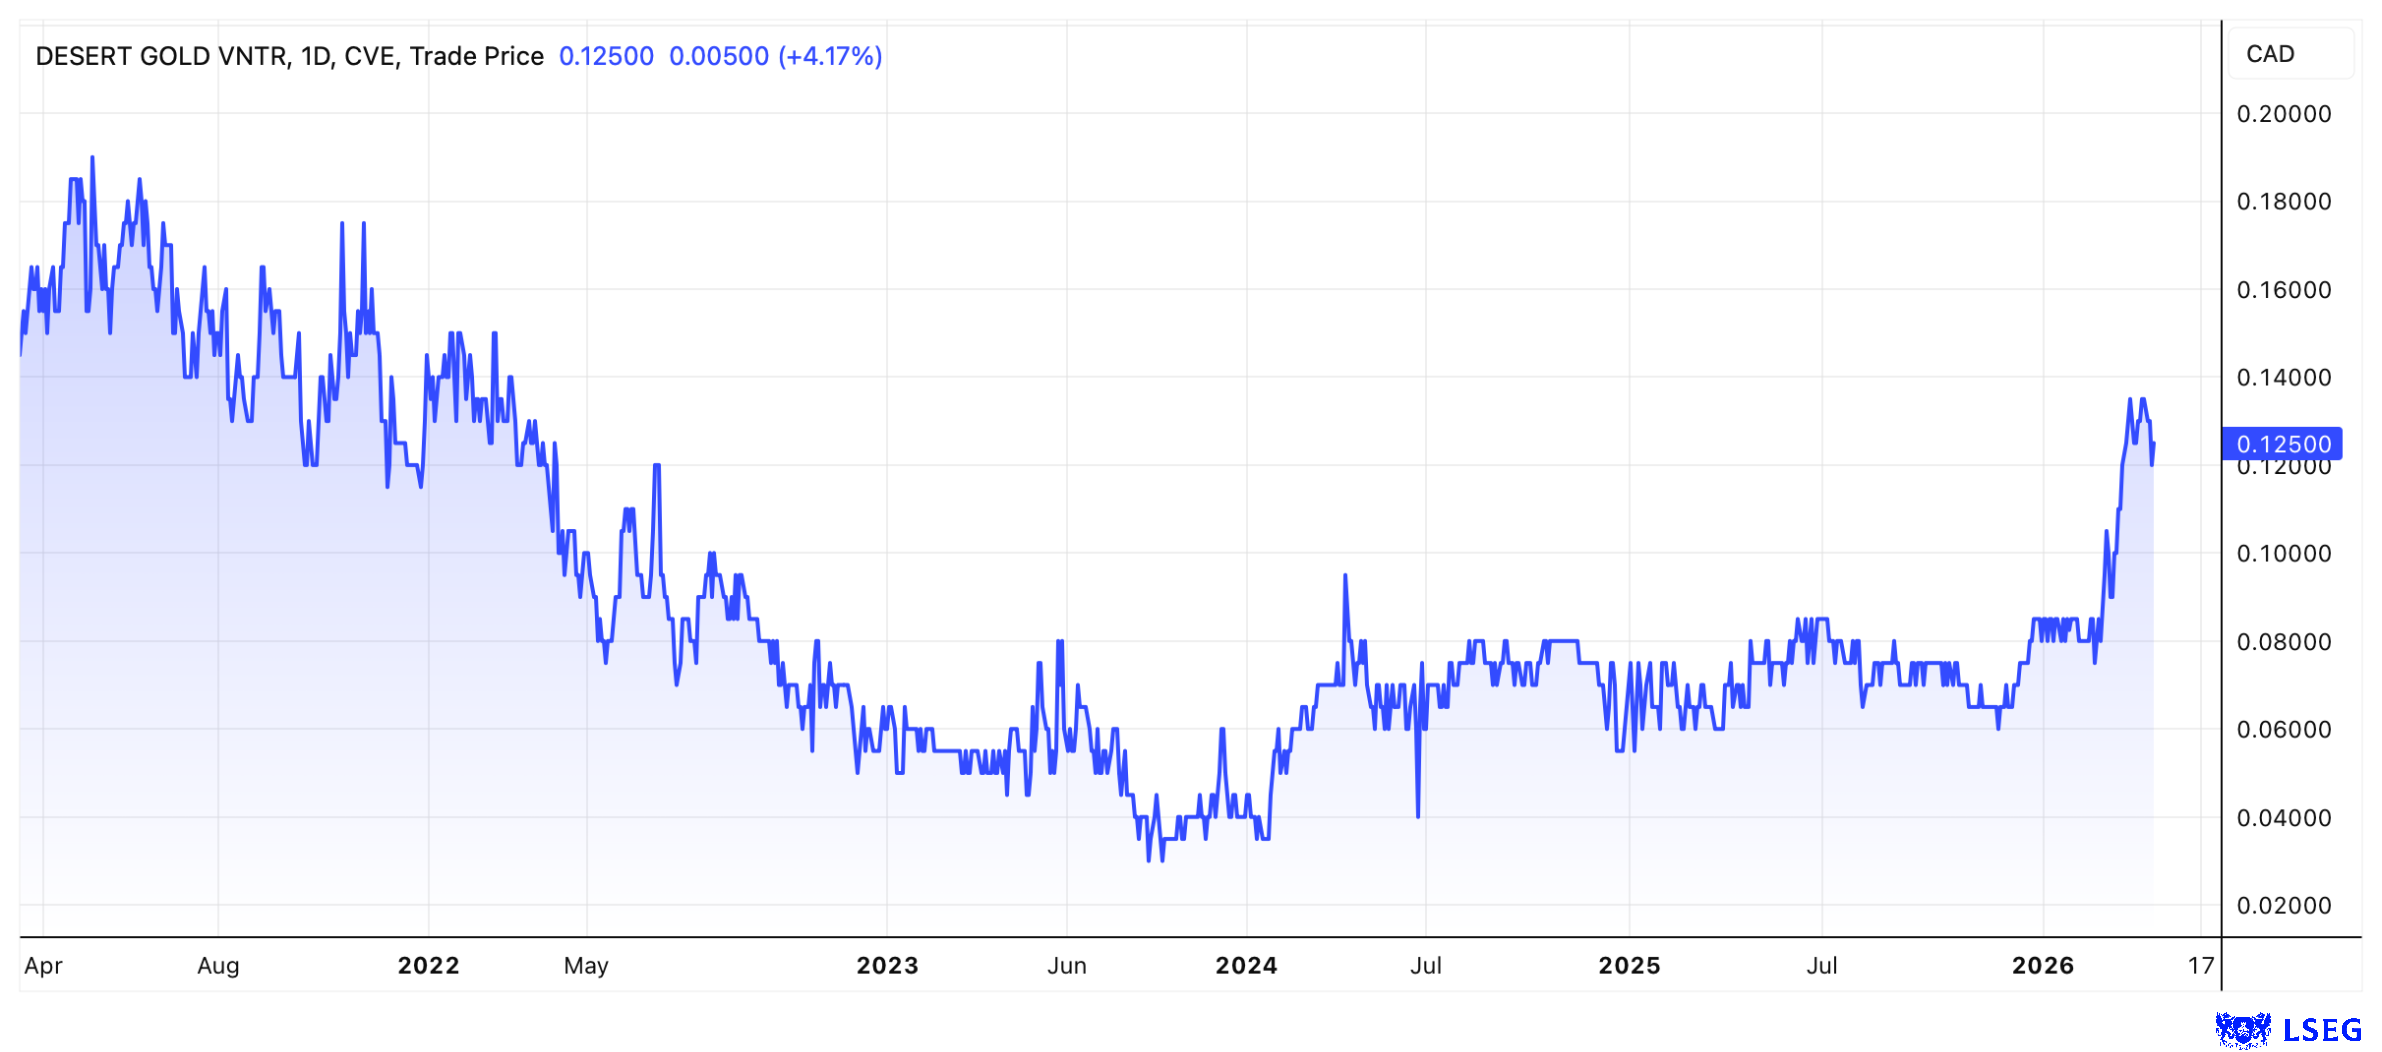
The stock's price performance over the past few weeks shows that the story now makes perfect sense. The stock has jumped from EUR 0.05 to EUR 0.08. However, this has merely initiated the revaluation. After all, the stock was at this level back in 2022. At that time, the gold price was quite different, and the project in Côte d'Ivoire did not yet exist. Analysts at GBC Research continue to recommend Desert Gold shares as a "Buy". They estimate the stock’s fair value at EUR 0.59, implying significant upside potential.
Conclusion: Over 500% Upside Potential and Takeover Speculation
From the perspective of GBC analysts, Desert Gold shares thus have over 500% upside potential. As described, there are good reasons to believe the stock can reach this level. And then there is the takeover potential. With reserves of 1.3 million ounces and further potential, the company has the necessary scale to be attractive to a larger producer.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.