April 30th, 2026 | 06:50 CEST
DEFENSE, RAW MATERIALS, RETURNS: POWER METALLIC MINES, ERAMET, AND NICKEL INDUSTRIES FACE A STRESS TEST
While gold and silver have lost significant ground following their price surge at the start of the year, other precious metals are attracting investors' attention. Leading the way is nickel, an indispensable raw material for the defence industry. The price per ton has just climbed to a new multi-year high above USD 19,000. We take a look at what this means for the shares of Power Metallic Mines, Eramet, and Nickel Industries.
time to read: 8 minutes | Author: Jens Castner
ISIN: POWER METALLIC MINES INC. | CA73929R1055 | TSXV: PNPN , OTCBB: PNPNF , ERAMET SA INH. EO 3_05 | FR0000131757 , NICKEL INDUSTRIES LIMITED | AU0000018236 | ASX: NIC
Table of contents:
Author
Jens Castner
The Nuremberg native brings over three decades of capital markets experience, backed by a career shaped by deep market insight and a genuine passion for investing. His journey began in 1994 through an investment club among colleagues – a formative experience that sparked a lifelong dedication to identifying compelling investment opportunities.
Following senior editorial roles at Nürnberger Nachrichten, €uro am Sonntag, and €uro, he went on to serve as Editor-in-Chief of the renowned investor magazine Börse Online from 2014, where he played a key role in shaping high-quality financial journalism for a broad investor audience.
Tag cloud
Shares cloud
BETWEEN AMMUNITION AND MEGAWATTS: THE NEW NICKEL BOOM
Even though the guns are currently silent in the Middle East, the conflict between Israel and the US on one side and Iran on the other is by no means over. Even if hostilities do not resume, the US military has expended so much ammunition that replenishing stocks is a top priority. In March 2026, the Pentagon began massively replenishing the National Defense Stockpile. Since nickel is required for both armor steel and high-penetration ammunition, as well as for nuclear submarines, missile systems, and high-performance engines, the US Department of Defense has specifically commissioned projects to reduce dependence on imports—particularly from China and Russia.
Another factor contributing to the rise in nickel prices is that Indonesia, the actual market leader, has capped mining quotas for 2026, further fueling concerns about a supply shortage. In nickel production, sulfur, mostly in the form of sulfuric acid, is necessary to extract the metal from the ore. Without sufficient sulfuric acid, production in modern facilities comes to a complete standstill. Although sulfur is produced worldwide as a byproduct of oil and gas refining, the blockade of the Strait of Hormuz has disrupted key supply chains and further exacerbated the nickel shortage. Indonesian plants have already had to cut production by at least 10%. In addition, high oil prices are driving up the costs of energy-intensive refining and transportation significantly.
POWER METALLIC MINES: SULFUR IN THE ROCK INSTEAD OF IN THE TANK
The situation is a perfect fit for Power Metallic Mines. The Canadian company sits on nickel deposits extracted from sulfide ores. The advantage: the required sulfur is already present in the rock, which offers significant cost advantages compared to the production of laterite ores common in Indonesia. The carbon footprint is also drastically reduced, as the processing of laterite ore using high-pressure acid leaching or smelting processes is extremely energy-intensive. In Indonesia, these facilities are often powered by coal-fired power plants, resulting in emissions of about 40-60 tons of CO₂ per ton of nickel. For sulfide projects in Canada, which mostly use hydroelectric power, this figure is often only one-fifth of that.
Since the NISK project—Power Metallic Mines's potential flagship nickel asset, located about 700 km north of Montreal, is situated in close proximity to a Hydro-Québec substation, near CO₂-free production is more than just a vision. Industry analysts, such as those at Benchmark Mineral Intelligence, estimate that the green premium for clean nickel from stable regions like Canada can range from 10 to 15% above the standard price. That would correspond to a bonus of about USD 2,000 to USD 3,000 per ton. But that is not all: Canada is also leading the way in waste management.
Conventional nickel smelting processes produce enormous amounts of acidic sludge, some of which is still disposed of in the ocean, posing a massive threat to ecosystems. Sulfide mines in stable regions like Québec typically store waste in controlled onshore basins or even use it for CO₂ sequestration in rock. In addition, sulfur can often be efficiently recovered during smelting and sold as a byproduct, rather than ending up as waste or a cost factor.
THE HIDDEN RESERVE IN THE GROUND: PRECIOUS METALS AND COPPER
Given all these advantages, the question arises: Why can't Power Metallic Mines' stock benefit from the soaring nickel price? The share price, currently at EUR 0.71 on German exchanges, has settled above CAD 1.00, but upward momentum has recently been lacking. The crux of the matter is that the Toronto-based company is not yet in production. Extensive drilling programs are currently underway, which have also revealed extremely high concentrations of gold, silver, platinum, palladium, and, above all, copper in the neighbouring Lion Zone. The polymetallic deposit is of crucial importance, as these raw materials are also considered critical to national defence. The defence industry needs them for rockets, engines, batteries, and guided missiles, among other things; furthermore, they are in high demand in the electric vehicle and tech industries.
Since it typically takes three to five years for a mine to begin production due to lengthy permitting processes, management intends to initially focus on the easier-to-mine, high-grade copper and precious metal deposits in the Lion Zone—a reason, incidentally, why the company changed its name from Power Nickel to Power Metallic Mines a little over a year ago.
By directly supplying high-grade ores to regional smelters, cash flow can be generated much more quickly than through the traditional construction of a large-scale mine. Therefore, the company is aiming for an accelerated production start in the Lion Zone as early as 2027. Whether the proceeds from copper and precious metals will be used in the future to advance large-scale nickel mining in the NISK zone remains to be seen.
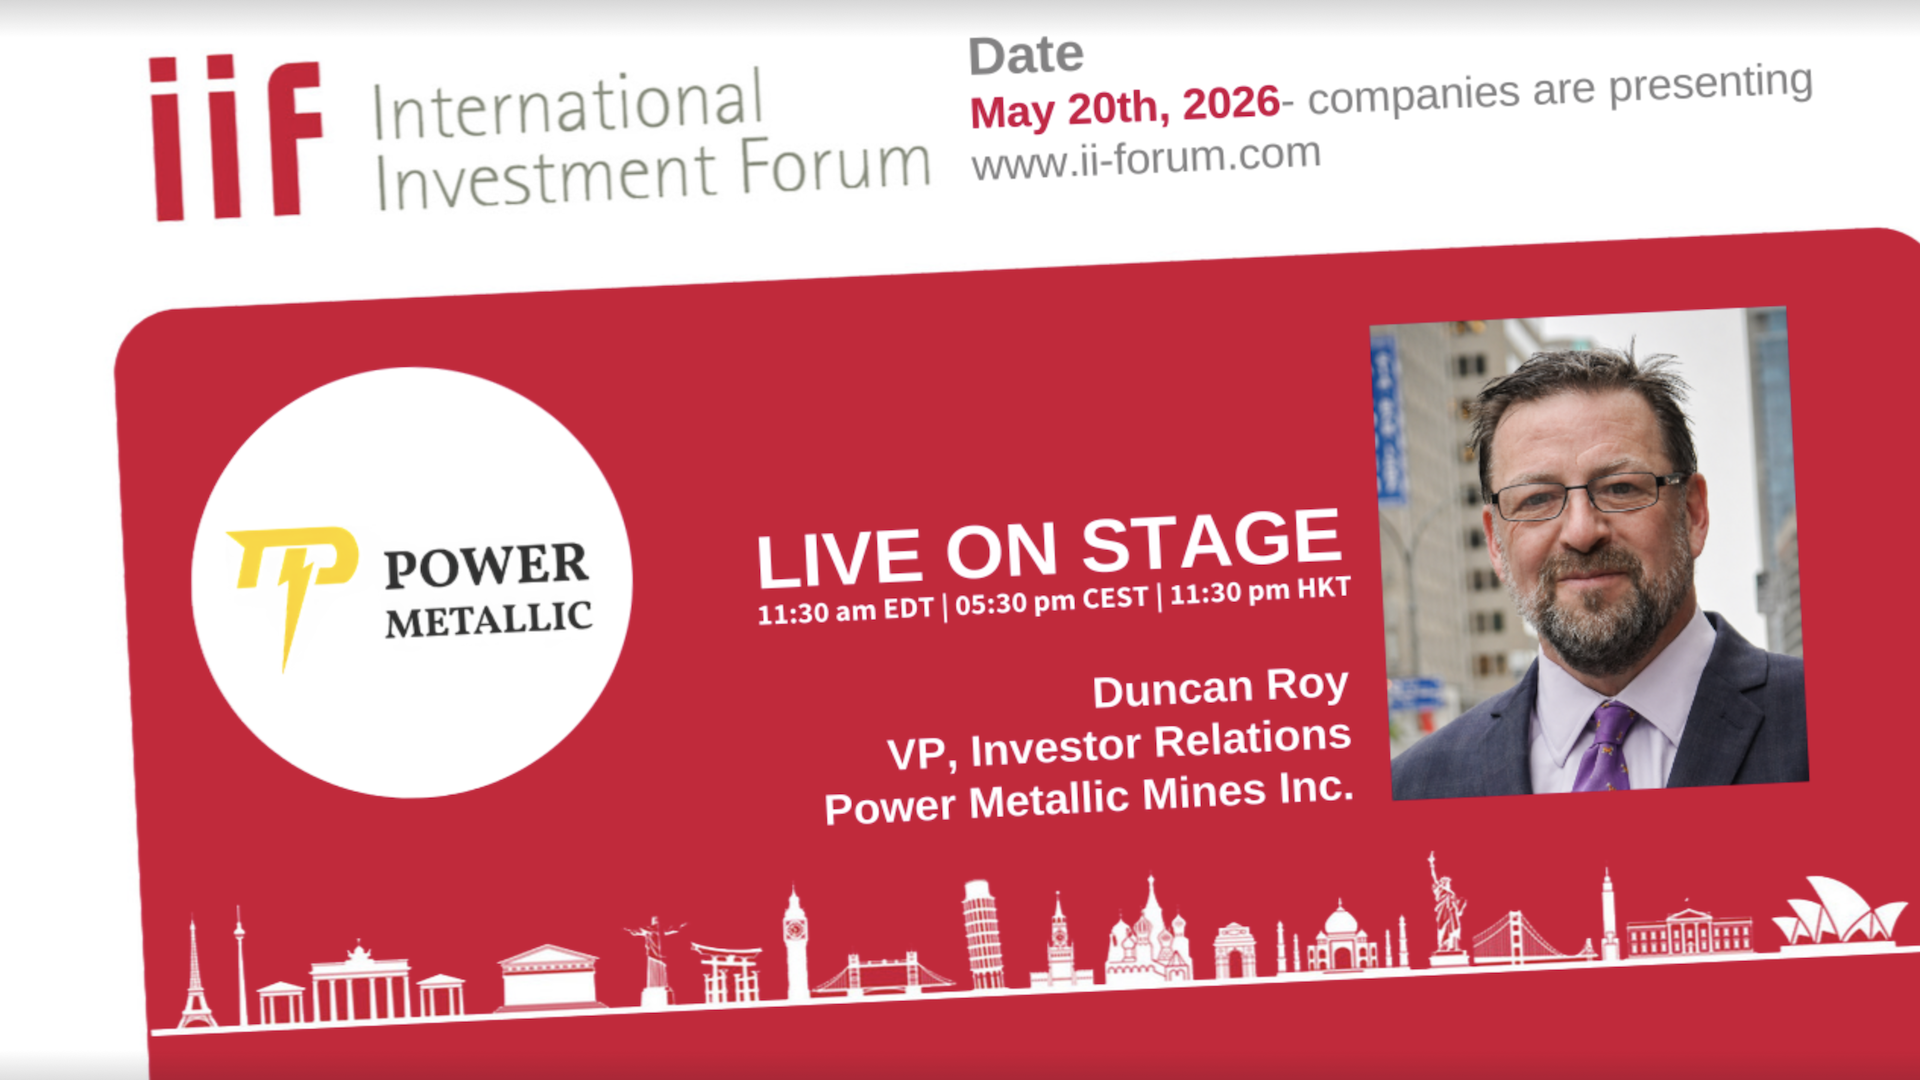
The fact is: Given the high price, the nickel deposits are attracting interest. A sale or even a takeover of the entire company by larger mining groups such as Glencore or Vale, which are active in the surrounding area, could also be conceivable. Duncan Roy, VP, Investor Relations, will provide deeper insight into management's strategy on Wednesday, May 20, at 5:30 pm CEST during the International Investment Forum (IIF). Click here to register.
ERAMET: A GIANT IN SEARCH OF STABILITY
It may be cold comfort for Power Metallic Mines shareholders, but even established competitors are struggling to keep up with nickel prices. One of Europe's leading nickel producers is Eramet. The French mining group is considered a veteran of the industry, but currently appears to be a giant in trouble. Although its business model is broadly diversified, with a focus on manganese and a new lithium division in addition to nickel, its geographic spread is both a blessing and a curse. While the manganese mines in Gabon are operating stably, the nickel division in the French overseas territory of New Caledonia is becoming a chronic problem child. High energy costs and ongoing political unrest are severely impacting profitability. The protests, which culminated in massive violence and the imposition of a state of emergency in 2024, were triggered by a planned constitutional reform by the French government to expand voting rights. The indigenous population feared this would lead to a loss of political influence and weaken their independence efforts. Major transportation routes and mine access points were paralyzed by blockades, and nickel processing plants had to temporarily suspend operations or reduce them to a minimum. This also affected the Eramet subsidiary Société Le Nickel (SLN), which consequently ran into financial difficulties.
Added to this is the costly expansion of the lithium business in Argentina and, to some extent, in Alsace. Following deep losses last year, analysts also expect losses for 2026 and 2027. At the start of the year, the stock saw a brief surge from EUR 55 to nearly EUR 88 as the company celebrated the successful ramp-up of lithium production with the market, which investors interpreted as a signal of its transition to a green metal producer. But by February, it was back to square one: Disastrous annual figures due to low manganese prices and the weak US dollar, combined with problems in the South Pacific and Indonesia, caused chaos at the company's headquarters in Paris. CEO Paulo Castellari was dismissed in early February 2026—just under three weeks before the earnings press conference. Abel Martins-Alexandre, the CFO appointed only recently, was also temporarily suspended, shattering investor confidence. From an investor's perspective, Eramet is currently less of a nickel growth stock and more of a risky bet on a successful restructuring and on stable global manganese market prices.
Since a return to profitability is not expected before 2028, the investment risk is by no means lower, despite a market capitalization of around EUR 1.5 billion, nearly 10 times that of the small-cap Power Metallic Mines.
NICKEL INDUSTRIES: THE DIVIDEND MACHINE WITH THE COAL STAIN
Nickel Industries is performing significantly better. Even though the stock is still far from its all-time high of AUD 1.65 from spring 2022, it has recently followed the nickel price on its upward trajectory. In record time, the company has risen to become the world's largest publicly traded pure-play nickel producer through close partnerships with Chinese giants such as Tsingshan. The epicenter of its success lies in Indonesia. However, this also has its downsides. The business model is based on precisely those laterite ores whose processing consumes enormous amounts of coal-based energy. As a result, the Australians are anything but role models when it comes to sustainability. The consequences have already come from Washington: the US Inflation Reduction Act threatens to impose tax disadvantages on nickel produced in Indonesia and China, complicating access to one of the most important markets.
On the other hand, the stock is considered a reliable dividend machine with a yield of 3 to 5%. A dividend of AUD 0.06 is expected for 2028, which, at the current price of just under AUD 1.00 (EUR 0.62), would correspond to a yield of 6%. According to consensus estimates, the company is expected to generate earnings of AUD 0.10 per share next year. This translates to a favourable price-to-earnings (P/E) ratio of 10—the perception of nickel as environmentally problematic appears to be acting as a drag on the valuation. There is, however, potential in cobalt production, which is set to expand from 800 to 4,000-5,000 tons per year within two years. However, the company is dependent on Chinese partners here, just as it is with nickel production. A certain political risk, therefore, cannot be ruled out. Nevertheless, analysts see an average upside potential of around 25% for the Sydney-based group, which is valued at AUD 4.3 billion, while the majority currently advise a wait-and-see approach regarding Eramet.
GREEN BEATS BIG: WHY THE JUNIOR COULD HAVE THE EDGE
A direct comparison reveals stark contrasts: The French stalwart Eramet is struggling with high costs and political unrest in New Caledonia, and management chaos has shaken investor confidence. Nickel Industries, on the other hand, delivers enormous volumes and offers an attractive dividend yield, but is in the crosshairs of Western regulatory authorities due to its reliance on Indonesian coal and its proximity to China. However, the stock correlates closely with the commodity price. According to analysts at GBC Research, Power Metallic Mines has enormous potential. The price target of CAD 2.85 is well over 100% above the current trading price. The combination of political stability in Canada and the opportunity to begin production as early as 2027 makes the company a top contender for the new era of commodity supply. The potential revenue from nickel production with a green CO₂ profile in a few years' time provides additional upside potential in the long term. Since the Canadian company has not yet generated any meaningful revenue, the risk is by no means negligible.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.