August 11th, 2026 | 07:05 CEST
Why the Greenhouse Gas Methane Threatens Baker Hughes and Shell – and How Zefiro Methane Is Capturing a Billion-Dollar Market
Across the United States, inconspicuous, rusted steel pipes can often be found protruding from the ground away from major roads. Although officially classified as orphaned, these former oil and gas wells represent a significant environmental liability: more than 2 million unplugged wells have been left behind by oil and gas operators over the decades. They continue to release methane, a highly potent greenhouse gas. According to US authorities, these emissions are expected to be addressed as quickly as possible. This is turning a legacy environmental problem into a potentially multi-billion-dollar niche market. In this article, we explain the background and take a closer look at Zefiro Methane, a potential beneficiary of this emerging market.
time to read: 3 minutes | Author: Nico Popp
ISIN: ZEFIRO METHANE CORP | CA98926D1069 | NEO: ZEFI , BAKER HUGHES CO. | US05722G1004 , Shell PLC | GB00BP6MXD84
Table of contents:
Author
Nico Popp
At home in Southern Germany, the passionate stock exchange expert has been accompanying the capital markets for about twenty years. With a soft spot for smaller companies, he is constantly on the lookout for exciting investment stories.
Tag cloud
Shares cloud
Shell Focuses on Its Core Business and Relies on External Partners for Sustainability
The global energy giant Shell is once again focusing primarily on maintaining high cash flows in its traditional oil and gas business. Conducting its own labor- and equipment-intensive cleanup operations at old production sites simply does not fit into this strategy. Instead of allocating its own resources to the costly removal of historic drilling sites, the British company prefers to outsource such tasks to specialized service providers. At the same time, Shell is driving its green transformation through targeted partnerships. Shell Energy signed an agreement with Baker Hughes regarding the Zamboni solar park in Italy to supply seven industrial sites and reduce on-site emissions by approximately 13%.
Baker Hughes Shines with Record Orders
US oil equipment supplier Baker Hughes is benefiting from the global expansion of gas and energy infrastructure. The company has a full order book and provides solutions for the oil and gas industry worldwide. In the most recent quarter, Baker Hughes reported revenue of USD 6.7 billion and adjusted earnings per share of USD 0.64. With an operating EBITDA margin of 18.3%, the US company's profitability is extremely robust. Baker Hughes' order backlog climbed to USD 40.1 billion. Among other things, the company provides high-end compressors, LNG technology, and—through its portfolio company Chart Industries—complex process plants. However, it leaves the detailed field remediation at the end of the life cycle of decommissioned infrastructure entirely to other players.
Zefiro Methane Taps into the Profitable Environmental Niche
This is precisely where Zefiro Methane comes in with its vertically integrated model. The US company transforms the enormous environmental burdens of abandoned wells into a predictable and high-margin business model. According to industry estimates, the market size for the remediation of abandoned and orphaned wells in North America ranges between USD 280 billion and USD 500 billion. According to official calculations by the US Environmental Protection Agency (EPA), approximately 7 to 20 million metric tons of CO₂ equivalent escape into the environment annually from unplugged wells. Zefiro Methane is tackling this monumental task with a three-pronged approach consisting of field remediation, measurement technology, and the generation of certified emission credits. Zefiro successfully completed a major project in Custer County, Oklahoma, and recorded 92,956 metric tons of CO₂ equivalent in certified credits according to the American Carbon Registry (ACR) methodology.
Mercuria Energy America, a global commodities trader, had already secured these emission credits in advance through a firm offtake agreement. The ACR's requirements are considered stringent, as even minimal methane leaks starting at 1 g CH₄/h must be verified with a maximum tolerance of 20%. US policy provides additional momentum for Zefiro. The IIJA federal funding program is providing USD 4.7 billion in public funds through the Federal Orphaned Wells Program. Zefiro aims to secure as large a slice of this pie as possible.
Capital Expenditures Drive Zefiro Methane's Revenue
To handle growing order volumes, Zefiro Methane is focusing on targeted acquisitions and the expansion of its subsidiary Plants & Goodwin. For a purchase price of USD 4.3 million, Zefiro Methane acquired the fleet of Viking Well Service, thereby expanding its operational capacity. This surge in capacity immediately bore fruit in the company's operations. A natural gas customer that has been awarding annual contracts to Zefiro since 2017 expanded its 2026 workover campaign from one to three drilling crews, which is expected to generate an estimated additional revenue of approximately USD 10 million. In addition, Plants & Goodwin won four new customers, including three publicly traded corporations with a combined market capitalization of over USD 140 billion. In the first three quarters of fiscal year 2025, revenue climbed 5% to USD 24.4 million. In the third quarter of fiscal year 2026, growth even accelerated by 58% compared to the same quarter of the previous year. At the same time, Zefiro Methane reduced its debt burden from USD 12.3 million to USD 8.2 million and raised CAD 3.3 million in fresh equity through a financing round. The appointment of CFO Correne Loeffler, who brings industry experience from Callon Petroleum, and trading expert Tina Reine, who previously helped build the carbon trading desk at JPMorgan, significantly strengthened the management team led by CEO Catherine Flax.
Zefiro Methane Attractive According to Analysts
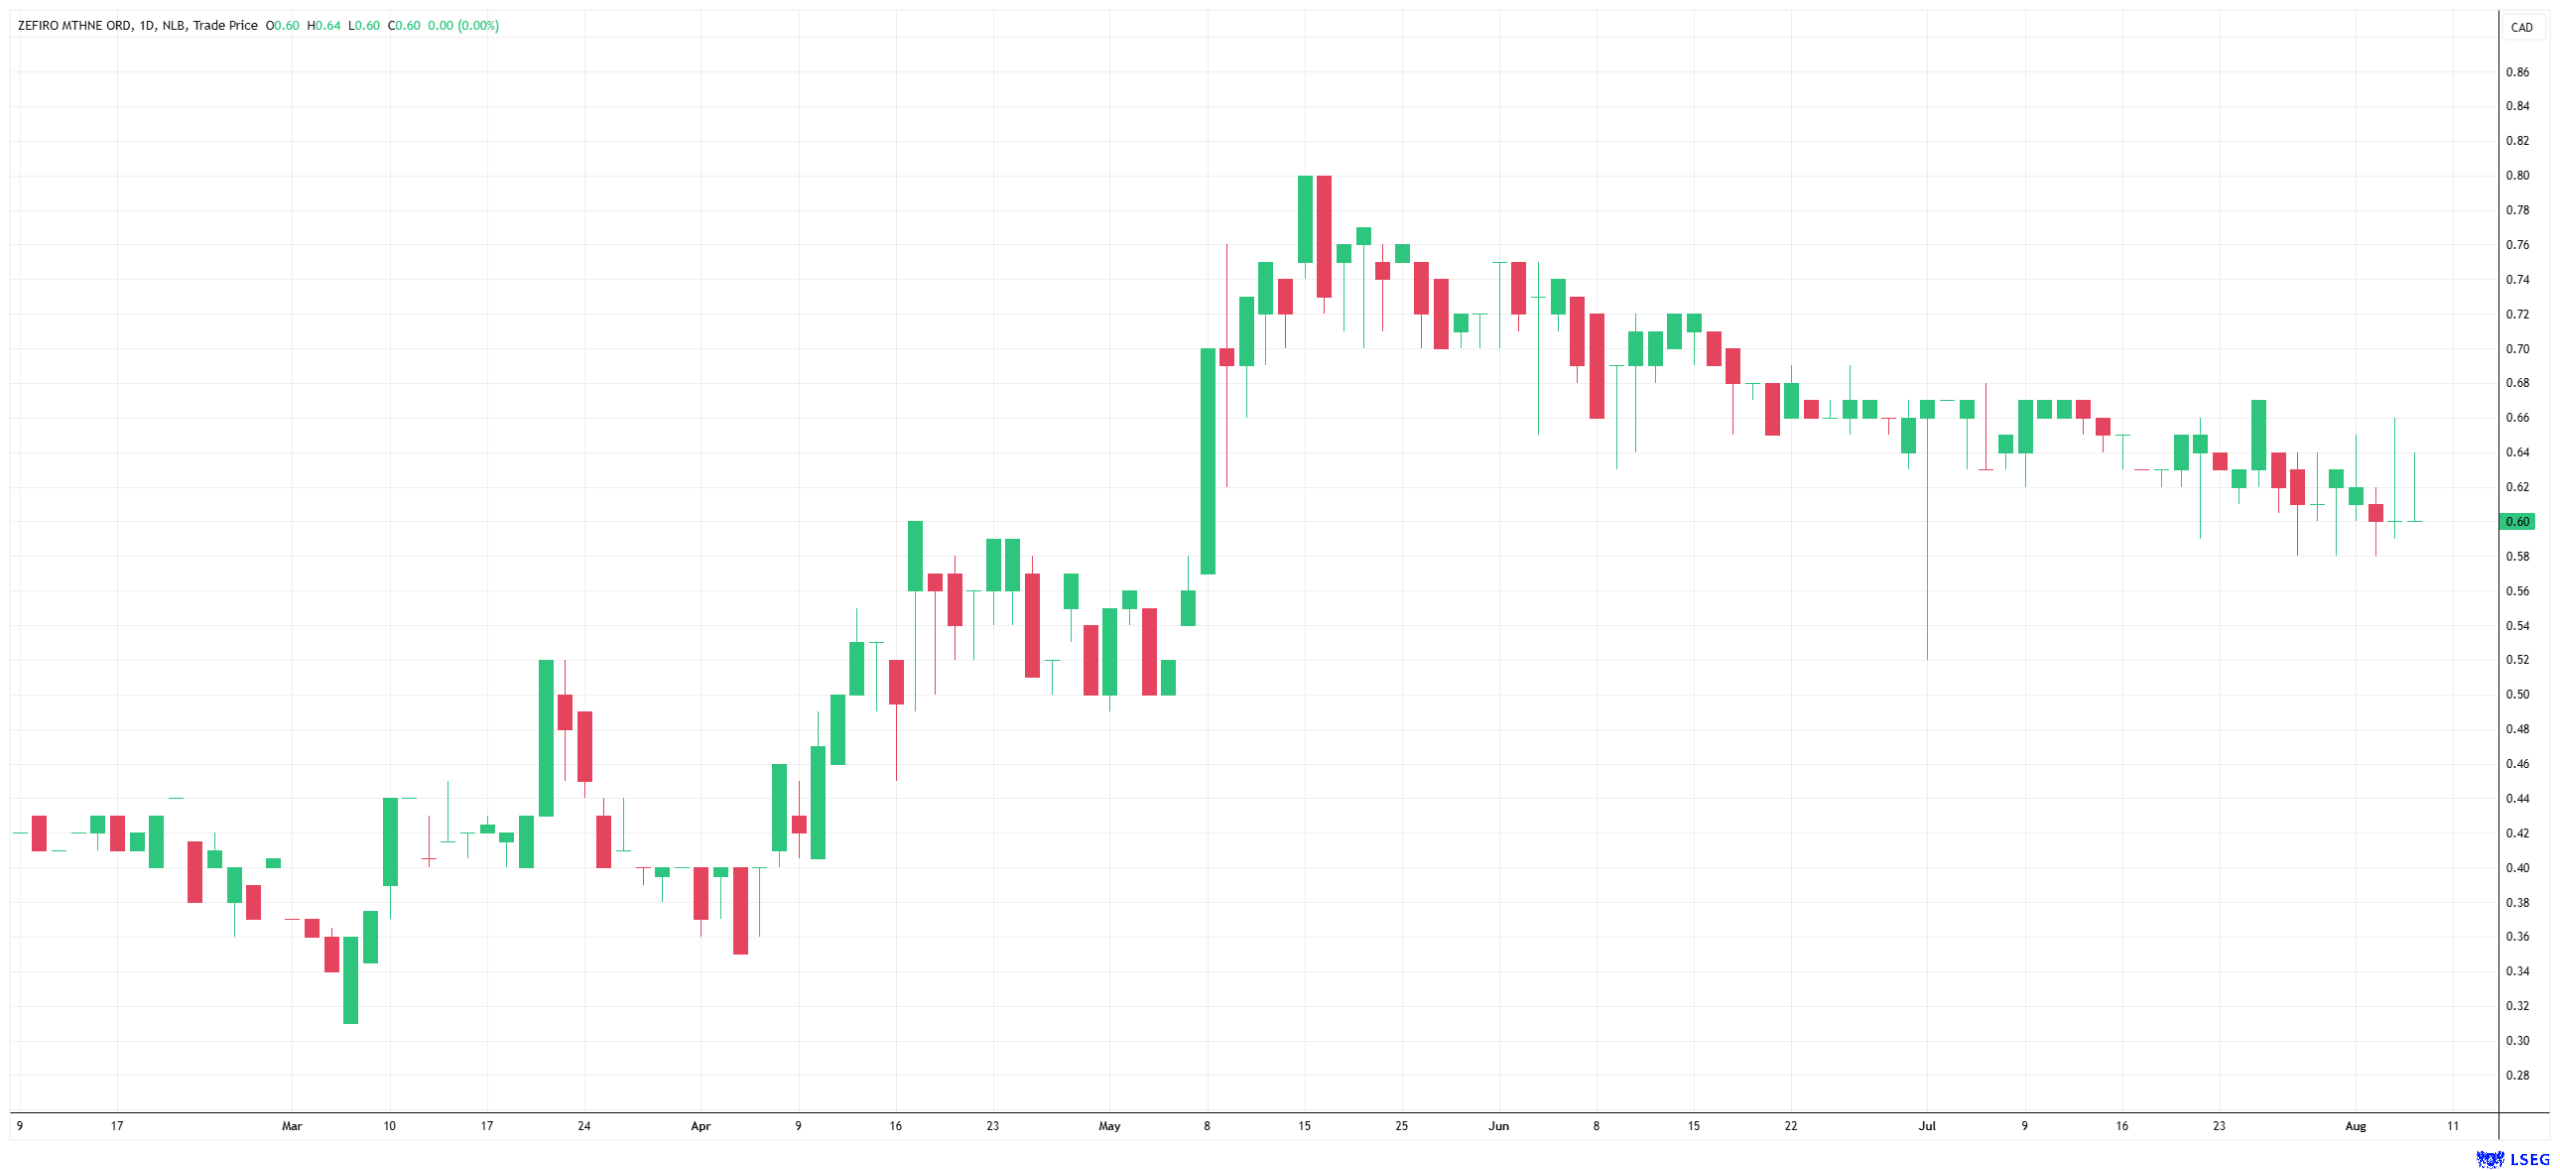
Analysts at GBC AG have initiated coverage of Zefiro Methane with a "Buy" rating and price targets of USD 1.50 and CAD 2.12, respectively. In their initial report, the market experts note that the company is exceptionally well-positioned to benefit from the significant need for remediation of abandoned wells in the US. Key growth drivers include government incentive programs and rising demand from private energy and data center developers. Following a dynamic breakout a few months ago, the share has pulled back and is now worth another look.
Watch YouTube videoConflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.