November 13th, 2026 | 05:40 CET
Funding for Green Power: RWE Brings KKR on Board, NextEra Bets on Storage – RE Royalties Finances Smaller Projects
Building projects requires capital – often more than even a group like RWE is willing to shoulder on its own. The Essen-based company is bringing financial investor KKR on board for two British offshore wind farms, while NextEra is filling its order book with battery storage projects in the US. But who finances the many smaller solar and storage projects that hold little appeal for major banks? This is where Vancouver-based RE Royalties comes in: the company provides capital to developers in return for a share of the revenue generated by their assets.
time to read: 3 minutes | Author: Nico Popp
ISIN: RE Royalties Ltd | CA75527Q1081 , RWE AG INH | DE0007037129 , NEXTERA ENERGY INC.DL-_01 | US65339F1012
Table of contents:
Author
Nico Popp
At home in Southern Germany, the passionate stock exchange expert has been accompanying the capital markets for about twenty years. With a soft spot for smaller companies, he is constantly on the lookout for exciting investment stories.
Tag cloud
Shares cloud
RWE: Gigawatt expansion and private equity partnerships
Essen-based group RWE is setting the pace in Europe. On November 11, RWE reported adjusted EBITDA of EUR 4.575 billion for the first three quarters, an increase of 35% year on year. The group expects to reach the upper end of its full-year guidance. In the first nine months of the year, RWE invested a net EUR 10.7 billion and is currently building new facilities with a capacity of 13.5 GW worldwide. To reduce net debt to around EUR 12 billion by year-end, the company is sharing large-scale projects with partners. RWE will operate the British offshore wind farms Vanguard West and East, with a combined capacity of 2.8 GW, in a joint venture with financial investor KKR, with each holding a 50% stake.
NextEra Energy: US growth and structural bottlenecks
In the US, NextEra Energy is showing comparable momentum. The group is the largest US operator of wind, solar and storage facilities. In the third quarter alone, the development division added 3.7 GW of new projects to its backlog, of which 2.4 GW is battery storage. The situation is different for smaller project developers: in the US, they often wait years for a grid connection, which is why energy regulator FERC has reformed the process. For projects in the single-digit to low double-digit millions, the due diligence effort is also often not worthwhile for major banks.
RE Royalties: Revenue participation for smaller projects
This is precisely where RE Royalties comes in. Instead of acquiring equity stakes, the company provides growth capital – usually in return for a share of the facilities' future gross revenues, sometimes also as a loan. For independent developers, this offers the advantage of gaining rapid access to capital without giving up their own voting rights. Because the participation is directly linked to revenue, rising operating costs at the facilities do not directly affect RE Royalties. The portfolio comprises over 100 revenue participations in solar, wind, hydropower, biogas and storage facilities in North America, South America and Asia.
Recent transactions show what this looks like in practice. In October, RE Royalties acquired a revenue participation in nine solar installations on the roofs of Philippine shopping centres, with a combined capacity of 14.2 MW, for USD 1.5 million. The installations are already operating, with payments made quarterly. Partner Singapore Solar also has projects totalling more than 700 MW in the pipeline in Southeast Asia. In the US, RE Royalties has so far invested USD 4.8 million in 16 smaller solar projects by developer Solaris Energy. A non-binding letter of intent (LOI) provides for up to USD 67.5 million for around 100 further projects. A case from Wisconsin shows the model's lasting effect: a biogas developer has repaid a USD 4.6 million loan in full, yet RE Royalties will still receive 4% of the capital deployed annually for 10 years.
Green capital and strategic review
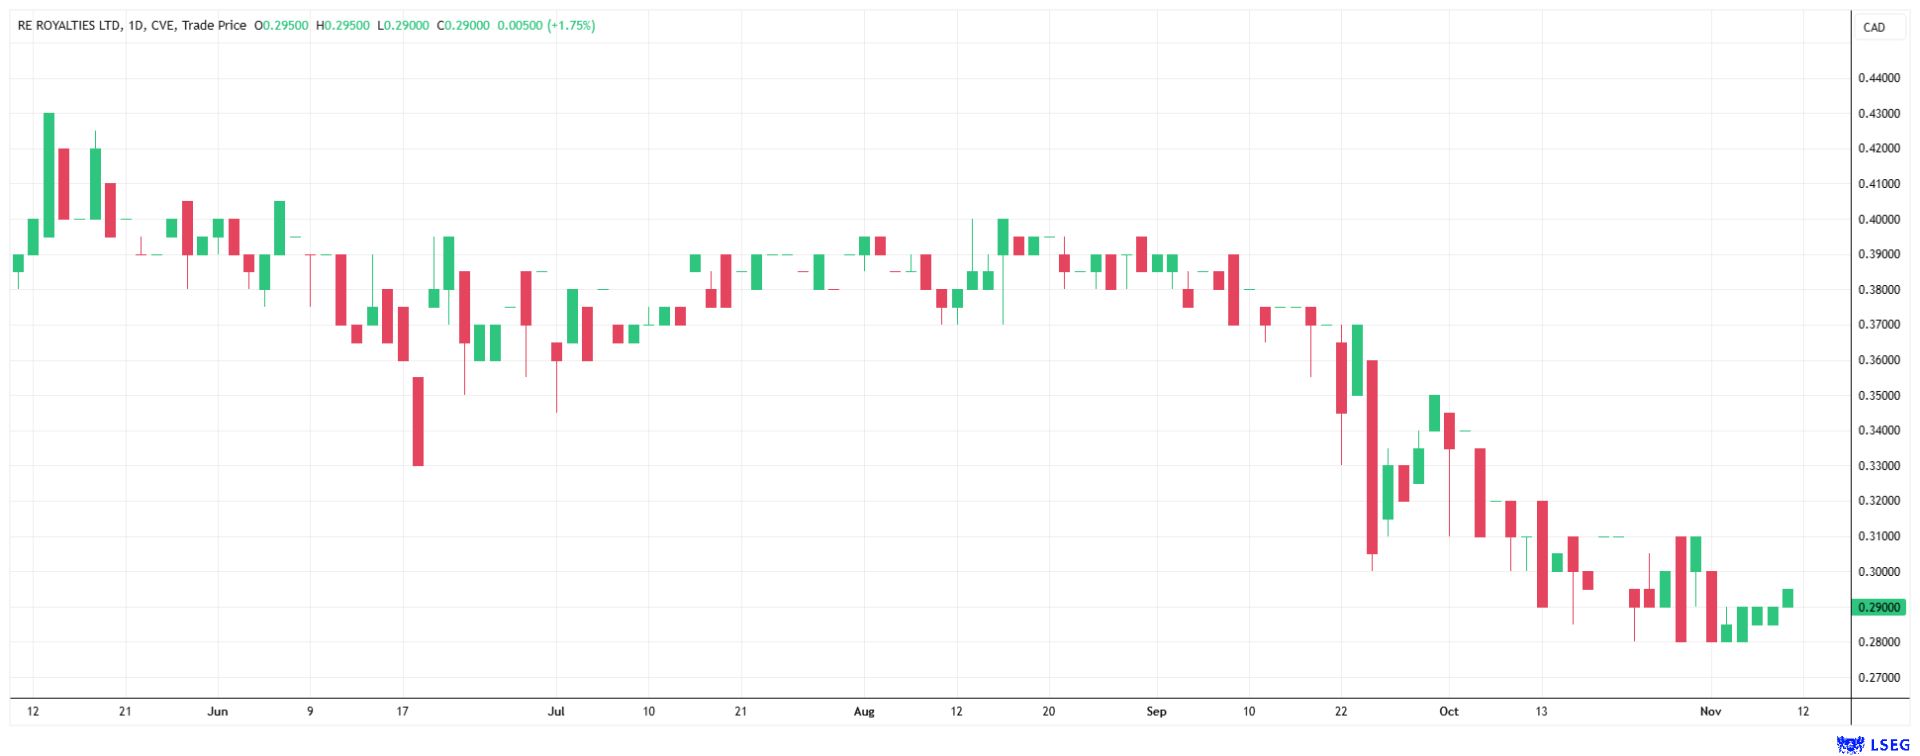
To serve its project pipeline, RE Royalties needs access to debt capital. In early November, the company launched a private placement of green bonds worth up to CAD 5 million. The five-year securities offer investors a fixed annual interest rate of 7.5%. The financing is secured by the company's existing participations and loans granted. The offering is accompanied by warrants that could provide the company with additional equity capital in future. RE Royalties is currently reviewing potential investments of around CAD 200 million. In March, the board launched a process to review strategic alternatives, advised by PwC Corporate Finance, ranging from partnerships and co-investments to a sale of the company.
Conclusion: Large and small financiers complement each other
The energy market is increasingly splitting into two camps. RWE shows that even large groups share billion-euro projects with financial partners, while NextEra is driving the expansion of battery storage in the US. RE Royalties, by contrast, occupies the niche of smaller projects, where traditional banking reaches its limits. Revenue participations offer smaller developers an alternative to selling equity stakes. At the same time, the model entails risks for RE Royalties: the company relies on continuous refinancing, and its reported net losses require close monitoring. RE Royalties' shares are currently a speculative investment due to the company's low market capitalisation and the pressure to expand. Nevertheless, the business model and dividend policy are certainly intriguing.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.