November 4th, 2026 | 05:43 CET
Apple disappoints with its outlook; Aixtron celebrates an order boom and Power Metallic Mines is poised for a rebound!
Prepared and published on behalf of Power Metallic Mines
Global equity markets face important directional decisions in late autumn 2026. Severe dislocations are occurring and have already occurred, most recently to an extreme degree at Intel and other chip stocks. While technology stocks such as Apple are struggling with unexpected margin pressure and expensive memory chips despite stellar record highs, semiconductor equipment manufacturer Aixtron is experiencing a breakthrough thanks to booming order books. Away from the major indices and stocks, the commodities sector is also worth a look. At Power Metallic Mines, a more pronounced consolidation may have laid the groundwork for a rebound to begin now. Strong drilling results and the upcoming PEA could pave the way for expectations of substantial share price gains. Read on to find out how to assess these three stocks in the current market environment.
time to read: 5 minutes | Author: Matthias Schomber
ISIN: Power Metallic Mines Inc | CA73929R1055 , APPLE INC. | US0378331005 , AIXTRON SE NA | DE000A0WMPJ6
Table of contents:
Author
Matthias Schomber
Raised in Giessen, Hesse, Matthias Schomber discovered his passion for the financial markets as early as the 1990s—at a time when stock trading was still largely the domain of true, die-hard traders. After completing his banking apprenticeship, he worked for a private bank there and witnessed the rise and fall of the Neuer Markt firsthand on the trading floor of the Frankfurt Stock Exchange, drawing lessons from the experience that continue to shape his thinking as a trader, author, and trading system developer to this day.
Tag cloud
Shares cloud
Apple: Record Revenue, but Margin Pressure and Costly Memory Chips
The Cupertino-based iPhone group is reporting its customary strong revenue for the period, but Wall Street remains palpably sceptical despite historic highs. The technology group with the bitten apple logo fell short of many market participants' lofty expectations with its outlook for the important Christmas quarter. Group revenue climbed 12% to USD 114.5 billion in the fourth quarter of the 2026 financial year, and earnings per share of USD 2.10 also exceeded consensus estimates. Nevertheless, the share price reacted in a muted fashion and is currently trading at just under EUR 290, as investors increasingly scrutinise future profitability rather than revenue records alone.
Operationally, the iPhone and the Mac division, in particular, drove substantial growth last quarter. Smartphone revenue rose by an impressive 17% to USD 57.6 billion, while Mac computers increased 24% to USD 10.8 billion. The robust core business once again demonstrates the company's enormous market and pricing power in an increasingly challenging global environment. The services segment grew more moderately by 9.8% to USD 31.6 billion, while the iPad and wearables division showed slight weakness. Revenue in the Greater China region also fell slightly short of analysts' high expectations at USD 17.5 billion.
However, the main reason for the weaker share price reaction following the release of the figures lies in the outlook for the coming months and rising component costs. Rising memory chip prices and ongoing investment in AI features for Siri are noticeably weighing on profitability. For the Christmas quarter, Apple expects a gross margin of just 45% to 46%, dampening short-term earnings expectations. With a P/E ratio of almost 50 and a dividend yield of 0.29%, the shares carry a demanding valuation. Apple could therefore also see weaker share prices in the coming days and weeks.
Aixtron: Order boom and analyst upgrades could fire up the turbo again
After a bumpy and volatile phase on the stock market, the semiconductor equipment specialist is making an impressive comeback. The latest share price momentum suggests that hopes of a sustained recovery in the global chip industry are finally gaining tangible support. Driven by sharply rising demand for advanced power electronics and optical components, the shares have regained their appeal among institutional and retail investors alike. Research firms such as Kepler Cheuvreux recently upgraded their rating on the shares from Neutral to Buy, providing fresh momentum for a further rise.
The operational turnaround is also clearly reflected in the financial figures for the latest quarter. In the third quarter of 2026, order intake exploded by 122% to EUR 274.9 million, while EBIT reached a solid EUR 56.7 million. These high order inflows put management in a good starting position for the coming quarters and also demonstrate the strong market position. Although the boom is leading to longer delivery times of up to 12 months, customers are backing their plans with "genuine advance orders". Momentum is growing rapidly, particularly in gallium nitride for efficient power supplies in AI data centres.
Investors are now eagerly awaiting the timely fulfilment of the fullest order books in the company's history. With a share price of around EUR 32.70 and a P/E ratio of 45, Aixtron is not exactly cheap, but already carries a demanding valuation, though it should be fairly valued if this growth momentum continues. The experts' average price target is approximately EUR 43, signalling upside potential of over 25%. Those who can generally handle the greater volatility in the technology sector could find a stock here that should benefit directly from long-term megatrends.
Power Metallic Mines: Strong drilling data and the ongoing PEA could lay the groundwork for the rebound
In the shadow of the major technology indices and away from Apple or Aixtron, the Canadian resources sector is offering some highly exciting, asymmetric entry opportunities. Following an earlier rise from CAD 1.00 to CAD 1.55, Power Metallic Mines shares have more than fully retraced this upward move in recent months. The share price even fell below CAD 1.00 for a time and is currently trading at a key support level at CAD 0.86. From a technical perspective, several indications suggest a stable bottom could form here, laying the foundation for a new upward trend.
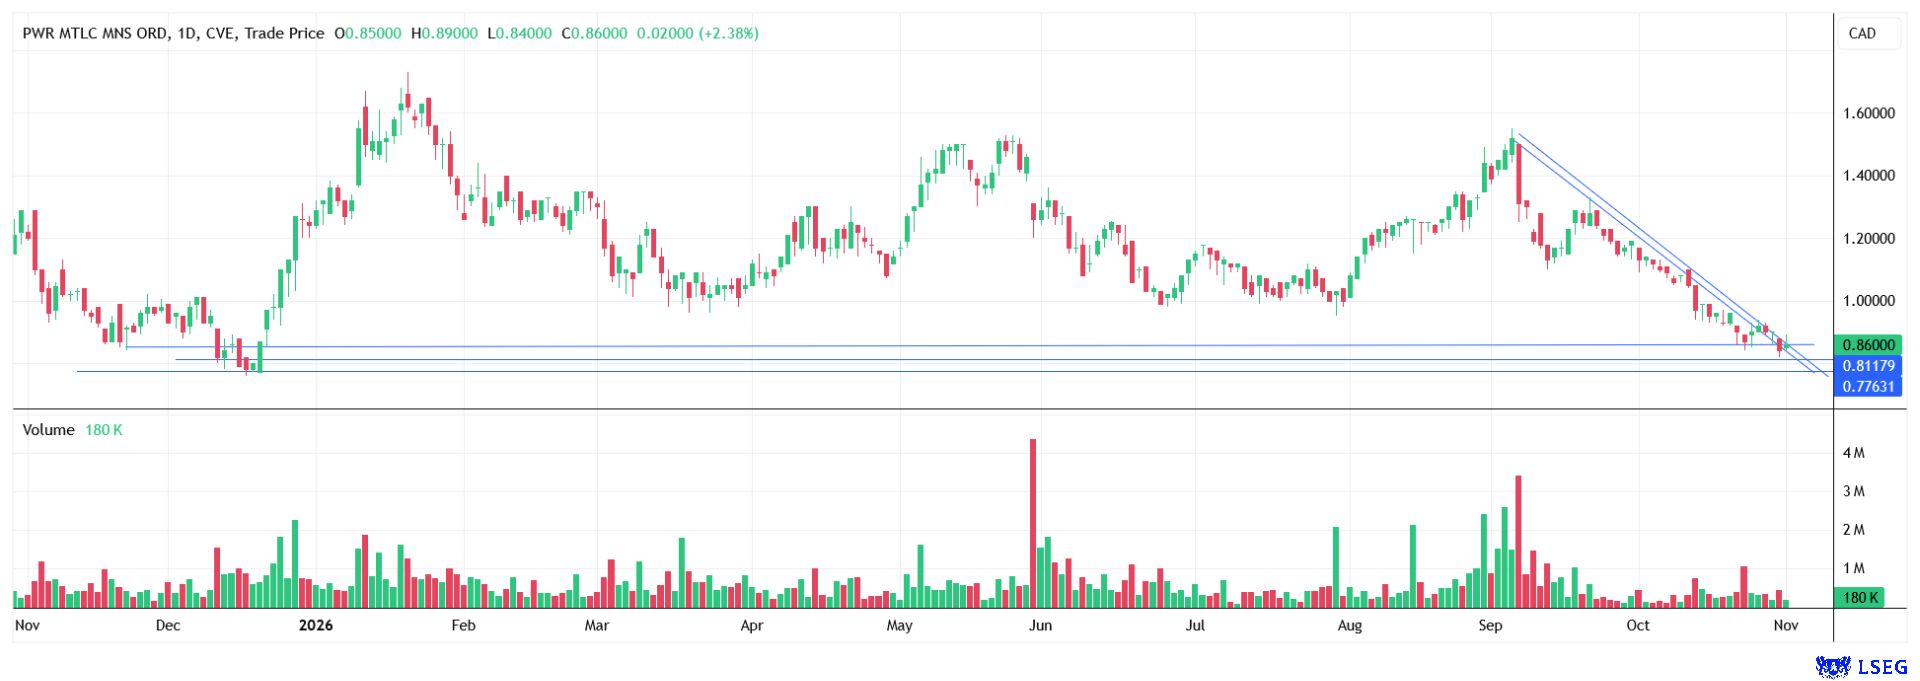
If the share price dips slightly again in the short term, strong horizontal support lies in the CAD 0.80 to CAD 0.83 range, and below that in the slightly lower territory between CAD 0.76 and CAD 0.79. From a technical perspective, a rise to CAD 0.95 alone would be sufficient to break above the fairly steep short-term downward trend (marked on the chart). In this scenario, the chart picture could change rapidly and drive the share price dynamically towards CAD 1.30 to CAD 1.40. In the longer term, experienced professional investors and other investors could also recognise GBC AG's ambitious price target of CAD 3.00. From the analysts' perspective, the shares therefore offer significant upside potential.
The latest company announcements from late summer and autumn 2026 in particular underline the positive development of the polymetallic Nisk project in Quebec.
On September 22, 2026, the company reported strong results from the deep development drill hole PML-26-125 in the Lion district, which intersected a very strong 5.70 m grading 14.00% CuEqRec at a vertical depth of just under 800 m and significantly extended the known frontal zones downwards.
Shortly after, on October 5, 2026, management announced the official launch of the Preliminary Economic Assessment (PEA) and appointed the renowned engineering firm BBA Inc. as lead consultant for the study, targeted for completion in the first half of 2027.
This combination of high-grade polymetals such as copper, platinum, palladium and nickel; a solid capital base following the CAD 28.2 million financing in June 2026; and prominent major investors such as Robert Friedland and Eric Sprott makes the stock a highly exciting exploration and development play.
Conclusion
Apple remains a profitable technology group but must contend with short-term margin pressure from expensive memory components. Aixtron impresses with a rapid boom in orders and intact growth drivers in the semiconductor segment. Following an intensive consolidation, Power Metallic Mines presents itself as a promising polymetallic stock that could impress with good drilling data, strong institutional backing and potential "catalysts" for 2027.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.