November 3rd, 2026 | 05:24 CET
Zefiro Methane: Old wells, new contracts and plenty of upside potential
Created and Published on Behalf of Zefiro Methane Corp.
Investors looking to benefit from the American energy boom usually focus on oil and gas producers or power plant builders. Yet opportunities can also be found in what previous generations of producers have left behind. Millions of disused oil and gas wells across the US need to be properly plugged. Some release methane, while others stand in the way of new construction projects. For Zefiro Methane, this represents a huge market. The latest company announcements show how the growing need for remediation is increasingly translating into firm contracts. Following its operational turnaround, Zefiro is now entering its next phase of growth. We take a closer look at this intriguing stock in our stock check.
time to read: 4 minutes | Author: Lars Winter
ISIN: Zefiro Methane Corp | CA98926D1069
Table of contents:
Author
Lars Winter
A native of North Hesse, he has over 25 years of experience in financial journalism and active portfolio management and is regarded as a proven expert on German small-cap stocks and special situations.
After studying law at the University of Göttingen with a focus on banking and capital markets law, he began his career in Frankfurt's financial scene at the turn of the millennium. As a stock market and business journalist, the passionate amateur golfer wrote for leading investment newsletters, financial newspapers, and business magazines, including PLATOW Börse, Capital Depesche, BÖRSE ONLINE, Capital, and the Financial Times Deutschland.
Tag cloud
Shares cloud
Potential share price tripler
Millions of orphaned oil and gas wells stretch across the US. Many leak harmful methane, while others prevent land from being used for new infrastructure projects. The environmental services provider Zefiro Methane measures emissions, plugs the wells and restores the land. Through its subsidiary, Plants & Goodwin, the company covers much of the value chain.
Government support is likely to continue for years. Of the USD 4.7 billion that the US Congress has allocated to the remediation of orphaned wells, around USD 4 billion is not due to be distributed until 2031. Zefiro's core states account for approximately USD 778 million of the formula-based funding allocated so far. According to the company, Zefiro has so far won around a quarter of the contracts funded by the infrastructure programme in its established regions.
A Fully Loaded Order Book
On October 19, Zefiro Methane reported a government order backlog of around USD 40 million. The projects run through June 2029. Around USD 4.9 million of this is due to be completed in the current quarter ending in December alone. This is a considerable amount for a company that generated USD 42.5 million in revenue in the past financial year. However, the contracts span several years. The volume must therefore not be mistaken for a short-term jump in revenue.
The largest individual item is a three-year contract worth USD 19.6 million from Ohio's environmental and natural resources authority. This involves the plugging of around 200 wells. In addition, there is a government-funded contract worth USD 11.5 million, with work beginning in November. For Zefiro, this means greater planning certainty. Staff and equipment can be deployed more effectively. Private contracts come on top, as the reported backlog covers only government projects.
Viking Provides First Evidence
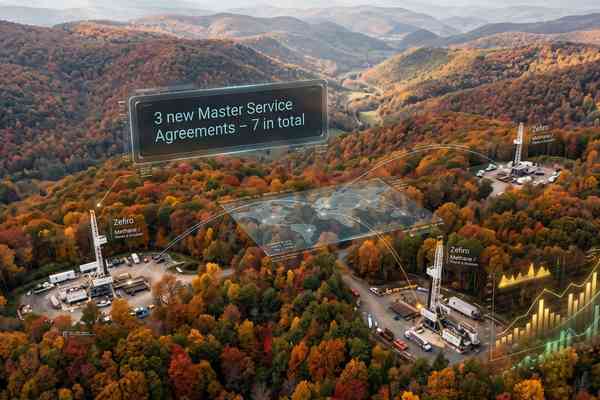
The October 27 news underlines that the private sector is also increasingly contributing to capacity utilisation. Since acquiring the Viking equipment in May, Zefiro Methane has concluded seven additional framework agreements with corporate clients. Five of these clients have already contributed revenue. Such framework agreements do not yet guarantee call-off volumes. However, they facilitate access to follow-up contracts. And the acquired capacity is already earning money: in August and September, a total of USD 1.54 million in revenue came from work attributed to the Viking acquisition. On an annualised basis, this equates to more than USD 9 million. This brings the additional annual capacity of around USD 10 million targeted by management within reach.
Data centres drive increased demand
Additional demand is emerging where new energy infrastructure and data centres are to be built. If abandoned wells are located on these sites, they must first be secured. In Pennsylvania, for example, Zefiro plugged nine gas wells on the site of a former coal-fired power station earmarked for a natural gas-powered data centre site. The link to the investment boom is tangible: without addressing such legacy liabilities, construction projects can be delayed.
The financial performance inspires confidence. In the 2025/26 financial year ended June 30, revenue rose by 31.1% to USD 42.5 million. Gross profit grew by 66% to USD 12.4 million, while the gross margin improved from 23% to 29.2%. At the same time, operating expenses fell by 10.2%. The adjusted EBITDA turned from a negative USD 4 million to a positive USD 3.8 million. Consistent profitability has not yet been achieved, however. The bottom line was a loss of USD 3.5 million. In the final quarter, the gross margin slumped to 18.6%, while adjusted EBITDA was negative at USD 0.6 million. Integrating the Viking fleet, additional staff and the start-up of the large Ohio project naturally cost money initially. However, the investments in increased capacity should pay off sustainably.
Analysts see scope for further substantial share price gains
The analysts at Augsburg-based financial services provider GBC Research see Zefiro Methane shares as a potential tripler. According to their study dated October 13, the experts expect revenue to rise to USD 57.9 million and EBITDA to reach around USD 10 million in the current 2026/27 financial year. Net profit is expected to reach USD 4.2 million. By 2028/29, operating profit is expected to rise to USD 15 million. Based on the current share price of around CAD 0.67, the analysts calculated a P/E ratio of 12 and an enterprise value-to-EBITDA ratio of 5.7 for 2026/27.
GBC Research's price target is USD 1.50 or CAD 2.15. This valuation offers, with share price upside of more than 220%, considerable further room for gains, but assumes that the expected jump in profit materialises. GBC forecasts a doubling of profit within two years.
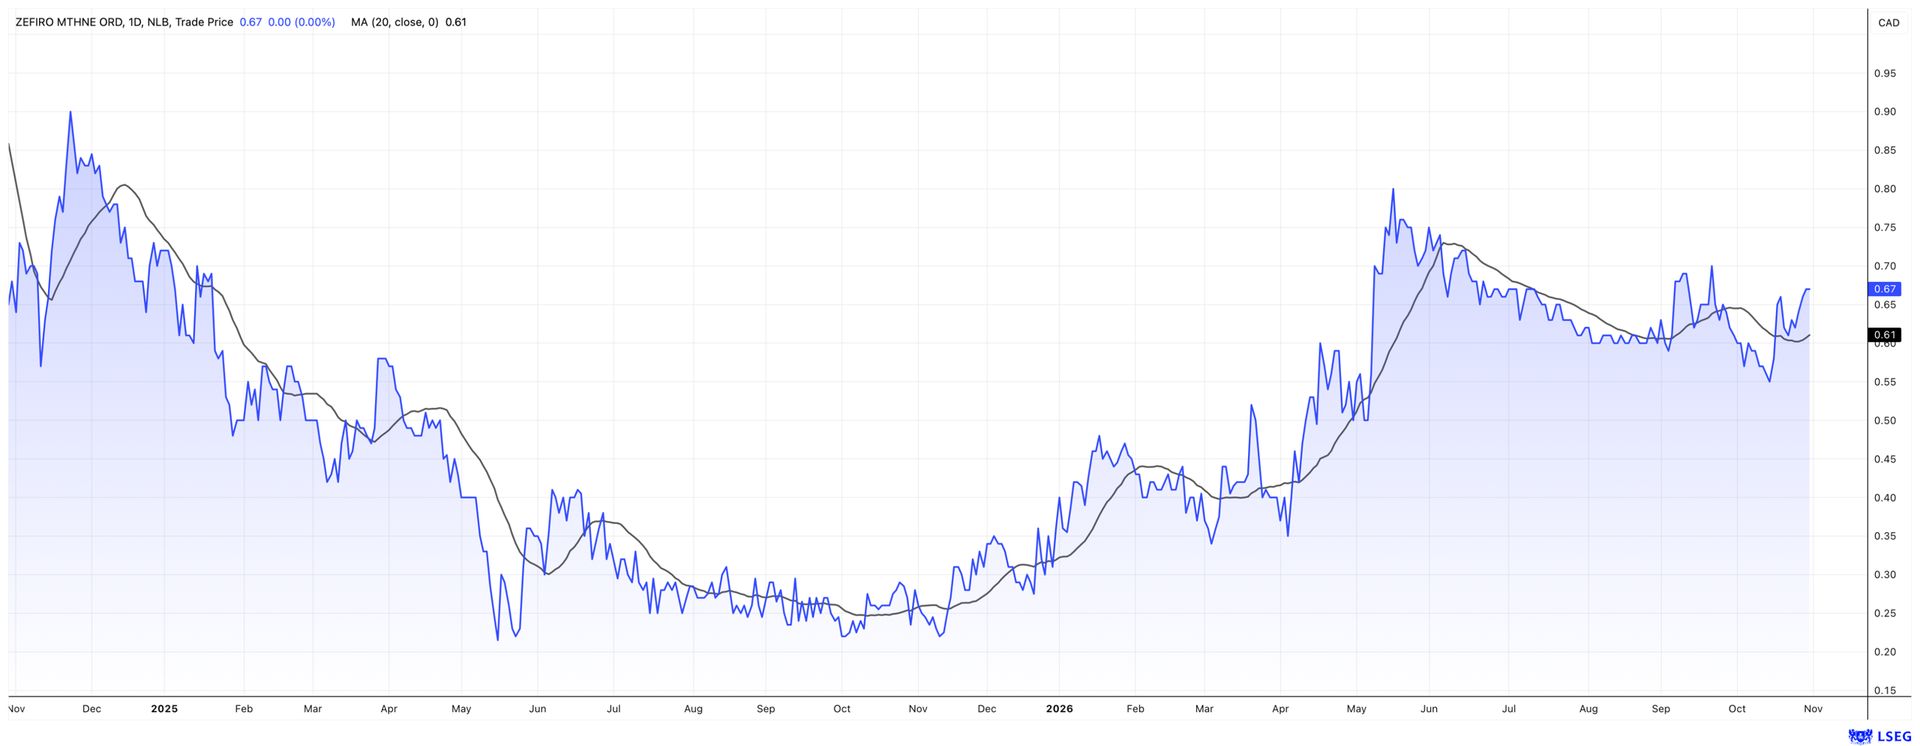
Zefiro has meanwhile also strengthened its financing capacity. On October 23, Zefiro raised CAD 5 million in gross proceeds through a private placement. Around 7.58 million units were issued at CAD 0.66 each, consisting of one share and half a warrant. The fresh funds are primarily intended to finance ongoing operations and provide a sufficient cash buffer.
Conclusion
Zefiro is increasingly providing tangible arguments for a revaluation. The government order backlog provides visibility, while the Viking equipment brings new clients and initial meaningful revenue. The emissions certificates business offers additional potential in the longer term. However, it remains crucial that improved capacity utilisation also translates into stable profits and cash inflows. For investors willing to take risks, the environmental specialist is an exciting turnaround play. The share remains promising given its low valuation and substantial upside potential. The risk-reward profile also continues to improve. Revenue and gross profit are rising, EBITDA is positive, debt is falling and the larger fleet provides the basis for the next stage of growth. The next reality check will come with the first-quarter figures in mid-November at the latest.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.