November 20th, 2026 | 05:55 CET
Two sides of the same coin: America's legacy liabilities are Zefiro's opportunity! Analysts are extremely bullish!
Created and published on behalf of Zefiro Methane Corp.
Over a period of 20 years, methane has around 80 times the global warming impact of the same mass of CO₂. Preventing methane emissions can therefore deliver results relatively quickly. This explains the political focus on leaks and the plugging of abandoned and orphaned wells. Under the Infrastructure Investment and Jobs Act (IIJA), the US government has earmarked around USD 4.7 billion to plug and remediate orphan wells. "Orphan" means that no responsible operator can be held accountable. One lesser-known beneficiary of this situation is Zefiro Methane. The company is an established hidden champion in the US and is steadily expanding its business both organically and through acquisitions. Having recently secured fresh capital, the company could soon be stepping up its operations significantly. Analysts see substantial share price upside.
time to read: 3 minutes | Author: Carsten Mainitz
ISIN: Zefiro Methane Corp | CA98926D1069
Table of contents:
Author
Carsten Mainitz
The native Rhineland-Palatinate has been a passionate market participant for more than 25 years. After studying business administration in Mannheim, he worked as a journalist, in equity sales and many years in equity research.
Tag cloud
Shares cloud
Still under the radar
Escaping methane harms the climate, while orphaned wells complicate land use. Zefiro Methane makes money by eliminating these problems. The company remediates orphaned oil and gas wells, measures methane emissions and intends to generate additional revenue from certified emission reductions in future.
Around USD 40 million in government contracts, growing demand from the private sector, partnerships and potential acquisitions underpin the business model's potential. With more than 2 million abandoned oil and gas wells in the US, a market is developing with an estimated value of USD 400 to 600 billion. So far, Zefiro has established a specialist presence in 15 US states with its integrated business model.
Operational foundation and partnerships
Plants & Goodwin provides the operational foundation, a company with more than 50 years of industry experience. Through this subsidiary, Zefiro covers several stages of the process: measurement and monitoring, maintenance and remediation, well plugging and land restoration. Its clients are primarily public-sector entities, with a growing number of private companies, particularly in infrastructure and AI data centres. The key bottlenecks are experienced crews, suitable equipment and reliable project execution.
The collaboration with the US-based Well Done Foundation opens up additional growth opportunities for Zefiro. The non-profit organisation, well regarded in the industry, identifies suitable projects and has a network across numerous US states, while Zefiro handles technical implementation through its subsidiary, Plants & Goodwin.
Contracts, acquisitions, credits
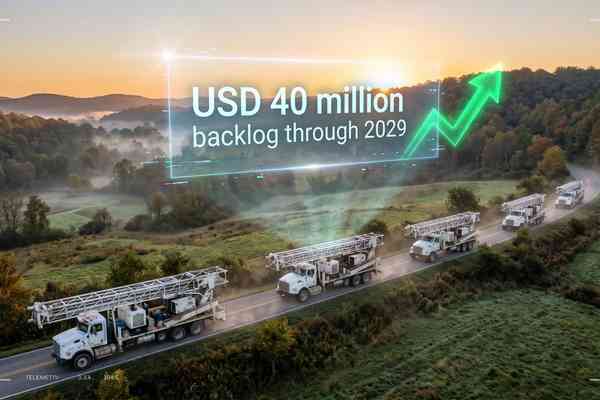
According to the company, the government order backlog amounts to around USD 40 million, with some work extending through June 2029. This includes a contract in Ohio originally valued at USD 19.6 million and an USD 11.5 million contract from the Great Lakes region announced in September. Around USD 3 million of the latter is to be completed between November 2026 and the end of June 2027, with the remainder following by June 2029.
The USD 4.3 million acquisition of the Viking Well Service fleet in May provided additional capacity. According to the company, five additional rigs are expected to provide approximately USD 10 million in annual revenue. The acquired fleet already generated around USD 1.5 million in August and September. Seven new framework agreements with corporate clients broaden access to the private market.
Figures and valuation
In the financial year to the end of June 2026, revenue rose by 31.1% to USD 42.5 million. The gross margin improved to 29.2%, while adjusted EBITDA reached USD 3.8 million. The net loss decreased correspondingly to USD 3.5 million. From the current financial year onwards, the acquired Viking equipment is expected to deliver higher utilisation and annual revenue of around USD 10 million.
Zefiro increased revenue by 30.7% quarter on quarter to USD 12.1 million in the first quarter of the current 2026/27 financial year (ended September 30). This was driven in particular by the gradual increase in utilisation of the acquired Viking rig fleet. The gross margin improved to 20.4%, while adjusted EBITDA returned to positive territory at USD 0.1 million. The net loss narrowed to USD 2.4 million.
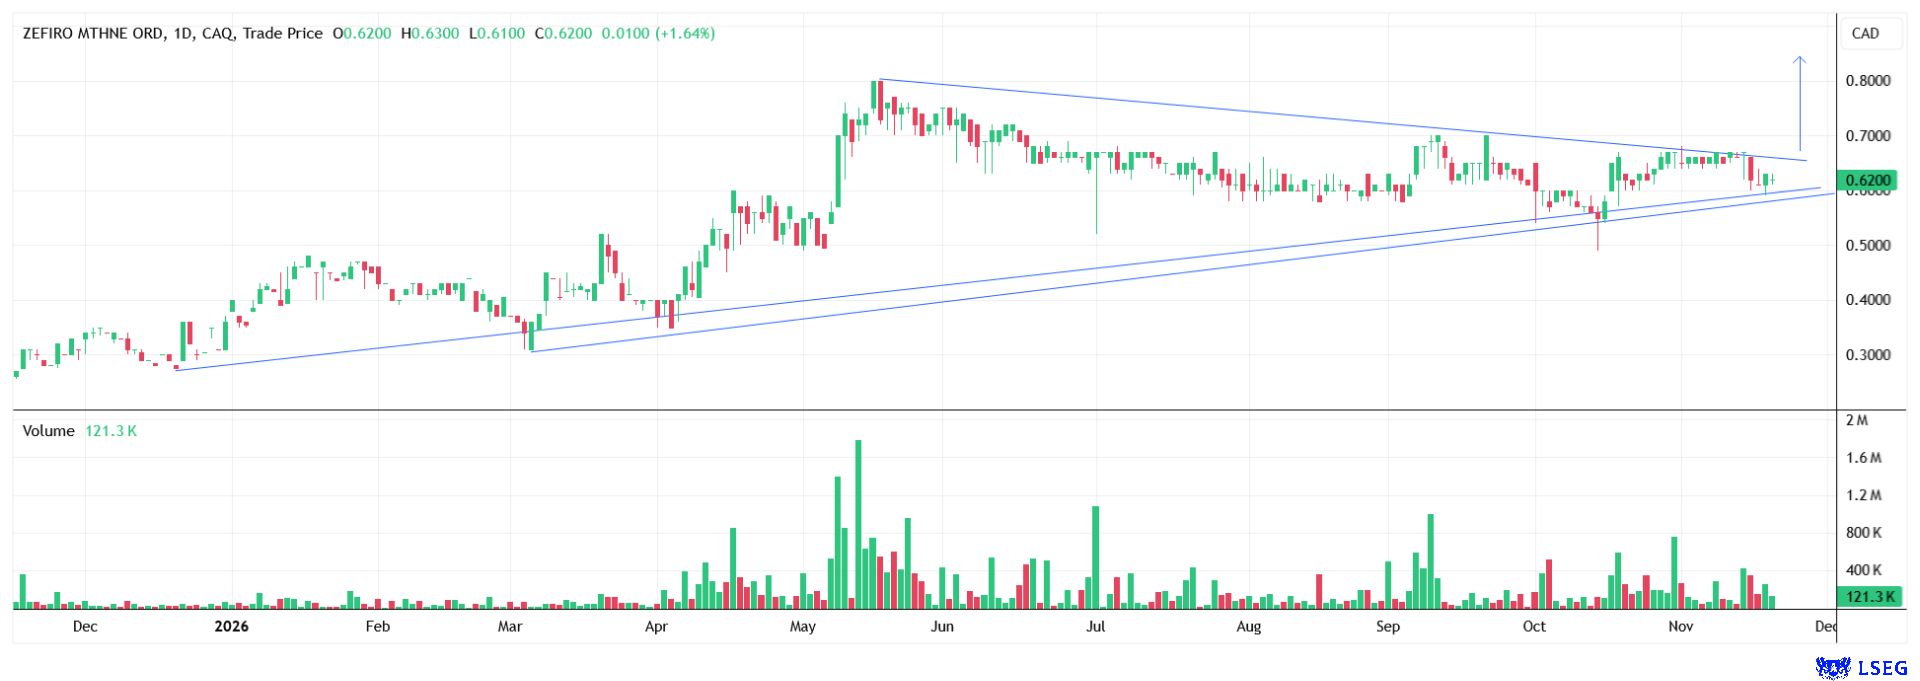
The company recently received CAD 5 million in gross proceeds from a capital increase. The funds are intended primarily to strengthen working capital and enable further acquisitions.
Research firm GBC projects dynamic growth and expects revenue of around USD 57.92 million, EBITDA of USD 10.02 million, and net profit of USD 4.21 million for 2026/27. The experts' price target is USD 1.47 or EUR 1.34, with a target horizon of the end of 2027. By comparison, the shares are currently trading at around EUR 0.41. This implies enormous upside potential.
Conclusion
Zefiro Methane is already making money today from a problem that remains under the radar of many investors. The US methane specialist plugs orphaned oil and gas wells from which methane continues to escape. This is appealing for the investment story, as a successfully remediated well can potentially contribute to revenue twice. In addition to the revenue from the remediation contract, further income from avoided emissions in the form of carbon credits could significantly boost margins in future. The fresh capital gives Zefiro scope to handle more projects simultaneously and expand through acquisitions. GBC's analysts believe the company is capable of strong growth in the coming years. Their price target is USD 1.47, more than 3 times higher than the current share price.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.