May 21st, 2026 | 07:10 CEST
Undervalued – Analysts Turn Their Attention to Life Sciences: Bayer, Vidac Pharma, Novo Nordisk, and Pfizer in Focus
DZ Bank's aggressive price target adjustment for Bayer demonstrates that analysts have recently begun to view the life sciences sector more favourably. The pharmaceutical and agrochemical group's strong start to the year has led to significantly improved prospects, and legal risks are now also viewed as more moderate. Finally, some good news for long-suffering investors in a geopolitically volatile environment. After all, there have not been any major upgrades in the sector for quite some time. When it comes to Novo Nordisk, however, experts remain divided on whether the earnings trend will turn positive again. Cutthroat competition in the weight-loss drug market is intense, putting pressure on margins. Buoyed by industry sentiment, Pfizer also saw its stock rise again. Time for a new tour of the sector. Where are the triggers?
time to read: 5 minutes | Author: André Will-Laudien
ISIN: VIDAC PHARMA HOLDING PLC | GB00BM9XQ619 , BAYER AG NA O.N. | DE000BAY0017 , NOVO NORDISK A/S | DK0062498333 , PFIZER INC. DL-_05 | US7170811035
Table of contents:
Author
André Will-Laudien
Born in Munich, he first studied economics and graduated in business administration at the Ludwig-Maximilians-University in 1995. As he was involved with the stock market at a very early stage, he now has more than 30 years of experience in the capital markets.
Tag cloud
Shares cloud
Bayer: Analysts See Light at the End of the Tunnel
Sometimes things happen in quick succession. That is exactly what happened yesterday, when two research firms raised their ratings, sending Bayer's stock price soaring by over 4% at its peak. Barclays had already taken the lead in the morning with a statement on the surprisingly strong Q1 performance and an "Overweight" rating, raising its price target from EUR 48 to EUR 50; by noon, DZ Bank had added a "Buy" recommendation with a target of EUR 51 instead of EUR 44. Operationally, the Leverkusen-based company impressed with surprisingly robust quarterly figures; the agricultural division, in particular, benefited from strong seed sales in North America, among other factors, leading to a noticeable increase in revenue and operating profit. Nevertheless, the glyphosate issue continues to cast a shadow over the group, as the ongoing Roundup lawsuits and multi-billion-dollar settlement payments are weighing equally on cash flow, the balance sheet, and investor confidence. The pharmaceutical sector also presents a mixed picture. New growth drivers like Nubeqa and Kerendia are growing rapidly, while former blockbusters are under intense pressure from patent expirations and generic competition. Management nevertheless maintained its full-year forecast, so the stock remains a turnaround candidate for patient investors.
Pfizer – Started the Year Well Above Expectations
At Pfizer, it is becoming increasingly clear that the company is weathering the sharp downturn following the end of the COVID-19 boom better than many investors had anticipated just a few quarters ago. Analysts had not yet anticipated a noticeable operational recovery and a 5% increase in revenue to USD 14.5 billion. Growth was driven primarily by established drugs such as Eliquis and Padcev, as well as by new products, some of which saw revenue growth of more than 20%. Despite this momentum, profit fell by 9% to just under USD 2.7 billion, as rising R&D expenses and higher administrative costs weighed on earnings. Strategically, Pfizer continues to face structural upheaval, with approximately USD 17 billion in annual revenue at risk by 2030 due to expiring patents and increasing competition. At the same time, management is banking on a growing pipeline in oncology and obesity to compensate in the long term for the billions lost due to COVID-19 and to establish a new growth base. Sentiment is improving on the LSEG Refinitiv platform, even though the consensus price target remains modest at USD 29.05, just 13% above the current price. Long-term investors, however, are enjoying the nearly 7% dividend.
Join us today for the 19th International Investment Forum and listen in live to 20 CEOs discuss their business models and strategic outlooks. Featured companies include K+S, RENK, and Almonty Industries. Click here to register for free
Vidac Pharma Positions Itself in the Race for the Next Oncology Revolution
With its unique scientific approach, Vidac Pharma is deliberately moving away from traditional oncology pathways and focusing on the point at which many tumour diseases originate: disrupted cellular metabolism. At the center of its research is the enzyme hexokinase-2 (HK2), which tethers to the mitochondria to fuel cancer cells like a permanent, high-performance engine while simultaneously blocking natural self-destruction mechanisms. Instead of solely attacking tumours aggressively, the company is pursuing the idea of reversing the metabolic dysfunction of cancer cells and, in a sense, forcing them back into a controllable state. This therapeutic strategy directly leverages the Warburg effect—a metabolic phenomenon documented for decades that has once again emerged as a pivotal battleground in modern cancer research.
It is noteworthy that Vidac is no longer merely operating on a theoretical level but has already demonstrated clinical progress. An advanced study for the treatment of actinic keratoses is currently underway in Germany, while positive results have already been achieved in earlier study phases for rare lymphoma diseases. The company garnered additional attention through an individual treatment case involving a child with a recurrent brain tumour. In this case, the active ingredient apparently influenced the tumour's metabolic activity. It provided evidence that the substance itself can cross the blood-brain barrier—an aspect considered particularly challenging in neuro-oncology. While individual cases do not replace broader clinical evidence, they often provide precisely the biological signals that investors and potential pharmaceutical partners seek at an early stage.
At the same time, Vidac is expanding the scope of its platform technology beyond traditional cancer medicine. Preclinical programs are now also addressing diseases such as psoriasis, in which metabolic dysregulation also plays a central role. Step by step, this paints a picture of a company whose platform technology need not be limited to a single indication but could potentially address multiple therapeutic markets. Also strategically interesting is the recently issued USPTO patent protection, which safeguards key components of the drug class through 2045, significantly strengthening the company's negotiating leverage with potential licensing partners.
Especially in an industry where major pharmaceutical companies' billion-dollar revenue drivers are set to lose patent protection in the coming years, pressure is mounting on established firms to integrate innovative platforms at an early stage.
The fact that the company's executives and founders occasionally sell their own shares has nothing to do with exiting the company but serves to self-finance research. This is because, in this case, there is no dilution from capital increases, and the profits remain with the shareholders on a pro rata basis. For long-term investors, the stock's current consolidation near its lower trend boundary may offer an attractive entry point. The probability is high that the next earnings release will again deliver a 50% gain. Buy up!
Novo Nordisk – Not Out of the Woods Yet
Novo Nordisk was sold off again at the 200-day line after a 25% price increase since the end of March. Barclays remains cautious on Novo Nordisk and confirms its "Equal Weight" rating with a price target of DKK 300. After a strong start, demand for the initial dose of Wegovy has stabilized at an elevated level. There are no signs of a slowdown due to the market entry of Lilly's competing drug in the latest prescription data, according to analyst James Gordon in a recent assessment. Out of 33 analyses on the LSEG Refinitiv platform, only 9 experts issue a "Buy" recommendation. At least that already offers 12% upside potential. The stock price will likely gain momentum only after overcoming the final resistance levels in the range of DKK 295 to 315. After all, the dividend of 11 kroner yields more than 3.8%. Long-term investors can thus enjoy the ride even while waiting. Dynamic investors are waiting for more momentum.
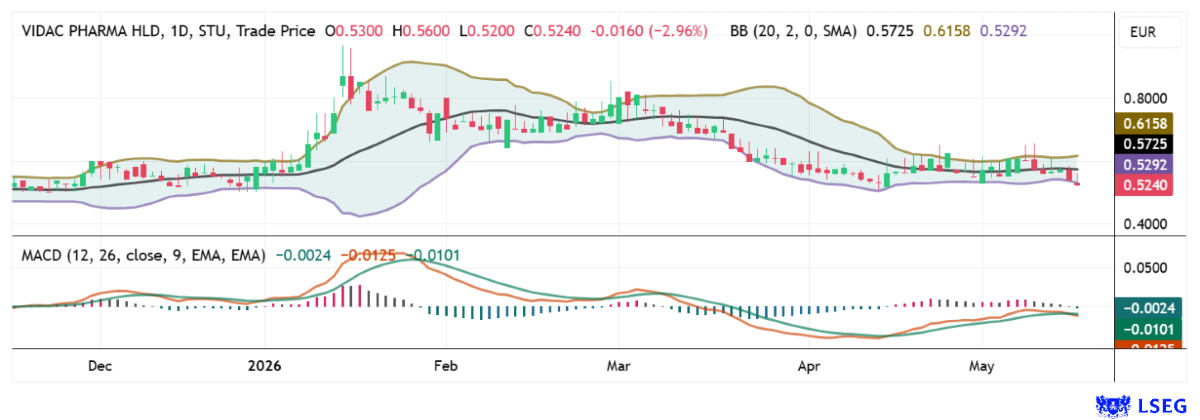
Volatility remains the dominant theme, but that is precisely where the opportunities lie. Bayer is sending the first constructive signals, while at Novo Nordisk, even professionals are still debating whether the next upward move is already in the starting blocks. Pfizer, on the other hand, has surprised positively with strong quarterly figures. And at Vidac Pharma, developments are intensifying behind the scenes—much suggests that the next news could give the share price fresh momentum.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.