November 18th, 2026 | 05:40 CET
Treasures from the depths, a slump in the stock market: Lynas, Almonty and Cameco tempt with low share prices
Without rare earths, no electric motors; without tungsten, no defence industry; without uranium, no nuclear power. The West needs these raw materials more urgently than ever and depends on a handful of suppliers that mine in politically stable countries. Yet shares in Lynas Rare Earths, Almonty Industries and Cameco are falling as if there were no shortage – down by one-third to two-thirds from their highs for the year. We have taken a close look at the three producers following their latest quarterly results. One of the shares has reached bargain levels.
time to read: 8 minutes | Author: Jens Castner
ISIN: Almonty Industries Inc | CA0203987072 , LYNAS CORP. LTD | AU000000LYC6 , CAMECO CORP. | CA13321L1085
Table of contents:
Author
Jens Castner
The Nuremberg native brings over three decades of capital markets experience, backed by a career shaped by deep market insight and a genuine passion for investing. His journey began in 1994 through an investment club among colleagues – a formative experience that sparked a lifelong dedication to identifying compelling investment opportunities.
Following senior editorial roles at Nürnberger Nachrichten, €uro am Sonntag, and €uro, he went on to serve as Editor-in-Chief of the renowned investor magazine Börse Online from 2014, where he played a key role in shaping high-quality financial journalism for a broad investor audience.
Tag cloud
Shares cloud
Lynas Rare Earths: Record prices versus maintenance shutdowns
A year ago, rare earth stocks were among investor favourites. Since then, disillusionment has set in. A broadly diversified VanEck ETF tracking rare earths and strategic metals has almost halved in value since March. Lynas Rare Earths, the largest producer outside China, has lost more than 40% of its value since April. Back then, the shares cost over AUD 21; today they stand at just over AUD 12. Yet the first financial quarter, which ended on September 30, did not look bad at all.
Revenue rose 55% to AUD 310.1 million, while the average selling price climbed 88% to a record AUD 102.10 per kilogram. This is made possible by contracts with price floors, which now cover more than half of production. Revenue nevertheless fell short of analyst expectations, as the volume sold shrank by 17.7%. Production rose 6.5% year on year to 4,254 tonnes, so some raw materials went into inventory. Headwinds are also coming from Beijing. China has extended the suspension of certain export controls until January 10, 2027, easing concerns about shortages. Maintenance shutdowns are also weighing on investor sentiment this quarter: a plant in Malaysia is idle for a month, while processing in Kalgoorlie, Australia, is suspended for two weeks. David Tuckwell, chief investment officer at ETF Shares, sums up the new situation. With the pricing problem largely resolved, earnings now depend more heavily on whether Lynas can overcome disruptions and maintain stable production.
In addition, there has been no permanent successor since long-serving CEO Amanda Lacaze's departure in June. The board aims to announce a permanent appointment ahead of the annual general meeting on November 25. Lynas is paying for its latest acquisition of Meteoric Resources entirely in its own shares, thereby conserving cash. Even after the share price slump, the shares are not particularly cheap: the price-to-earnings (P/E) ratio based on 2027 earnings estimates is 25.5. At least analysts put the average fair value at over AUD 18, representing upside potential of around 50%.
Almonty Industries: No respite for tungsten
For Lewis Black, the respite granted by Beijing is a textbook example. The CEO of Almonty Industries points out that China repeatedly announces export bans on rare earths and graphite and then withdraws them. With tungsten, Almonty's main product, this never happens. Rare earths, he adds, are not nearly as rare as the name suggests. Deposits exist on every continent. Tungsten, by contrast, is scarce everywhere. According to the US Geological Survey, China controls around 80% of the global market. "Tungsten is too important for games", Black writes in his latest letter to shareholders.
The metal only melts at 3,422 °C and is almost as dense as gold. It is virtually irreplaceable in defence, aviation, toolmaking and medical technology. Beijing does not ban exports, but sets export-licence barriers so high that hardly anyone can overcome them. Black calls this a "ban without a ban". Only tungsten that does not require Chinese approval can be relied upon, he says. From January 1, 2027, the US will closely scrutinise where tungsten ore is mined for defence contracts. According to Black, only a few producers can demonstrate that significant quantities originate from allied countries – Almonty's Sangdong mine in South Korea, commissioned in September, is one of them. It has the potential to become the most important tungsten production site in the Western world. The first concentrate flowed in September, and the first container has now left the port of Busan. Round-the-clock operations began on November 1 but were briefly interrupted after just 10 hours. "This is what commissioning looks like," Black comments. They are working through one fault after another.
Almonty has recently had an even tougher time on the stock market than Lynas. Since April, its shares on the Nasdaq have fallen from USD 24.40 to USD 8.15, a decline of around two-thirds, even though the third-quarter figures were certainly impressive. Revenue rose 382% to CAD 41.9 million, while earnings per share increased from CAD 0.13 to CAD 0.17. The strong growth is mainly attributable to the Panasqueira mine in Portugal, which has been producing for decades. Although Sangdong is already producing, sales are not expected to contribute to revenue until the fourth quarter. The main reason for the explosive increase in revenue was the price of ammonium paratungstate (APT), the most important tungsten intermediate product. In Europe, it stood at USD 2,800 per metric tonne unit (MTU, 10 kg of tungsten oxide), compared with USD 615 a year earlier. The price has since eased somewhat. In early November, it stood at around USD 2,650 per MTU, slightly below third-quarter levels. However, this does not explain the drastic decline in the share price. Almonty could also manage comfortably with a price of USD 1,000 per MTU.
New listing plans and full order books
Management is pushing ahead vigorously with both operations and measures to support the share price. As the company had raised more money through a convertible senior notes offering than it actually needed, it is buying back up to USD 300 million of its own shares. More than 3.6 million shares have already been cancelled. Cash currently stands at CAD 1.15 billion. Yesterday, Almonty also announced plans to make its shares tradable in Seoul. "We see a listing on the Korean stock exchange as a natural complement to our Nasdaq listing", says Black. This should allow Korean investors to share in Sangdong's success, and a lead bank is to be named soon. At the same time, Almonty is strengthening its board of directors. Joining the board is US diplomat Eugene Bae, who was stationed in Seoul, Beijing and New Delhi for 16 years and most recently oversaw technology policy at the US State Department. Also new is Jim Rudyk, an experienced chief financial officer of listed companies. Following the departure of David Hanick and Andrew Frazer at the end of the year, five of the seven members are independent.
Operationally, the signs clearly point to expansion. More than 90% of production from the first expansion phase of the Sangdong project has already been sold to Austria's Plansee Group under long-term contracts. The second phase is intended to almost double capacity to up to 1.2 million tonnes of ore per year in 2027. There are further projects as well. At Los Santos in Spain, tungsten is to be recovered from old waste heaps, and a European customer has already firmly secured at least 1,720 tonnes of tungsten oxide. In Rwanda, a joint venture with the government is already buying more than 100 tonnes of ore per month. In the long term, the Gentung mine in Montana will be added, where tungsten is to be mined in the US for the first time in 30 years. Almonty only recently moved its headquarters from Canada to Dillon, Montana, to be closer to the mine and potential customers.
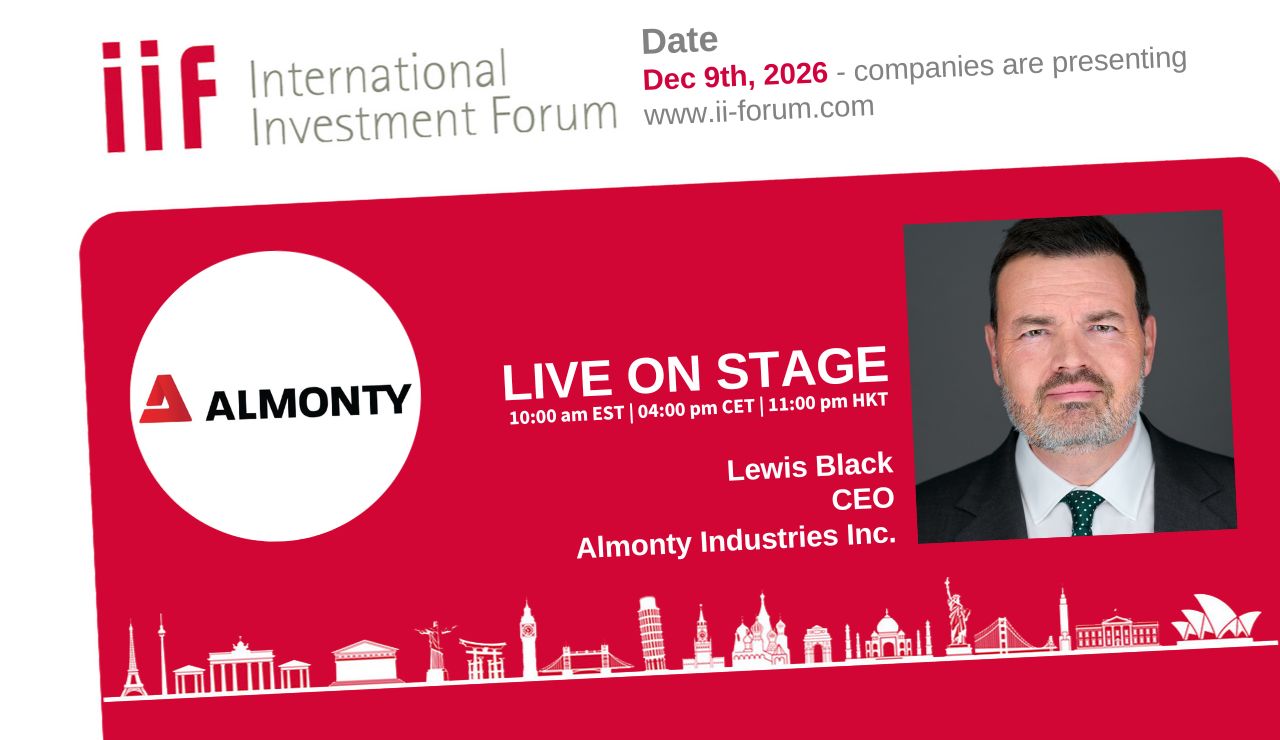
With a 2027 P/E ratio of 6.8, Almonty is valued significantly more cheaply than Lynas. The average analyst price target is around USD 23.30. That would represent almost a tripling of the current share price. Of interest to investors: On Wednesday, December 9, CEO Lewis Black will present his strategy at 4 pm CET at the International Investment Forum (IIF), one of the few specialist conferences also open to retail investors. Register via this link:
https://us06web.zoom.us/webinar/register/WN_e8tHYT16Tzy7t9vDH3fLkw#/registration
Cameco: Old contracts acting as a brake
Long-term supply contracts protect Almonty. At Cameco, they currently act more like a brake. The Canadian group mines some of the world's richest uranium deposits in the Athabasca Basin in Saskatchewan. It has contractually committed to supplying an average of more than 28 million pounds per year over the next 5 years. The uranium price briefly shot up from USD 90 to USD 106 per pound in January, then fell to as low as USD 64 and is now back at around USD 90. However, Cameco achieved only USD 65.78 per pound in the third quarter because older contracts pass on rising prices only with a delay. The share price has almost halved from its record high of CAD 182.72 in January to CAD 94.00.
Revenue rose by just 1% to CAD 619.1 million in the third quarter. On an adjusted basis, a loss of CAD 2 million remained, compared with a profit of CAD 32 million in the previous year. Extended maintenance at the Key Lake processing plant reduced production by 20% to 3.5 million pounds. For 2026, management now expects only 19.5 to 20.5 million pounds. To meet supply commitments, Cameco had to purchase 1.8 million pounds on the market. "We continue to be guided by our disciplined strategy", says CEO Tim Gitzel. He stresses that the recent share price fluctuations in nuclear stocks should not be confused with weaker fundamentals. Political support is providing a tailwind: Canada aims to double its uranium exports by 2035. In addition, a non-binding agreement between the US and South Korea provides for the financing of up to eight reactors, including six from Westinghouse. Cameco holds a stake in this reactor builder, whose earnings contribution rose 15% to CAD 143 million in the past quarter. With a P/E ratio of over 40 for 2027, Cameco nevertheless remains the most expensive stock in the comparison. Barclays recently lowered its price target, but on average analysts still see upside to CAD 167.20 – more than 75% above the current level.
Conclusion: A bargain among the trio
For all three companies, the current share price weakness is not due to demand. Lynas is suffering from maintenance shutdowns, a lack of leadership and China's pause for breath. Cameco cannot yet take full advantage of high uranium prices because of old contracts. Almonty is grappling with the typical teething problems of a new mine. The big difference lies in valuation. Lynas and Cameco are still trading at earnings multiples more commonly associated with the "Magnificent Seven", the seven largest US technology groups. Almonty, by contrast, has already fallen so sharply that a P/E ratio of 6.8 prices in many start-up risks. Moreover, analysts see by far the greatest share price upside here. With the ramp-up at Sangdong, today's share price is likely to prove a bargain in retrospect.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.