April 23rd, 2026 | 07:10 CEST
Oil Profits Are Flowing—But Methane from Abandoned Wells Is Becoming a Cash Machine: Shell, Zefiro Methane, and Occidental Petroleum
When fighting flared up in the Middle East, oil prices surged sharply. The industry is enjoying windfall profits. But behind the boom lies a creeping risk: millions of abandoned wells leaking methane unchecked—a gas that warms the planet far more intensely than CO₂. While oil majors benefit from high prices, a massive opportunity is emerging for service providers that specialize in dealing with these orphan wells. Three players with different strategies are aiming to capitalize on the current environment: Shell, Zefiro Methane, and Occidental Petroleum.
time to read: 5 minutes | Author: Armin Schulz
ISIN: ZEFIRO METHANE CORP | CA98926D1069 | NEO: ZEFI
Table of contents:
Author
Armin Schulz
Born in Mönchengladbach, he studied business administration in the Netherlands. In the course of his studies he came into contact with the stock exchange for the first time. He has more than 25 years of experience in stock market business.
Tag cloud
Shares cloud
Shell – Between an Oil Price Rally and a Billion-Dollar Risk
The extreme fluctuations in commodity prices in the first quarter of 2026 are leaving deep marks on Shell's balance sheet. Management warns of a negative working capital impact of USD 10–15 billion, a direct consequence of skyrocketing inventory values. In addition, long-term ship leases are inflating reported net debt to as much as USD 4 billion, even though no cash is flowing out. Operationally, lower volumes from Qatar and the slow ramp-up of the Canadian LNG project are dampening gas production to around 890,000 barrels of oil equivalent per day. On the positive side, oil trading and refining margins, which have risen to USD 17 per barrel, stand out.
Dividend investors remain the focus, however. At the end of March, the quarterly dividend of USD 0.372 per share was paid out, an increase of 4%. The ongoing USD 3.5 billion share buyback program runs through May across multiple trading venues. This marks the 17th consecutive quarter with at least USD 3 billion in purchases. Despite the risks, analysts are largely confident. Goldman Sachs raised its price target to EUR 45, while JPMorgan maintains an "Overweight" rating. Only Morgan Stanley is taking a more cautious stance, downgrading to "Equalweight", citing limited upside potential compared to competitors.
Shell is pushing ahead with its pivot to LNG. In Venezuela, the final investment decision for the Dragon gas field is approaching, and initial production from the cross-border Loran-Manatee field is expected in mid-2027. At the same time, the sale of approximately 600 gas stations in South Africa to Adnoc for USD 1 billion is imminent. However, new headwinds are emerging: Climate activists in the Netherlands have filed a lawsuit seeking to prohibit Shell from developing new oil and gas projects. A trial date has not yet been set. The quarterly results on May 7 and the annual general meeting on May 19 are thus coming into focus. The stock is currently trading at EUR 37.85.
Zefiro Methane – Scaling Its Business
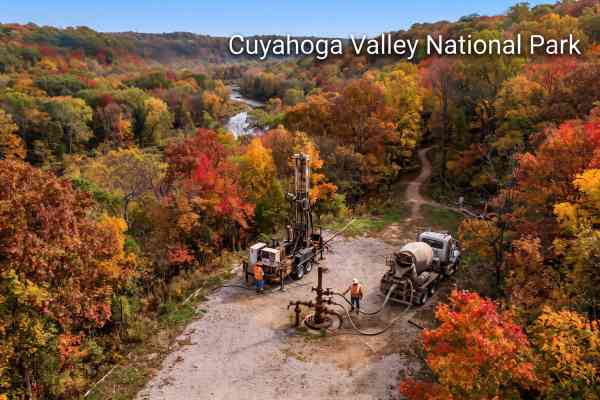
While major oil producers are primarily focused on new production, Zefiro Methane has specialized in the opposite: permanently plugging old (orphaned) wells. The past winter quarter from January to March, typically a quiet period, brought the subsidiary Plants & Goodwin a solid USD 11 million in revenue, an increase of over 50%. One reason was that the first contract in Louisiana was completed three weeks earlier than planned. At the same time, the team had already completed over a third of the USD 4.5 million Wood 12F project in Ohio. And the spring schedule is also full. A USD 19.6 million contract with the state of Ohio begins in June. Added to this are new orders for wastewater disposal drilling as well as the expansion of methane monitoring into Pennsylvania.
Political support for the remediation of abandoned wells is remarkably stable. Both Democrats and Republicans are promoting the business—the former for environmental reasons, the latter as an economic stimulus. The USD 4.7 billion allocated is just a taste of what is to come. The actual costs are estimated at USD 400 to USD 600 billion for 2 to 4 million abandoned wells. Zefiro has carved out a niche in which hardly anyone can compete. The company offers its own training programs for skilled workers, an integrated fleet ranging from drilling rigs to excavators, and a success rate in bidding that recently rose to over 30%.
Financially, the company is in a better position than it was a year ago. In the first two quarters of fiscal year 2026, the company generated an adjusted EBITDA of USD 3.8 million and a small net profit. At the same time, high-interest debt was reduced by nearly USD 2.8 million. Gross margins are expected to range between 30-35% in the future. In addition to its core business, the company sells carbon credits - CO₂ certificates. Most recently, over 92,000 metric tons of CO₂ equivalents were delivered to four customers. This is easier to scale than drilling operations but remains, for now, a secondary revenue stream with good margins. The stock is currently trading at CAD 0.37, giving it a market capitalization of approximately CAD 51 million. Given the market and the increasingly strong business performance, this appears to be a bargain.
Occidental Petroleum – The Streamlined Giant Gains Momentum
After more than four decades at Occidental, CEO Vicki Hollub is preparing to step down. COO Richard Jackson, who was promoted only in the fall of 2025, is considered the designated successor. A smooth transition is planned; Hollub may remain on the board of directors. The news was well-received at the end of March, and investors remained calm. A leadership change is always a sensitive moment, but Occidental has a tradition of strong leadership. The real question is whether Jackson will consistently drive the ongoing transformation forward—less growth at any cost, but more cash flow and capital discipline? Berkshire Hathaway, as a major shareholder, will be watching closely.
The numbers speak for themselves. Since the sale of the chemical division OxyChem to Berkshire Hathaway, USD 6.5 billion has been used to reduce debt. The remaining debt fell to around USD 15 billion, the lowest level in ten years. At the same time, management has cut operating costs by USD 2 billion since 2023. Capital expenditures for 2026 have been reduced by 8%, yet production is expected to remain stable. This is no magic trick, but the result of a consistent efficiency strategy. Free cash flow could rise to over USD 6 billion this year if oil prices cooperate.
Two recent announcements underscore the positive trend—first, an oil discovery in the Gulf of Mexico with high-quality production. Occidental holds a 45% stake. Second, the Trump administration confirmed funding commitments for two Direct Air Capture projects, including Occidental's "Stratos" facility. The carbon management business remains strategically relevant, even if investments are scaled back somewhat in 2026. Together with efficiency gains and a streamlined balance sheet, the company has several levers at its disposal, regardless of short-term oil price fluctuations. The next quarterly results on May 5 will show whether the roadmap is working. The stock is currently trading at USD 51.43.
The oil price shock is bringing the industry booming profits, but the creeping methane risk from millions of abandoned wells is opening up a parallel billion-dollar business. Shell is struggling between high refining margins and working capital effects worth billions due to skyrocketing inventory values. Zefiro Methane is successfully scaling its niche model, increasing revenue by over 50%, and reducing debt. Occidental Petroleum is focusing on efficiency, reducing debt to a decade-low, and driving carbon management forward. While major oil producers benefit from the price rally, the remediation of orphaned wells is emerging as a growing service market with significant revenue potential.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.