October 29th, 2026 | 05:23 CET
Hidden billion-dollar market: Zefiro Methane - Is this turnaround candidate poised for a re-rating?
Created and published on behalf of Zefiro Methane Corp.
While many small-cap stocks face headwinds in the current market environment, a specialised environmental services provider is making significant operational progress outside the market spotlight. Driven by government funding programmes and strict environmental regulations, demand for well-plugging and methane measurement services is surging. With a record order backlog, fresh capital and a move into operating profitability, the stock now offers an asymmetric risk-reward profile. The following special report examines why analysts see substantial upside potential.
time to read: 3 minutes | Author: Stefan Bode
ISIN: Zefiro Methane Corp | CA98926D1069
Table of contents:
Author
Stefan Bode
A native of the Eichsfeld region in the heart of Germany, he has more than 30 years of experience in the capital markets, with broad expertise spanning financial markets, history, and geopolitics. He founded his own business more than 20 years ago while still a student and today advises clients, foundations, and asset managers across four continents.
Tag cloud
Shares cloud
Significant increase in momentum at Zefiro Methane
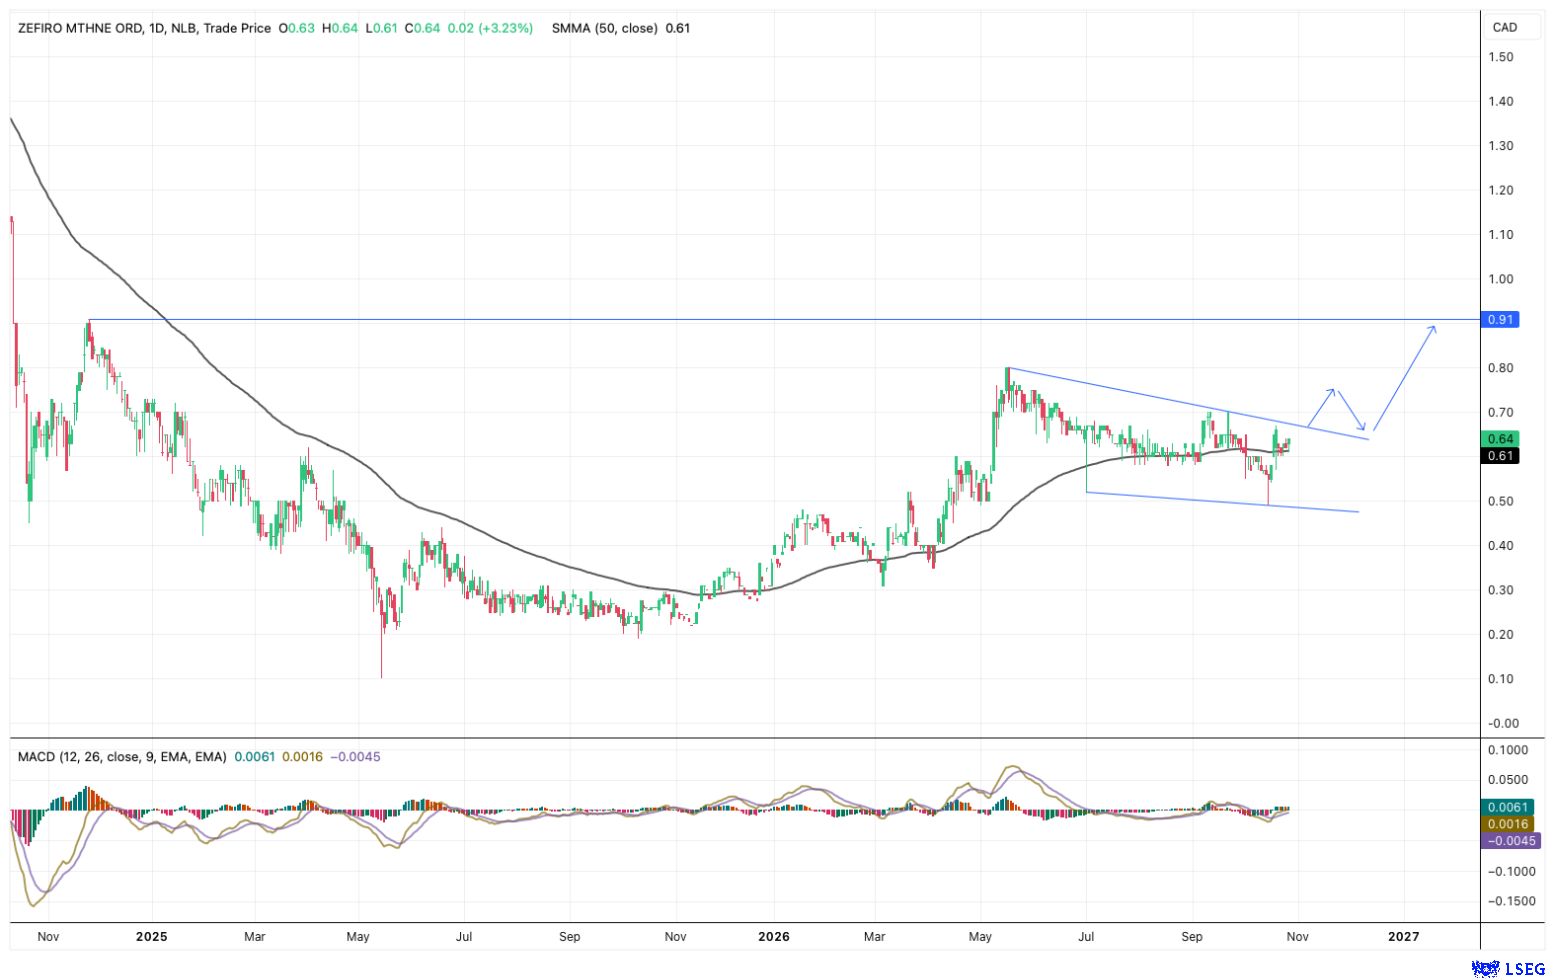
Zefiro Methane shares are trading at CAD 0.64 on its home exchange following a period of increased trading activity and repeated positive company announcements. In European trading, the price is around EUR 0.41. The market capitalisation currently stands at around CAD 68.75 million or EUR 44.00 million. The stock has gained 68% since the start of the year, while its 52-week performance stands at 120% despite the preceding summer consolidation (52-week range: CAD 0.29 to CAD 0.80). The market is increasingly responding to the significant growth, the accompanying operational scaling and the strategic positioning of the ESG environmental services provider.
Order book catalysts
The main catalyst for the recent share price momentum is the significant expansion in secured project and revenue volume. Zefiro recently reported a government order backlog of over USD 40 million, with terms running through June 2029, and signed its seventh new framework agreement following the integration of the Viking Well Service fleet. The fleet was acquired in May 2026, and within 6 months, Zefiro had leveraged these assets to secure framework agreements with almost all major gas producers in the northeastern US. 5 of the 7 framework agreements signed are already generating revenue. In August and September alone, these agreements generated USD 1.54 million in completed work. The company funded this expansion with a successful private placement last weekend, raising gross proceeds of around CAD 5.0 million to finance operational growth. These announcements in rapid succession not only significantly reduce refinancing risk, but may also put pressure on short sellers. Why? They may have anticipated financing at significantly lower prices, but the company placed the new shares at CAD 0.66, above the last traded price of around CAD 0.63. This suggests new investors value the company more highly than the broader market currently does.
Business metrics turn upwards
In the past financial year 2025/26, Zefiro's revenue jumped 31.1% to USD 42.5 million from USD 32.4 million the previous year. Adjusted operating earnings before interest, tax, depreciation and amortisation rose to USD 3.8 million, marking a successful turnaround from a prior-year loss of USD 4.0 million. The net loss narrowed significantly over the year from minus USD 10.8 million to minus USD 3.20 million. In the latest quarter, revenue reached USD 9.3 million, 16% above the prior-year quarter. Although free cash flow (FCF) was negative at minus USD 1.85 million due to investments made in the operational fleet, it will pay for itself directly in the coming quarters through the major contracts secured. At the same time, this forms the foundation for the EBITDA increase to USD 10.02 million forecast by analysts for the following year 2026/27.
Technical analysis provides support
The sell-off to CAD 0.49 on October 15 likely completed the technical bottoming process. Since then, the stock, currently at CAD 0.64, has moved above the 50-day moving average at CAD 0.62, the 100-day moving average at CAD 0.635, and the 200-day moving average at CAD 0.57, which should now serve as key support. On the upside, the area around CAD 0.69 forms the first relevant resistance. A sustained breakout above this would clear the way towards CAD 0.80. Should this be achieved, GBC's price target of CAD 2.10 (USD 1.50) provides a further reference point on the upside. On the downside, the price must not fall below CAD 0.48 again, as otherwise CAD 0.39 would likely come back into focus.
Conclusion
Zefiro Methane is achieving an operational turnaround in orphaned-well remediation thanks to government funding and a record order backlog of over USD 40 million. By selling its equipment to Zefiro, Viking Well Service enabled the geographical expansion of the operational fleet to 15 US states and the signing of new framework agreements with established gas producers in the northeastern US. The research firm GBC rates Zefiro stock a Buy, citing strong growth prospects and economies of scale, with a price target of USD 1.50 (CAD 2.10).
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.