November 17th, 2026 | 05:41 CET
Zefiro Methane in Focus Following Results: Analysts See Potential for a Threefold Gain
Created and Published on Behalf of Zefiro Methane Corp.
Before the excavators arrive for a new data centre, the legacy of the past sometimes has to be cleared away first. Beneath American building plots lie many abandoned oil and gas wells that have long been out of use but can still leak methane. Zefiro Methane makes money by professionally plugging these legacy wells. The Canadian environmental specialist has secured a substantial order backlog, won new customers and expanded its fleet. Now the investments are expected to pay off. The latest quarterly results show initial progress, while the carbon credit business offers additional upside potential. We take a closer look at the hot stock in our news check following the latest developments.
time to read: 5 minutes | Author: Lars Winter
ISIN: Zefiro Methane Corp | CA98926D1069
Table of contents:
Author
Lars Winter
A native of North Hesse, he has over 25 years of experience in financial journalism and active portfolio management and is regarded as a proven expert on German small-cap stocks and special situations.
After studying law at the University of Göttingen with a focus on banking and capital markets law, he began his career in Frankfurt's financial scene at the turn of the millennium. As a stock market and business journalist, the passionate amateur golfer wrote for leading investment newsletters, financial newspapers, and business magazines, including PLATOW Börse, Capital Depesche, BÖRSE ONLINE, Capital, and the Financial Times Deutschland.
Tag cloud
Shares cloud
Full order books and a new opportunity for high margins
Millions of disused oil and gas wells in the US still need to be properly plugged. Where no responsible operator exists, government programmes often step in. The US Infrastructure Act provides a multibillion-dollar budget for this. Private energy companies, by contrast, must pay to plug their own wells.
Environmental services provider Zefiro Methane measures emissions, plugs wells and restores the land. Through its subsidiary Plants & Goodwin, the company covers a large part of the value chain. Government support is likely to continue for years to come. Of the USD 4.7 billion the US Congress has allocated to remediating orphaned wells, around USD 4 billion is not due to be distributed until 2031. Zefiro's core states account for around USD 778 million of the funding allocated so far. According to the company, Zefiro has so far won around a quarter of the contracts financed by the infrastructure programme in its core regions.
With 25 service rigs and deployment capabilities in 15 US states, the company has a substantial operational base. Developers of energy facilities and data centres also require these services. In Pennsylvania, for example, nine gas wells were plugged on the site of a former coal-fired power station earmarked for a data centre.
USD 40 million provides planning certainty
The government order book totals around USD 40 million and extends through June 2029. A three-year contract in Ohio worth USD 19.6 million to plug around 200 wells is the largest item. In addition, a contract worth USD 11.5 million is scheduled to begin in November. In the current quarter ending in December alone, Zefiro aims to complete around USD 4.9 million of its government backlog.
The volume is spread over several years, supporting deployment planning. This helps limit transport and downtime. Private contracts come on top; because of short lead times, they do not appear in the reported backlog.
In the private-sector business, the Viking acquisition is bearing its first fruits. In May, Zefiro purchased additional equipment, including five service rigs, for USD 4.3 million. Since then, Zefiro has signed seven new framework agreements with corporate customers. Five of these customers have already contributed to revenue. In August and September, the acquired capacity generated around USD 1.54 million. Annualised, that would be more than USD 9 million annually, close to the targeted additional USD 10 million. Framework agreements do not, however, mean guaranteed call-off volumes.
New figures show encouraging progress on the previous quarter
In the first quarter of 2026/27 ending in September, Zefiro generated revenue of USD 12.1 million. Compared with the weak previous quarter, this represents an increase of 30.7%, but only a small increase of 0.1% year on year. The gross margin recovered from 18.6% to 20.4%, but remained below the previous year's 37.8%. The larger fleet and additional staff incur costs before they are fully utilised. This was compounded by higher expenses for items such as fuel and maintenance, as well as the absence of credit sales. Adjusted EBITDA reached just under USD 0.13 million, compared with minus USD 0.6 million in the previous quarter and plus USD 2.8 million in the previous year. The bottom line was a loss of USD 2.4 million. The direction of travel compared with the immediately preceding quarter is therefore encouraging.
Credits could improve the numbers
Voluntary carbon credits from verified emissions reductions achieved by permanently plugging methane leaks promise additional profits. Zefiro has already generated revenue from these. However, business has stalled because the American Carbon Registry is revising its methodology.
An additional opportunity is now opening up through the certification platform Isometric. Zefiro has co-financed and provided technical support for the development of a new framework for orphaned wells. Direct on-site measurements and a seal check after 12 to 18 months are envisaged. Only projects that would not go ahead without credit financing and are not already earmarked for plugging under a government programme are to be considered.
This could enable Zefiro to finance remediation work through credit sales where funding has so far been lacking. The framework still needs to be finalised, projects assessed and buyers secured. The prospect of high-margin revenue is attractive.
GBC continues to see substantial share price upside
Analysts at Augsburg-based financial services provider GBC Research see Zefiro Methane as a potential threebagger. The experts expect revenue to increase to USD 57.9 million in the current 2026/27 financial year, with EBITDA of around USD 10 million. Net profit is forecast to reach USD 4.2 million. By 2028/29, operating profit is expected to rise to USD 15 million. Based on the current share price of around CAD 0.67, the analysts calculated a P/E ratio of 12 and an enterprise value-to-EBITDA ratio of 5.7 for 2026/27.
GBC Research recently lowered its price target slightly from USD 1.50 to USD 1.42 (CAD 2.01). However, this valuation still offers share price upside of more than 200% and thus considerable room for gains, assuming the expected jump in profit materialises. GBC forecasts a doubling of profit within two years.
Meanwhile, Zefiro has also strengthened its financing capacity. On October 23, gross proceeds of CAD 5 million were raised through a private placement. Around 7.58 million units were issued at CAD 0.66 each, consisting of one share and half a warrant. The fresh funds are primarily intended to finance ongoing operations, facilitate the pre-financing of projects and provide the company's cash reserves with a sufficient buffer.
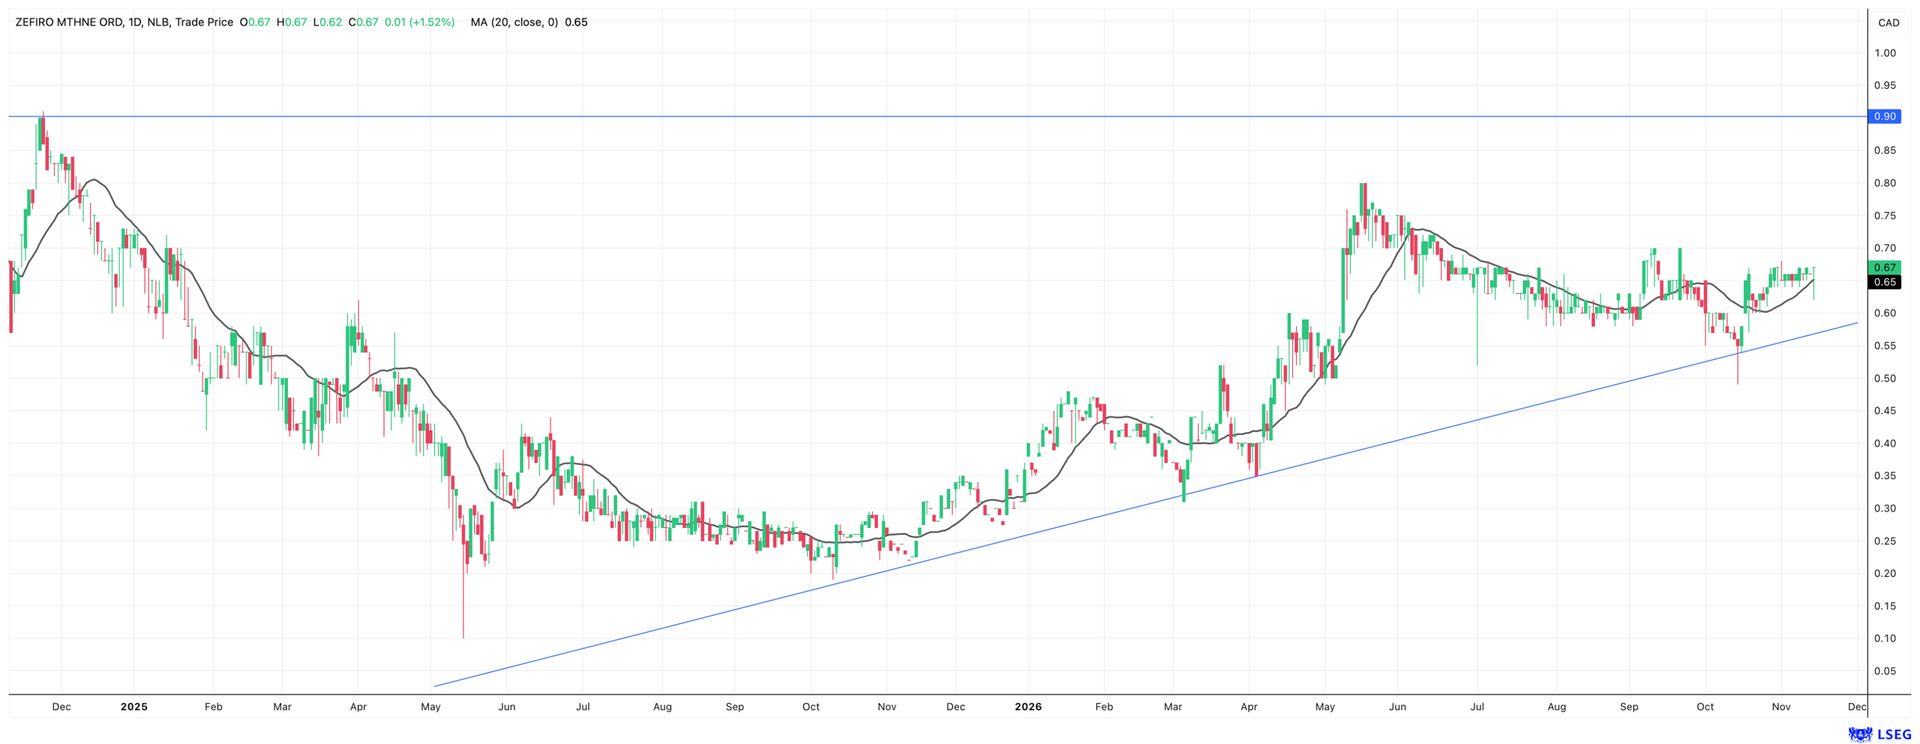
On its home exchange in Canada, Zefiro shares are currently trading at CAD 0.67, in the US at USD 0.46, and on German trading venues between EUR 0.41 and EUR 0.42. From a technical analysis perspective, the long-term uptrend remains intact. After doubling to CAD 0.80 between early April and mid-May, the stock has been in a stable, healthy consolidation phase for several months. For investors, the May high remains the key level. Reaching it would require a gain of around 19% from the current level. If the share price breaks above CAD 0.80 on rising trading volumes, this would signal the next upward move.
Zefiro has laid the foundations for further growth. The orders must now also deliver sustained benefits in the income statement. The latest quarterly figures already showed a recovery. For investors willing to take risks, the environmental specialist remains an exciting addition to a portfolio. If it succeeds in improving utilisation of the larger fleet and reviving the certificate business, speculation about a revaluation will gain fresh impetus.
Investor Day: Experience Zefiro live!
This Thursday, November 19, 2026, at 17:00 Central European Time, GBC Research and Apaton Finance invite you to the virtual Zefiro Investor Day. Over the course of an hour, Catherine Flax and Luke Plants will present the business model, the latest developments and the company's prospects. The subsequent Q&A session will be moderated by GBC analyst Matthias Greiffenberger. The event will take place via Zoom, and participation is free following registration.
Register here:
https://us06web.zoom.us/webinar/register/WN_C1iZ6V1oRymqeOaaSVy5nQ#/registration
Investors can send questions to Markus Nellessen, Head of Investor Relations at Apaton Finance, until 18 November: m.nellessen@apaton.com
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.