November 18th, 2026 | 05:28 CET
Copper at a crossroads: BHP produces less, Siemens Energy reports record orders – and Power Metallic Mines positions itself for growth
Created and published on behalf of Power Metallic Mines
Copper is becoming cheaper, even though the major mines are supplying less and grid equipment suppliers are reporting record orders. How does that add up? On the London Metal Exchange, the price of the red metal temporarily fell to around USD 13,515 per tonne on November 13, its lowest level since July. Goldman Sachs sees the main reason as investor positioning around AI stocks, not weaker physical demand. The bank therefore considers its forecast of USD 15,400 per tonne for 2027 potentially too high and sees USD 14,500 to 14,600 per tonne as more likely. A different picture emerges in industry: major mine operators are producing less because ore grades are declining and accidents or strikes are slowing extraction. At the same time, power grid equipment suppliers are reporting record orders. A high-grade copper deposit in Canada aims to fill this gap between falling mine supply and rising demand.
time to read: 4 minutes | Author: Nico Popp
ISIN: Power Metallic Mines Inc | CA73929R1055 , BHP GROUP LTD. DL -_50 | AU000000BHP4 , SIEMENS ENERGY AG NA | DE000ENER6Y0
Table of contents:
Author
Nico Popp
At home in Southern Germany, the passionate stock exchange expert has been accompanying the capital markets for about twenty years. With a soft spot for smaller companies, he is constantly on the lookout for exciting investment stories.
Tag cloud
Shares cloud
BHP Group: Accident, severe weather and declining grades
BHP Group shows how tight the supply side is. In the quarter to the end of September, the Australian group produced 400,700 tonnes of copper, 19% less than a year earlier. The Chilean mine Escondida, the world's largest copper mine, accounted for most of the decline: ore grades fell as planned, severe weather and maintenance slowed production, and operations were temporarily halted after a fatal workplace accident at the end of September. Escondida alone produced 252,600 tonnes in the quarter, 23% less than a year earlier. Nevertheless, BHP is maintaining its annual guidance. Chile as a whole produced 8.5% less copper up to September. According to the copper commission Cochilco, the country's average ore grade has fallen by around 45% over the past two decades. In Canada, workers at Teck Resources' Highland Valley Copper mine have been on strike since October 24, and the mine is operating at reduced capacity only. New mines that could offset these shortfalls are expensive. According to S&P Global, projects scheduled to enter production by 2030 cost an average of USD 22,359 per tonne of annual capacity.
Siemens Energy: Record orders driven by grid expansion and data centres
On the demand side is Siemens Energy. On November 11, the group reported a record order backlog of EUR 164 billion for the past financial year. The grid technology business increased its revenue on a comparable basis by 26.2% to EUR 14.1 billion, driven by grid expansion, including for new data centres. According to estimates by S&P Global, a data centre campus with 1 GW of capacity contains up to 47,000 tonnes of copper.
Power Metallic: High-grade resource in Québec targets the supply gap
Smelters worldwide are short of copper concentrate. In this environment, Power Metallic is positioning itself with its Nisk project in Québec. In early September, the company presented the first resource estimate under the Canadian NI 43-101 standard for the Lion Zone, the project's most important deposit. The more reliable Indicated category comprises around 4.15 million tonnes of ore with an average grade of 3.86% copper equivalent (CuEq). Including the Inferred category, Lion totals around 4.75 million tonnes at just under 3.9% CuEq, and the deposit remains open in several directions. The value is made up of copper and by-products such as palladium, platinum, gold and silver. Notably, around 60% of the total tonnage lies within the area of a potential open pit. In tests by SGS Canada, the ore proved readily amenable to processing. Copper recovery was over 98%, and the concentrate contains more than 25% copper. Five drill rigs are currently searching for extensions. Most recently, drill hole PML-26-125 intersected 5.70 m grading 14.00% CuEqRec (copper equivalent after expected recovery) at a depth of just under 800 m. This means the Lion Zone extends more than 25% deeper than the deepest drill hole in the resource estimate.
Power Metallic: Economic assessment under way, hydropower nearby
Since early October, engineering firm BBA has been leading the first preliminary economic assessment (PEA) for the Nisk project, with results scheduled for the first half of 2027. The study assesses an open pit followed by underground mining for the Lion Zone and examines whether the neighbouring Nisk Main deposit can be processed alongside it. One advantage of the location is its infrastructure: Hydro-Québec's Albanel substation is only around 4 to 9 km from the deposits, providing access to hydroelectric power. The work is funded in part by a CAD 28 million capital increase in June. To reach additional institutional investors, management is also working on a Nasdaq listing.
Conclusion: The physical deficit dominates the real economy
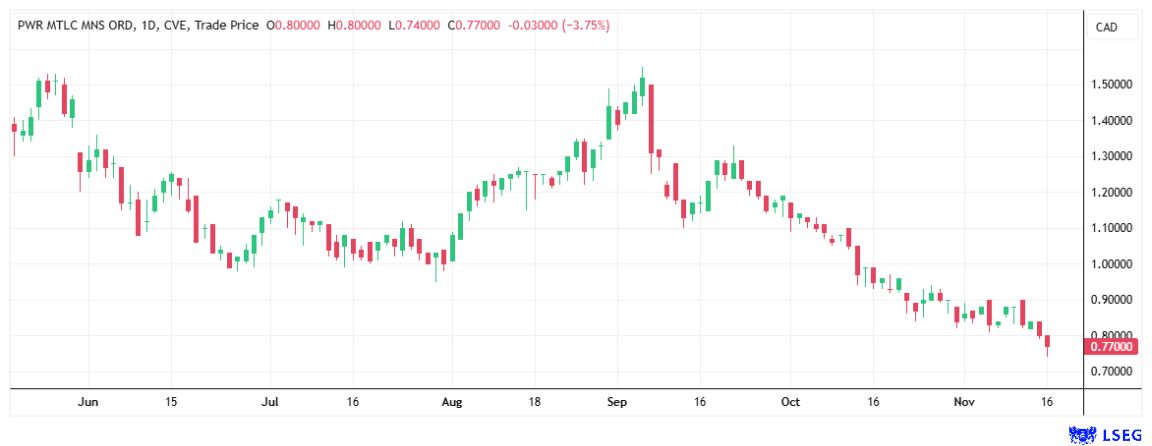
The price decline in the copper market primarily reflects sentiment in the financial markets, while supply in the real economy remains tight. Established producers are grappling with declining grades and industrial disputes, while demand from grid expansion continues to grow. With the Lion Zone at its Nisk project, Power Metallic offers a high-grade deposit readily amenable to metallurgical processing in a politically stable region. British research firm Hannam & Partners models processing of 500,000 tonnes per year in its base case, with low operating costs and an internal rate of return of 47%, rising to 71% in the expansion scenario. Following the resource estimate, the analysts raised their price target for Power Metallic Mines by 13% to CAD 2.70 per share. At the time of the study, this represented upside potential of 78%. As the company is still in the exploration and study phase, the share remains a speculative investment dependent on future financing.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.