October 21st, 2026 | 18:29 CEST
Almonty Industries: Bank of America sees share price weakness as an opportunity - Catch-up potential in the tungsten market
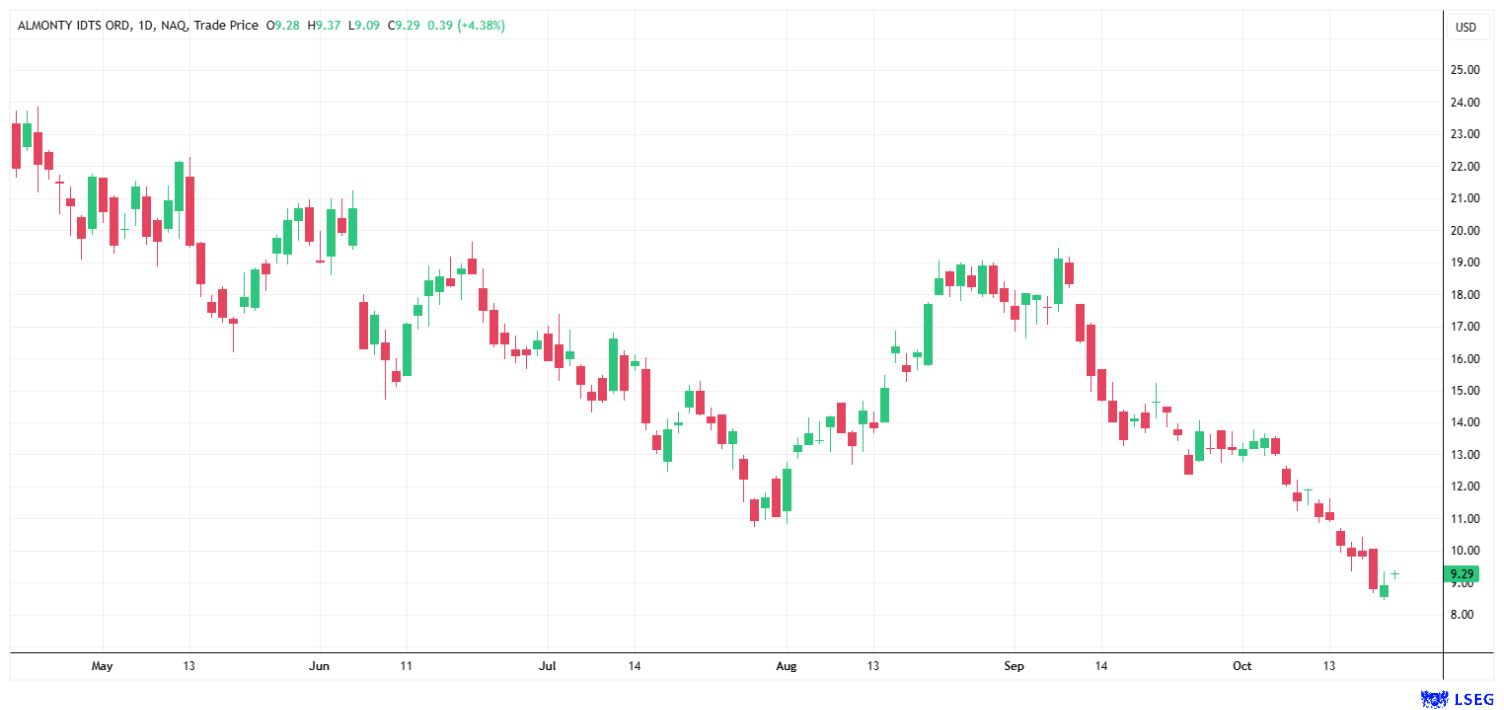
The European benchmark price for tungsten has risen 176% this year, driven by unexpectedly strong demand from the defence sector and ongoing Chinese export controls. While Almonty Industries shares have recently weakened, security of supply in the West is coming into focus: industry is desperately seeking tungsten. This is precisely where Almonty comes into play as one of the few producers building additional supply capacity over the coming years. Shortly before the first shipment of material from the Sangdong mine in South Korea, a recent Bank of America report with a price target of USD 24.00 highlights the company's key strategic role.
time to read: 3 minutes | Author: Nico Popp
ISIN: Almonty Industries Inc | CA0203987072
Table of contents:
Author
Nico Popp
At home in Southern Germany, the passionate stock exchange expert has been accompanying the capital markets for about twenty years. With a soft spot for smaller companies, he is constantly on the lookout for exciting investment stories.
Tag cloud
Shares cloud
Market dynamics and analyst assessment
Bank of America Global Research analysts position Almonty in their current study as one of only two publicly listed Western tungsten producers and the only player listed on a US stock exchange. At a share price of USD 8.90 (closing price on October 20), the experts reaffirm their Buy rating. Based on 2026 estimates, Almonty trades at an EV/EBITDA of 6.6x, and 1.6x for 2027. A peer group of critical raw materials producers in the uranium and rare earth sectors trades at market-weighted multiples of 41.0x and 17.4x, respectively, while copper producers trade at 9.0x and 7.6x, respectively. The analysts view the recent weakness in Almonty's share price as unrelated to fundamentals and therefore maintain their Buy recommendation.
On the way to historically low production costs
A key lever for future margins is the cost structure of ongoing projects. According to Bank of America, all-in sustaining costs (AISC) are expected to fall by almost half as production ramps up, to just over USD 200/MTU of tungsten trioxide (MTU WO₃) in 2029. According to Bank of America, this will place Almonty in the lowest-cost quartile of global tungsten production from 2027 onwards. Bank of America Global Research expects Almonty to perform positively throughout the tungsten commodity price cycle thanks to these low relative production costs. Following free cash flow of CAD 151 million in 2026, Bank of America forecasts a jump to CAD 753 million for 2027 and CAD 875 million for 2028.
Sangdong production and recycling deal for the EU
Bank of America Global Research expects production volumes to increase more than ninefold from 2025 to 2029, to 5,600 tonnes of tungsten trioxide (WO₃) per year. The main drivers are higher ore grades at the Panasqueira mine in Portugal and the ramp-up of the Sangdong mine in South Korea, which, according to Bank of America, is expected to reach its planned output within the next 60 days.
To further expand value creation, Almonty plans to build a tungsten oxide plant in addition to ore extraction alone. The Sangdong molybdenum deposit also offers additional potential for the operating business. At the European level, the company has entered into an agreement with Wolfram Bergbau und Hütten AG (WBH), a subsidiary of Sandvik. The agreement covers the supply of at least 1,720 tonnes of tungsten trioxide from the Los Santos mine's historical tailings. In addition, the company is advancing a joint venture in Rwanda, in which Almonty holds a 75% stake, positioning itself as the African country's largest tungsten exporter. Management underscores its confidence in the company's development through an approved share buyback programme of up to USD 300 million.
Conclusion: Unique strategic position and falling costs
With the upcoming first delivery from South Korea, the recycling initiative in Europe, and progress in Rwanda, Almonty is establishing itself operationally as one of the most important Western pillars of tungsten supply. Its unique strategic position and future production costs that will be among the lowest worldwide underpin the positive growth and margin forecasts from analysts at Bank of America Global Research. Professional analyses of this scope always also examine possible risks, such as a potential fall in tungsten prices, adverse currency movements or challenges during the operational ramp-up. Nevertheless, we consider the risk of a massive price decline to be relatively low. Almonty brings extensive experience in mine operations, and significant new competition is unlikely to enter the market for several years. Bank of America analysts also expect prices outside China to remain structurally above historical levels.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.