January 13th, 2026 | 07:00 CET
When the machines grind to a halt: Why Sandvik is trembling, and Almonty Industries is becoming a billion-dollar bet like MP Materials
The 2026 stock market year begins with a realization that is causing industrial producers worldwide to break out in a cold sweat: tungsten, one of the hardest and most heat-resistant metals, is sold out. What began with rare earths last year is now continuing with brutal severity for the material without which no armored steel can be hardened, no smartphone can vibrate, and - most importantly for the global economy - no industrial cutting tools can function. In this tense situation, Swedish industrial giant Sandvik is acting as the "canary in the coal mine" – the Company is signaling the situation on the tungsten market before all other market participants. Sweden's dependence on tungsten carbide is comprehensive. But while the industry struggles for security of supply, savvy investors are recognizing a historical parallel: the situation is the same as the rise of MP Materials in the rare earths sector. Almonty Industries, which owns the largest tungsten mine outside China, still trades at a fraction of MP Materials' valuation. Yet the Company is poised to become the West's tungsten monopolist.
time to read: 3 minutes | Author: Nico Popp
ISIN: SANDVIK AB | SE0000667891 , ALMONTY INDUSTRIES INC. | CA0203987072 , MP MATERIALS CORP | US5533681012
Table of contents:
Author
Nico Popp
At home in Southern Germany, the passionate stock exchange expert has been accompanying the capital markets for about twenty years. With a soft spot for smaller companies, he is constantly on the lookout for exciting investment stories.
Tag cloud
Shares cloud
Sandvik: The seismograph is sounding the alarm
To understand the scope of the crisis, one must look to Stockholm. Sandvik is not just any machine manufacturer, but the global market leader for cutting tools. As the Sandvik Group's Q3 2025 Interim Report shows, demand from the aerospace and automotive industries is robust, but CEO Stefan Widing recently issued an unambiguous warning about the risks in the supply chain. Without tungsten carbide, there are no indexable inserts, and without these inserts, neither engine blocks can be milled, nor aircraft turbines turned.
Sandvik painted a bleak picture in its "What Would Happen without Mining" campaign: a halt in the supply of tungsten would paralyze large parts of global manufacturing within weeks. The research makes it clear that recycling alone cannot satisfy the industry's hunger; dependence on Chinese primary material remains the group's Achilles' heel. Sandvik is willing to pay almost any price to keep the conveyor belts running, which drastically shifts pricing power to the few remaining producers.
MP Materials as a blueprint: The value of independence
For investors, the current situation is déjà vu. When tensions between China and the US over rare earths escalated, MP Materials' stock skyrocketed. The reason was simple: MP Materials owns the Mountain Pass mine, the only relevant asset in North America that could guarantee security of supply. The market paid a massive "geopolitical premium" for independence from Beijing.
Almonty Industries is now at exactly this point on the curve. According to EU and US classifications, tungsten is even more critical than many rare earths, as it is virtually irreplaceable due to its extremely high melting point of 3,422° Celsius. While MP Materials is already valued at around USD 11 billion, Almonty is still flying under the radar with its low single-digit billion valuation, even though the Company has an asset in the Sangdong mine in South Korea that is every bit as important as the Mountain Pass mine.
For investors, the following parallel suggests itself: those who missed out on MP Materials will find in Almonty a second chance to bet on the strategic decoupling of the West.
Almonty Industries: The Sangdong monopoly
Almonty's ace in the hole is the Sangdong mine, which recently ramped up production. The geological facts presented in the NI 43-101 Technical Report are impressive. With an average grade of 0.45% WO3, the ore in Sangdong is more than twice as rich as the global average of about 0.19%. This geological advantage translates directly into an unbeatable cost structure: while the marginal costs of Chinese producers are often between USD 200 and USD 250 per MTU, Almonty will produce at Sangdong at a cash cost of around USD 110.
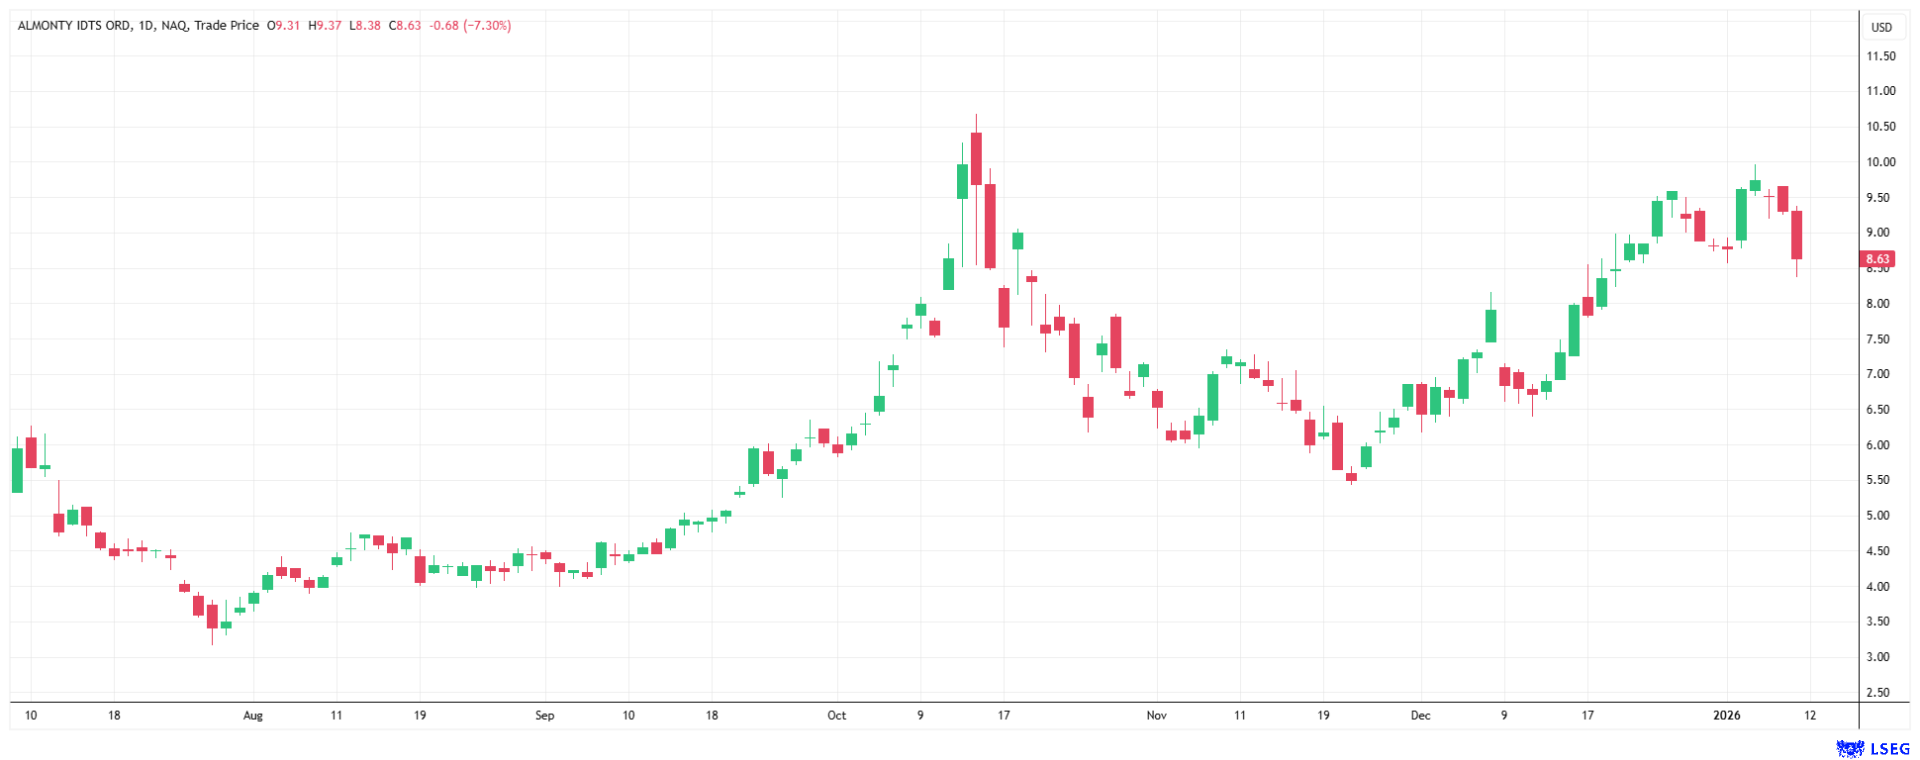
CEO Lewis Black, considered by industry insiders to be the most experienced tungsten manager in the West, has positioned the Company to take maximum advantage of the current price explosion. **According to current market data, tungsten in the form of APT is currently trading just below the USD 1,000 mark. At these prices, Sangdong becomes a money-making machine. Almonty thus not only offers security of supply for its customers in the defense and industrial sectors, but also an operating margin that is unparalleled in the mining sector.
Conclusion: The valuation gap must close
The facts are clear: the world needs tungsten, China is reducing supply, and companies like Sandvik have to buy at almost any price. Almonty Industries is the only player that can offer significant, new, and geopolitically secure capacities of this sought-after metal. Currently, the market is still pricing in development risks for Almonty, while it is already paying for production at MP Materials – given that Almonty has also been producing at its Panasqueira mine in Portugal for many years and the Sangdong giga mine in Korea is ramping up, the valuation difference seems too large. With each passing day, as the first production figures for Sangdong draw nearer, this risk diminishes. Investors are presented with a classic arbitrage situation here. Following the price decline in recent days, Almonty's stock appears all the more attractive.
Watch YouTube videoConflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.