October 28th, 2026 | 05:35 CET
USD 100 million in revenue soon? Zefiro Methane impresses analysts!
Created and published on behalf of Zefiro Methane Corp.
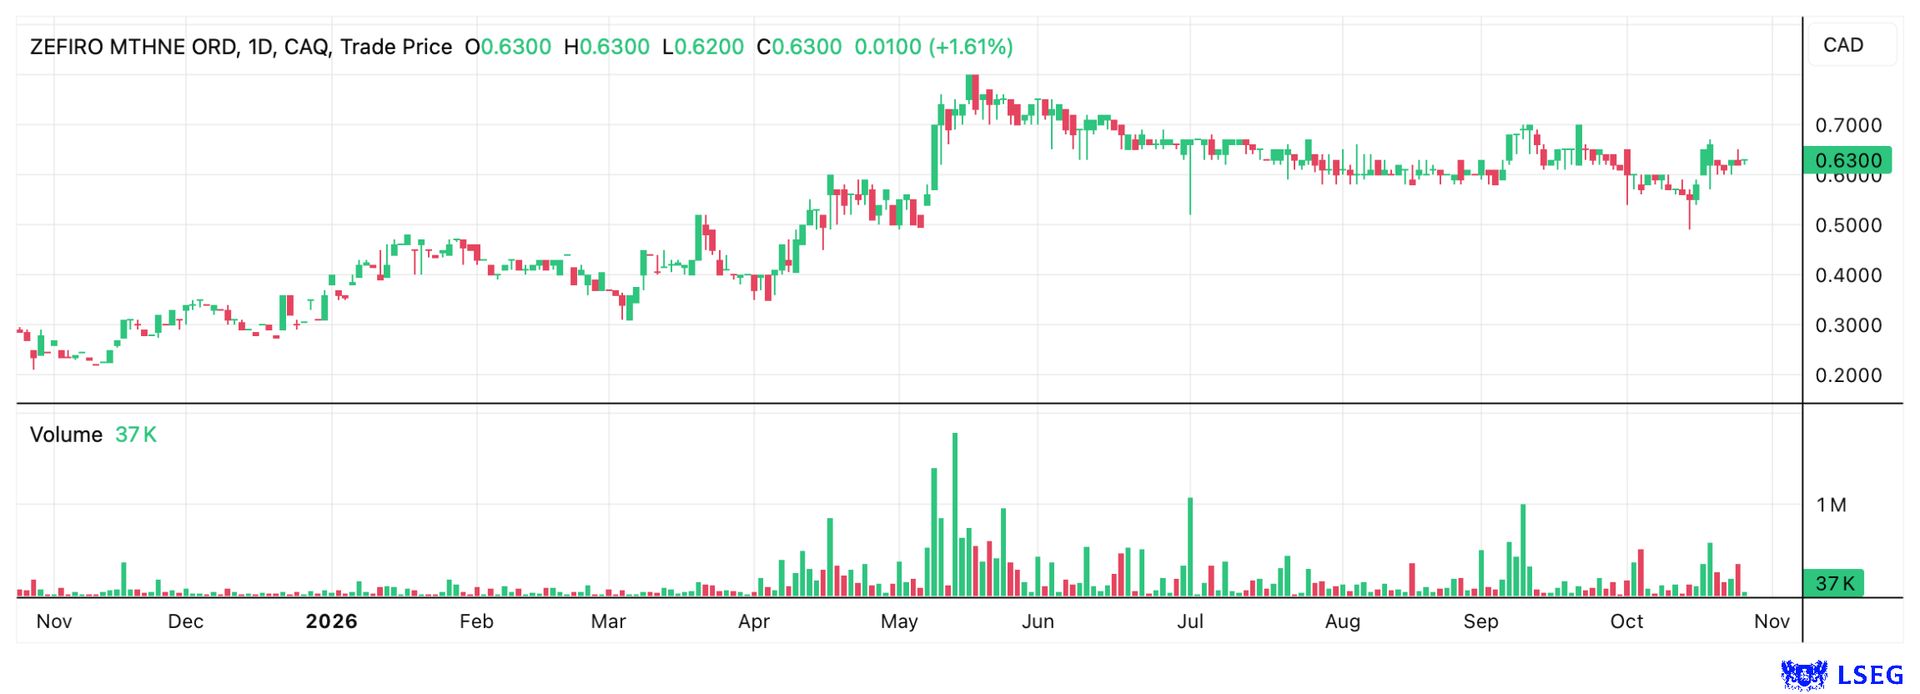
Zefiro Methane is poised for significant growth. The specialist in plugging orphaned oil and gas wells is benefiting from rising government investment and a vast remediation market in the US. The data centre boom is providing an additional tailwind, as rapid construction requires large, uncontaminated sites. With its existing capacity, the CEO believes annual revenue of nearly USD 70 million is achievable. Through organic growth and targeted acquisitions, the company aims to reach USD 100 million in the medium term. Yesterday's developments provided further evidence of its ability to select acquisition targets strategically. Yet despite record revenue, an operational turnaround and long-term orders, the share price has barely moved so far. Analysts see more than 200% upside potential. Is Zefiro Methane an overlooked growth story?
time to read: 5 minutes | Author: Fabian Lorenz
ISIN: Zefiro Methane Corp | CA98926D1069 , US30231G1022
Table of contents:
Author
Fabian Lorenz
For more than twenty years, the Cologne native has been intensively involved with the stock market, both professionally and privately. He is particularly passionate about national and international small and micro caps.
Tag cloud
Shares cloud
Analysts enthusiastic
GBC Research sees significant growth potential at Zefiro Methane and recommends buying the shares. The analysts believe Zefiro shares could rally by more than 200%. Their price target is CAD 2.12 or EUR 1.41, while shares currently trade at around EUR 0.41.
The analysts' investment thesis is based on the enormous remediation needs associated with millions of inadequately plugged oil and gas wells across the United States. In the US alone, the estimated cost of the required remediation totals USD 500 billion. With its subsidiaries P&G and AWS, Zefiro covers the entire value chain from investigation and decommissioning to environmental restoration. In the analysts' view, multi-year government contracts provide high revenue visibility, while acquisitions create additional capacity to accelerate growth. Following the change in management, operational performance has improved significantly. GBC sees additional potential in the carbon credits business, the resumption of which could generate high-margin revenue.
GBC Research's forecasts for Zefiro Methane's coming financial years are correspondingly optimistic. Following record revenue of USD 42.49 million in the 2025/26 financial year (ended June 30), the analysts already expect revenue of USD 57.92 million in the current 2026/27 financial year. Revenue is then expected to rise to USD 75.21 million by 2028/29. Zefiro is now starting to become highly profitable. EBITDA is expected to increase from USD 0.60 million in the past financial year to USD 10.02 million in the current year and USD 15.04 million in the 2028/29 financial year. The operational turnaround is also becoming visible in the net result. Following a loss of USD 3.55 million in the 2025/26 financial year, GBC forecasts a profit of USD 4.21 million for the current year. This is expected to rise to USD 8.31 million by 2028/29. Zefiro could thus increase revenue by around 77% within three years and become sustainably profitable.
Zefiro Methane's CEO Catherine Flax describes the growth opportunities and considers annual revenue of USD 100 million achievable:
How to make a successful acquisition
Targeted acquisitions are a clear part of Zefiro Methane's strategy to accelerate growth. The acquisition of equipment from Viking Well Service demonstrates its expertise in this area. In May 2026, it not only acquired five drilling rigs and other technical equipment, but also expanded into five additional US states. Zefiro paid USD 4.3 million and cited annual revenue potential of USD 10 million.
Yesterday, Zefiro demonstrated that the calculation was anything but optimistic and that the purchase price could perhaps even be described as a bargain. The specialist in well plugging and methane emissions reduction has concluded three further framework agreements (Master Service Agreements) with customers. Two of these are listed natural resources companies. This brings the number of new framework agreements made possible by the acquisition of equipment from Viking to seven. Zefiro now has active framework agreements with almost all major gas producers in the northeastern US. The company is strengthening its market position and laying the foundation for further growth in its high-margin business with corporate customers.
Five of the seven new framework agreements have already generated revenue. In total, Zefiro generated around USD 1.54 million in revenue in August and September 2026 alone from activities made possible by the acquisition of Viking equipment. Annualised, this equates to more than USD 9 million. The company is therefore already close to management's original forecast that the acquired equipment should increase annual revenue by around USD 10 million. As two of the seven new framework agreements have not yet contributed any revenue, there is additional potential.
Zefiro has also just raised fresh equity to fund further acquisitions. One or more interesting transactions could therefore be announced in the near future.
Strong order backlog secures growth
Even before its latest announcement, Zefiro Methane had reported a full order book. The company has a backlog of approximately USD 40 million in government-funded oil and gas well-plugging projects. Of this, orders worth around USD 4.9 million are expected to be completed in the current financial quarter, which ends at the end of December 2026. The bulk of the remaining orders, worth around USD 34.6 million, are expected to be carried out in 2027 and 2028. The final projects run through June 2029. The largest individual orders include a three-year contract worth USD 19.6 million to decommission around 200 wells in Ohio and another contract worth USD 11.5 million from the Great Lakes region on the border with Canada. As the order backlog comprises exclusively government-funded projects, potential revenue from private oil and gas companies would be additional. Zefiro therefore has a long-term revenue base that is not yet reflected in the published financial figures.
A new exploration contract with the Ohio Department of Natural Resources opens up additional growth opportunities. Under this contract, Zefiro undertakes preparatory work on orphaned wells before plugging and permanent decommissioning. This includes assessing the condition of the wells, exposing the facilities and taking initial technical measurements. Because these services are awarded separately from the decommissioning work, Zefiro gains an additional revenue stream. At the same time, the company can deploy its existing teams more efficiently and get involved in remediation projects earlier. CEO Catherine Flax sees the substantial order backlog as the foundation for increasingly converting the project pipeline into revenue in fiscal 2027. The long-term workload also makes it easier to plan staffing and drilling equipment through mid-2029.
Conclusion
Zefiro Methane has been delivering on its promises, as the past few months have shown. The latest figures demonstrate how effectively the company is implementing its buy-and-build strategy. Its substantial government-funded order backlog provides planning certainty. The need for remediation in the US is enormous, and the data centre boom could further drive demand. If Zefiro succeeds in making one or two acquisitions alongside organic growth, its medium-term revenue target of USD 100 million appears achievable, with profits potentially growing at a disproportionately faster rate. The share price has so far barely priced in these prospects. With upside potential of more than 200% according to GBC Research, Zefiro is an exciting growth story for the portfolio.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.