August 10th, 2026 | 07:15 CEST
New Wave of Liquidity from the Bessent Plan: Should Investors Turn to Vonovia, DRC Gold, and Strategy to Escape Currency Depreciation?
Japan is the largest holder of US Treasury bonds. The yen is currently extremely weak, driving up import prices and putting increasing pressure on Japanese households. Against this backdrop, signs are mounting of a coordinated currency intervention between Washington and Tokyo. Recently, US Treasury Secretary Scott Bessent was reportedly seen with a notepad indicating that the United States could be planning to purchase billions of dollars' worth of yen. Such a move could fuel a new wave of global liquidity, erode the purchasing power of cash, and push investors toward hard assets. The question is whether investors should turn to "concrete gold" (real estate), the yellow metal, or cryptocurrency. We therefore take a closer look at Vonovia, DRC Gold, and Strategy.
time to read: 5 minutes | Author: Armin Schulz
ISIN: VONOVIA SE NA O.N. | DE000A1ML7J1 , DRC GOLD CORP. | CA23347H1064 | CSE: DRC , STRATEGY INC | US5949724083 | NASDAQ: MSTR
Table of contents:
Author
Armin Schulz
Born in Mönchengladbach, he studied business administration in the Netherlands. In the course of his studies he came into contact with the stock exchange for the first time. He has more than 25 years of experience in stock market business.
Tag cloud
Shares cloud
Vonovia: First Half of 2026
In the first half of the year, Vonovia's operating business proved resilient. The core Rental business saw adjusted EBITDA rise by 3.5% to EUR 1.27 billion, despite a 5,000-unit decline in its portfolio. The higher rental income fully offset the reduction in the portfolio. The vacancy rate is low at 2.3%, and the collection rate is very solid at 99.6%. The Value-Add segment, comprising in-house maintenance organizations and the energy business, increased EBITDA by 27.6% to EUR 128.5 million and now contributes around 9% to the overall result. This means the target set for 2028 has already been achieved.
The sales divisions Recurring Sales and Development remain challenging. In residential privatization, the number of units sold declined from 1,134 to 687. Nevertheless, EBITDA rose slightly to EUR 39.3 million thanks to higher margins. The Development division recorded a 65% decline in earnings to EUR 20.1 million. However, a land sale in the prior year skews the comparison here. The real estate portfolio gained 1.1% in value excluding investments, and its market value rose to EUR 81.8 billion.
The increase in earnings was offset by higher financing costs of EUR 406.3 million, representing an 11.8% increase. Adjusted pre-tax profit fell by 2.6% to EUR 962.3 million. Since the beginning of the year, the Group has refinanced approximately EUR 4.4 billion and covered a portion of the maturities due in 2027/2028. Management is sticking to its forecast for 2026. However, reaching the upper end of the range could prove difficult given the persistently challenging market environment. Net debt stands at approximately EUR 37.6 billion. With a current share price of EUR 21.05, the company's market capitalization is around EUR 18.5 billion. This leaves considerable room relative to the EUR 81.8 billion property portfolio value. Refinancing remains the key factor.
DRC Gold: Exciting Gold Projects in the Congo
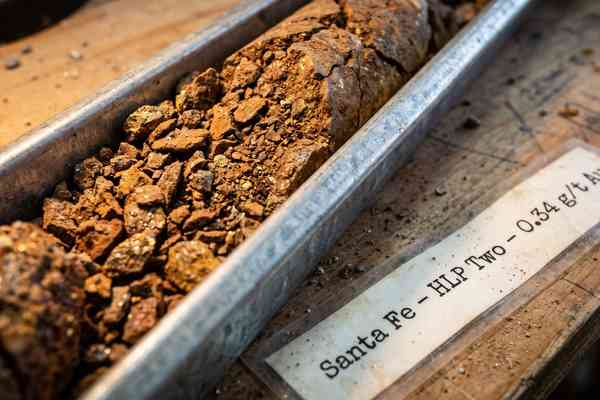
DRC Gold's two gold projects in the northeast of the Congo offer a promising starting point. Historical resource estimates for the Giro project stand at approximately 2.5 million indicated ounces. If you add the inferred resources, the total reaches as high as 4.4 million ounces. The deposit is located only about 35 km west of the producing Kibali mine and exhibits similar geological structures. Management estimates production costs of about USD 1,100 per ounce, with capital expenditures of less than USD 100 million. The Nizi project is a historic gold production site dating back to the 1930s that has never been systematically explored. The plan is to uncover additional resources in the range of 2–3 million ounces within the next two years. The acquisition price of approximately USD 6 per ounce is well below the typical valuations of comparable projects in other jurisdictions.
The management team led by CEO Klaus Eckhof has more than three decades of experience in the region. Under his leadership, Moto Gold Mines was able to define a resource of over 20 million ounces within four years. David Wargo, who joined the company in February, brings extensive financing experience as an investment banker for Congolese commodity companies. Thanks to the management's experience in the Congo, the company has access to local networks and permitting processes that represent a barrier to entry for competitors. DRC Gold can rely on well-established structures, which is an operational advantage in an environment characterized by bureaucracy and informal relationships.
The anchor shareholder, Raging River Capital, currently holds approximately 22.4% of the 133.7 million outstanding shares. The planned issuance of an additional approximately 325 million shares for the project acquisitions will result in dilution. However, the significant potential justifies this. The company currently has approximately CAD 3.5 million in cash, which is sufficient for the next steps. However, additional capital will likely be needed for larger drilling campaigns and the potential acquisition of an additional 10% stake in the two projects. If the upcoming drill results confirm the assumptions, the company will be exceptionally well-positioned with one of the most cost-effective gold projects on the market. And this comes with manageable political risk, as the properties are far removed from the troubled regions of the Congo.
Strategy: High-flying Days are Over
The once high-flying Strategy is now facing a crisis, as its latest quarterly results demonstrate. The reported net loss stands at USD 8.22 billion and is largely attributable to accounting-related Bitcoin impairments. Operationally, the software business is performing steadily, with revenue up 6.9% to USD 122.4 million. It is currently worth taking a closer look at the balance sheet. Strategy has reduced its convertible debt by USD 1.5 billion, while simultaneously expanding its preferred-stock capital significantly. This has fundamentally changed the company's capital structure. Preferred shares, valued at USD 14.4 billion, now dominate the balance sheet. The STRC preferred stock stands out here with its variable dividend yield, currently around 12%. Management has made it clear that stabilizing the preferred stock around its USD 100 par value is the company's top priority.
Strategy is now managing the company more actively than ever before. The Bitcoin holdings were most recently reduced by 1,638 tokens to 842,138. The proceeds were allocated equally to dividends and share buybacks. The USD reserve was increased to USD 4 billion, covering more than two years of dividend payments. This is intended to reassure the market, but it also shows that the pure Bitcoin strategy is reaching its limits. The capital raise via common stock took place in July at a price that was only slightly above the calculated Bitcoin value per share. The premium spreads, which used to exceed 100% in some cases, are a thing of the past. However, this also significantly reduces the leeway for further non-dilutive Bitcoin purchases. The 4.5% Bitcoin return since the beginning of the year shows that while the model still works, it is nowhere near as dynamic as in previous years.
The STRC preferred stock is facing a test, as the price drop to USD 89.50 clearly illustrates the challenge. Investors are demanding a higher return than management considers sustainable. The company has broken with its doctrine of pure holding. For shareholders, the key question is whether the model will remain viable in the long term. The balance sheet is solid, and the software business delivers reliable revenue. However, the leverage the company has built up through its preferred shares works both ways. The share price of around USD 100 reflects this uncertainty.
Germany has racked up record debt, while the US and Japan appear to be planning the next flood of money. As a result, tangible assets are becoming attractive. Vonovia shines with operational strength and substantial real estate value, but is struggling with high debt and refinancing pressure. DRC Gold, with its Congolese projects, offers one of the most attractive gold production potentials on the market. Strategy, on the other hand, highlights the risks of a pure Bitcoin strategy. Pressure on the preferred stock is mounting, while the former premium spreads are shrinking. Investors are left with a choice between stability, precious metal opportunities, and crypto speculation.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.