November 19th, 2026 | 05:25 CET
Lahontan Gold, Barrick Mining and Newmont: Nevada comes to Wall Street
The gold price is falling to its lowest level since October 2025 as investors expect the US Federal Reserve to raise interest rates in December. At the same time, the Monetary Authority of Singapore (MAS) is opening its vault to foreign central banks, with space for up to 500 tonnes of gold. Against this backdrop, Barrick Mining is listing its North American mines as a separate company on the New York Stock Exchange. What does this mean for small developers in Nevada, such as Lahontan Gold, which is seeking to bring a mothballed mine back into production?
time to read: 5 minutes | Author: Nico Popp
ISIN: Lahontan Gold Corp | CA50732M1014 , BARRICK MINING CORPORATION | CA06849F1080 , NEWMONT CORP. | US6516391066
Table of contents:
Author
Nico Popp
At home in Southern Germany, the passionate stock exchange expert has been accompanying the capital markets for about twenty years. With a soft spot for smaller companies, he is constantly on the lookout for exciting investment stories.
Tag cloud
Shares cloud
Barrick Mining: A new benchmark for Nevada
Barrick Mining filed for the initial public offering (IPO) of American Barrick Gold Corp. with the US securities regulator last week. The company is to be listed on the New York Stock Exchange under the ticker ABGC, with Barrick retaining a majority stake afterwards. The aim is a separate valuation for the North American mines, distinct from the operations in Africa and Asia. American Barrick brings together a 61.5% stake in Nevada Gold Mines, the world's largest gold mining complex, which now also includes the Fourmile project, and a 60% stake in the Pueblo Viejo mine in the Dominican Republic. The initial public offering will show what price investors are willing to pay for gold ounces in North America. In the 12 months to the end of June, the new company generated revenue of USD 14.16 billion and earnings of USD 3.33 billion. Attributable gold reserves of 40 million ounces are sufficient for 20 years. In 2025, the portfolio produced 2.0 million attributable ounces of gold, at all-in sustaining costs (AISC) of around USD 1,800 per ounce, according to Scotia Capital. Shareholders are to receive an annual base dividend of USD 1.25 billion. Renaissance Capital estimates the offering size at up to USD 6 billion, while Bloomberg previously cited a possible total valuation of more than USD 60 billion.
Newmont and interest rate headwinds
An agreement with Newmont, the partner in the Nevada Gold Mines joint venture, paved the way for the IPO. In August, the two groups settled their dispute: Barrick is contributing Fourmile to Nevada Gold Mines, while Newmont is contributing the Fiberline and Mike projects and paying an additional USD 1.95 billion in cash. This gives Newmont an interest in Fourmile through its 38.5% stake, and it is consenting to the initial public offering. Headwinds are coming from the interest rate environment. US producer prices in October were 6.5% higher than a year earlier, the largest increase since November 2022. Together with high consumer prices, this fuelled expectations of an interest rate rise in December. Gold briefly fell below USD 3,850 per ounce on Monday, while the yield on 10-year US government bonds is above 5%. The precious metal has lost around 31% since its record high in January. The US Federal Reserve will decide on December 8 and 9, with markets treating a 0.25 percentage point rate hike as largely a foregone conclusion. Despite falling gold prices, the gap between the gold price and production costs remains wide for major producers. Newmont reported all-in sustaining costs (AISC) of USD 1,621 per ounce and free cash flow of USD 2.2 billion for the second quarter. The group produced around 1.3 million ounces of gold during the quarter and held net cash of USD 3.4 billion at mid-year. For the full year, Newmont is targeting 5.26 million ounces at all-in sustaining costs of USD 1,680 per ounce.
Lahontan Gold: Restarting the Santa Fe mine
For smaller mining companies, high interest rates make financing new mines more expensive. Lahontan Gold plans to bring the historic Santa Fe mine in Nevada's Walker Lane back into operation in 2027. Between 1988 and 1995, the operator at the time, Corona Gold, produced 359,202 ounces of gold and 702,067 ounces of silver through open-pit mining and heap-leaching. According to the October PEA, the company expects all-in sustaining costs (AISC) of USD 2,250 per ounce at an initial rate of 12,500 tonnes per day. Old leach pads and waste rock dumps, not yet included in the study's mine plan, are expected to provide additional material. Around 16 million tonnes of rock were processed on the four historic leach pads, and CEO Kimberly Ann puts the gold remaining there at around 200,000 ounces. For rock that has already been mined, drilling, blasting, loading and haulage from the pit are not required.
Core drilling results published by Lahontan on Tuesday support this approach: 26 holes totalling 435.5 m yielded a weighted average grade of 0.34 g/t Au and 2.4 g/t Ag in leach pad 2. The gold grade is therefore around 17% higher than historical records had suggested. On average, 40% of the remaining gold is cyanide-soluble. Pad 2 once held 3.76 million tonnes of uncrushed rock, with only 47% of the gold recovered at the time. Together with drilling on the other three pads, the results will feed into a resource estimate under the Canadian NI 43-101 standard. Early last week, Lahontan also announced up to 100 drill holes in the eastern waste rock dump. It contains around 9.0 million tonnes of rock that was deposited as waste at a cut-off grade of 0.55 g/t at the time and will have to be moved during mining in any case.
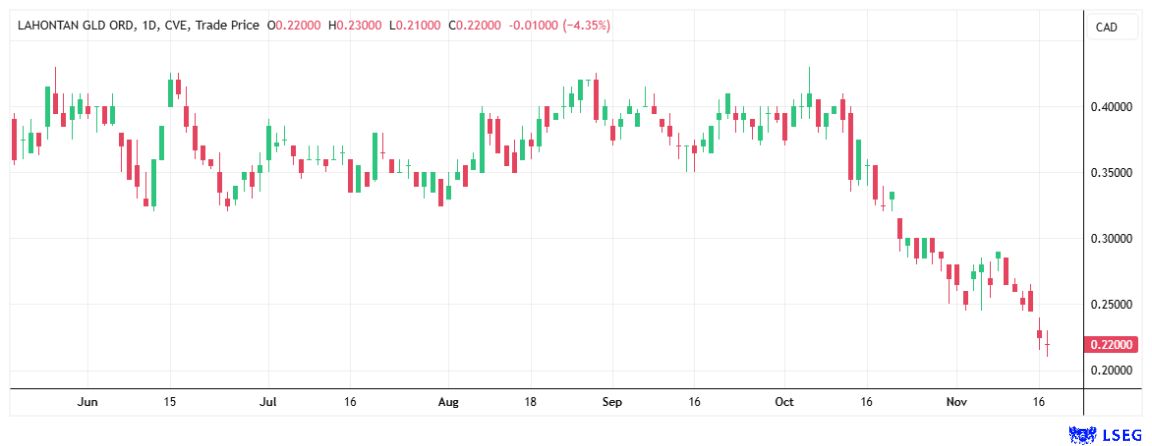
Economics and strategic positioning
In the base case, with gold at USD 3,600 per ounce, the study shows an after-tax net present value (NPV) of USD 820.0 million and an internal rate of return (IRR) of 40.1%, with start-up costs of USD 172.0 million. At October's spot price of USD 4,166 per ounce, the net present value rises to USD 1.13 billion. The mine is expected to operate for 11 years and deliver an average of 91,900 ounces of gold equivalent per year. An expansion to 17,000 tonnes per day is planned from the fourth year, with production then rising to around 112,500 ounces. Lahontan expects the mining permit in mid-2027 and the first gold pour by the end of 2027. According to the company presentation, the project has a payback period of around 3.7 years in the base case and is to be financed with 80% debt and 20% equity. If large funds subscribe to American Barrick's initial public offering, a public benchmark for the value of gold ounces in Nevada will emerge. This could also turn investors' attention towards smaller developers in Nevada. Lahontan has resources of 2.385 million ounces of gold equivalent, around half of which are in the Indicated category, and is working towards the start of production.
Conclusion: Nevada moves into the spotlight
With American Barrick's IPO and the agreement with Newmont, Nevada is moving into the spotlight for investors. Lahontan Gold combines the restart of the Santa Fe mine with the processing of old stockpiles, whose initial results exceed historical expectations. Next up are the resource estimate for the old stockpiles, the mining permit and financing. With its PEA, permitting process and stockpile programme, Lahontan has made good progress towards production in 2027.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.