October 29th, 2026 | 05:39 CET
Life Sciences in Focus as Sector Rotation Takes Shape: Bayer, Vidac Pharma, Eli Lilly, Novo Nordisk and Evotec in 2027
AI is consolidating, and the Life Sciences sector is firing up its first turbo: Rising healthcare spending, the demographic ageing wave and a veritable wave of innovation are catapulting the industry straight into a multi-year supercycle – and now the major players are reallocating their capital. AI and high-tech have delivered their returns, and now the new outperformers for 2027 are stepping into the spotlight. The catch: after years of heavy losses, most stocks are trading close to their 5-year lows. That will not last! Some companies are already waiting in the wings, with the painful restructuring completed. Leading the way, Novo Nordisk continues its relentless advance as the undisputed flagship of the global obesity and diabetes wave. A genuine hidden gem for return hunters is Vidac Pharma. Through its research into the Warburg effect, the biotech firm is revolutionising cancer therapy and, as a classic high-beta play, adds a dash of spice to opportunity-focused portfolios. The giant Bayer is also back, consistently using the current valuation lull as a major entry opportunity to ignite the next phase of growth with a revamped pipeline. The power quartet is completed by Hamburg-based drug discovery company Evotec, which benefits directly from demand for complex therapies as an indispensable infrastructure and development partner. Those who want to stay ahead in the coming Life Sciences boom need to set the course for their portfolio now!
time to read: 5 minutes | Author: André Will-Laudien
ISIN: Vidac Pharma Holding PLC | GB00BM9XQ619 , BAYER AG NA | DE000BAY0017 , US5324571083 , NOVO NORDISK A/S | DK0062498333 , EVOTEC SE INH | DE0005664809
Table of contents:
Author
André Will-Laudien
Born in Munich, he first studied economics and graduated in business administration at the Ludwig-Maximilians-University in 1995. As he was involved with the stock market at a very early stage, he now has more than 30 years of experience in the capital markets.
Tag cloud
Shares cloud
Novo Nordisk: Eli Lilly wins first round in court in the advertising war over fat-busting injections
Another setback! Danish pharmaceutical giant Novo Nordisk failed to obtain an interim injunction from a US federal court to stop rival Eli Lilly's aggressive marketing campaign. Judge Zahid Quraishi, who presided over the case in New Jersey, rejected the application because Novo Nordisk could not show any tangible market damage or sustained declines in prescription numbers for its bestsellers, Wegovy and Ozempic. From an analytical perspective, the ruling shows that the relentless battle for market share in the obesity drug market, worth tens of billions, has long been fought with bare-knuckle tactics and statistical tricks. Novo Nordisk had accused Eli Lilly of making unfair apples-to-oranges comparisons in advertisements by pitting the weight loss achieved with Lilly's Zepbound at the highest dose against low-dose Novo drugs. The court's assessment of the revenue impact of these campaigns as "negligible" gives Eli Lilly free rein for now to continue its aggressive marketing offensive unhindered. For investors, the skirmish underscores the enormous volatility of this duopoly: Both companies fire new, sometimes contradictory study and authenticity data at each other almost weekly to gain the upper hand in defining which fat-busting injection is more effective. The Q3 figures on November 4 should be very interesting!
Bayer: Approval in China fuels fresh hopes
Bayer's share price completed its consolidation phase in one decisive move. A bombshell from the Far East reverberated across the trading floor: long-battered pharmaceutical giant Bayer secured a genuine milestone in a market worth billions with Chinese approval for its promising drug Asundexian. From an analytical perspective, the regulator's green light for stroke prevention comes at just the right time to effectively cushion the drastic revenue declines caused by the patent expiry of its existing cash cows, Xarelto and Eylea. As the world's first approved FXIa inhibitor, the drug takes on a highly profitable pioneering role in the vast Chinese market, preventing blood clots without the dreaded risk of severe associated bleeding. The accelerated procedure builds on strong data from the Oceanic-Stroke study and now breathes urgently needed blockbuster hopes back into the shares after earlier Phase III setbacks. Geopolitically, this success in China gives the group enormous strategic leverage, significantly reducing its dependence on the struggling agricultural business. Investors' eyes are now fixed excitedly on the US, where a similar fast-track FDA approval process is nearing its conclusion. If Bayer pulls off its next coup there, the shares, previously battered from a technical perspective, could finally embark on a dynamic turnaround story. The Q3 figures are expected on November 3. Exciting!
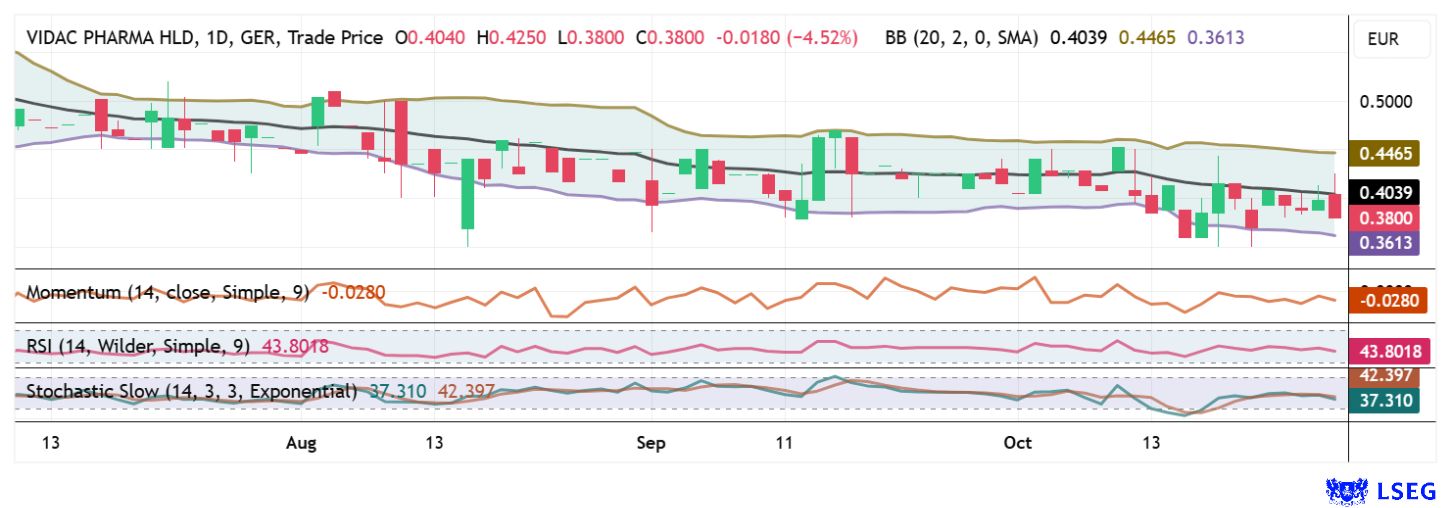
Vidac Pharma: Promising attack on cancer metabolism
Innovative biotech company Vidac Pharma is revolutionising modern cancer therapy by cutting off tumour cells' vital energy supply. Rather than weakening the entire body with conventional, aggressive chemical sledgehammers, the innovative lead candidate VDA-1102 blocks the specific key enzyme hexokinase-2, thereby forcing malignant cells into programmed cell death with high efficiency. Sector studies on global oncology underline the enormous economic significance of this visionary approach. The worldwide market for cancer drugs is rapidly heading towards a value of well over USD 200 billion, which could make a universally applicable metabolic platform technology an extremely sought-after takeover target for international industry giants virtually overnight.
A genuine share price catalyst is taking shape in oncodermatology, after the clinical team successfully treated all patients in the placebo-controlled Phase 2b study targeting precancerous, high-risk actinic keratosis. Following database lock, management is preparing the final statistical analysis, meaning that publication of the eagerly awaited topline data is imminent and is likely to fundamentally redefine the shares' intrinsic value. The patent portfolio, newly expanded into Canada, and the strategic move into the elite French biotech network "Quest for Health", which has already brought its members over EUR 220 million in fresh venture capital and opens first-class doors to global commercialisation partners, add share price potential and solid protection against imitators. While sluggish pharmaceutical giants such as Pfizer primarily manage their established legacy portfolios, this agile high-beta play offers bold investors the rare opportunity for massive leverage, underpinned by research firm Sphene Capital in a recent study with a clear price target of over EUR 4. Extremely exciting!
Evotec: The eternal hope for the invisible buyer
After its share price fell to a 13-year low in October 2026, crisis-hit Hamburg-based drug discovery company Evotec remains an extremely hot but highly speculative takeover candidate. Although earlier multibillion-euro offers, such as Halozyme Therapeutics' EUR 11 cash offer, ultimately failed due to management resistance, major investor Triton continues to keep the takeover scenario boiling hot. The latest reports of Abu Dhabi sovereign wealth fund Mubadala's complete exit shook up the shareholder structure and briefly dampened hopes of a swift bidding war. At the same time, recent voting-rights notifications confirm that major banks such as Goldman Sachs have expanded their complex derivatives positions to over 13%, pointing to massive hedging and positioning manoeuvres behind the scenes. On the operational front, preliminary nine-month figures beat market expectations and provided an unexpected positive surprise ahead of the official quarterly report on November 5, supporting the badly battered share price. To achieve a fundamental turnaround under its own steam, the new management is taking radical action through the cost-cutting programme "Project Horizon" and high-calibre recruits from Novo Nordisk. For investors, the share remains a double-edged sword: the fundamental recovery stabilises the foundations, but it also reduces the pressure to throw itself into the arms of the first available "invisible buyer" below its true value. After all the sell-offs, only 1 Buy recommendation remains on the LSEG Refinitiv platform. At EUR 4.38, the consensus price target is still 50% above the latest share price. If that isn't a contrarian indicator, what is? Highly speculative!
Conclusion
While the much-hyped AI sector is struggling with astronomical valuations and an acute risk of overheating after an unprecedented rally, the life sciences sector now offers a historically inexpensive and relatively defensive foundation. If a typical market sector rotation occurs, the companies mentioned above will very quickly find themselves back on buy lists. A rediscovery is long overdue. Healthy diversification guards against concentration risks.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.