October 2nd, 2026 | 07:05 CEST
RENK Under Pressure! Buy Signals for TKMS and Almonty
Alarm at Renk. The stock has slipped below EUR 40. It has now more than halved in value since its all-time high in October 2025. An analyst's comment sparked renewed unease. The comment warned of a potentially disappointing third quarter of 2026. Almonty shares are recommended as a "Buy". Analysts expect the tungsten producer to significantly increase revenue and profits in the coming years. Revenue is projected to exceed USD 1 billion in 2028. Almonty is then expected to be the largest Western supplier of this critical raw material. Analysts also recommend buying TKMS shares. A record order is taking shape. The order book is already full. The stock, however, is struggling.
time to read: 5 minutes | Author: Fabian Lorenz
ISIN: ALMONTY INDUSTRIES INC. | CA0203987072 | NASDAQ: ALM , RENK AG O.N. | DE000RENK730 , TKMS AG & CO KGAA | DE000TKMS001
Table of contents:
Author
Fabian Lorenz
For more than twenty years, the Cologne native has been intensively involved with the stock market, both professionally and privately. He is particularly passionate about national and international small and micro caps.
Tag cloud
Shares cloud
Almonty: Analysts Recommend Buying
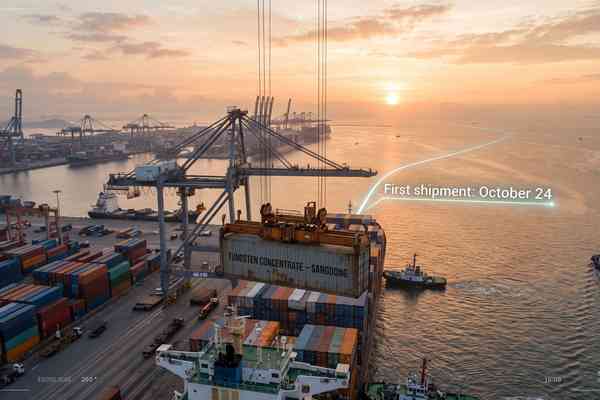
Stifel initiates coverage of Almonty Industries with a "Buy" rating and a price target of USD 25. Analysts say the expansion of tungsten production in South Korea and Portugal is driving the share price. With Sangdong, Almonty has brought one of the world's largest tungsten mines back into operation. Phase II is expected to roughly double capacity by 2027. At the same time, the Panasqueira mine in Portugal is being expanded. According to Stifel's assessment, this could make Almonty the largest tungsten producer in the Western world by the end of 2028. The tight market conditions are providing a tailwind. China controls about 80% of global tungsten production and has imposed export restrictions since 2025. As a result, prices for ammonium paratungstate (APT) have risen by about 775%. Stifel expects the market to remain structurally tight and for the APT price to stabilize at around USD 2,000 per MTU in the long term. This is a conservative estimate, as is the view of nearly all analysts, since the price has been at USD 3,000 for months. Tungsten is critical for industries such as defence and technology.
Stifel sees additional potential for Almonty in several projects not yet fully factored into the valuation model. These include additional tungsten deposits in Spain and the US, as well as planned activities in South Korea's molybdenum and tungsten oxide sectors. Establishing downstream tungsten oxide production could also integrate Almonty more deeply into the value chain over the long term. Stifel also views the existing offtake agreements positively, as they secure a portion of future production, while uncommitted volumes allow the company to benefit from the current high price levels. Overall, the research report views Almonty as well-positioned to benefit from the strategic realignment of Western supplies of critical raw materials and the growing importance of tungsten for the US defence industry.
For full-year 2026, Stifel analysts expect Almonty to generate revenue of CAD 345.8 million. Next year, that figure is projected to reach CAD 926.2 million. EBITDA is expected to climb from CAD 247.1 million to CAD 792.7 million.
Sphene Capital is slightly more optimistic on growth but more conservative on margins. The analysts project that Almonty will generate revenue of USD 308 million this year. In 2027, revenue is expected to reach USD 786.1 million. In 2028, the company is projected to break the billion-dollar mark, generating USD 1.36 billion. EBITDA is expected to rise during this period from USD 114.8 million to USD 979.5 million. Sphene Capital also recommends buying Almonty shares. The price target is USD 26.40. The tungsten producer's stock is currently trading just above USD 13, bringing its market capitalization to approximately USD 4 billion. The stock is also actively traded on German exchanges such as Tradegate.
TKMS: Record Order Takes Shape
While investors are not currently embracing defence stocks, TKMS shares are at least holding above the EUR 80 mark. From mwb research's perspective, this is too low. mwb research has reaffirmed its "Buy" recommendation with a price target of EUR 140.
Analysts see TKMS on the verge of securing another major contract. The focus is on India’s P75(I) submarine program. Under this program, six conventional submarines are to be built for a total of approximately EUR 8 billion. According to German Ambassador Jasper Wieck, Germany has already completed its internal approvals. On the Indian side, only the final steps remain. TKMS would not be responsible for the entire construction process, but rather primarily for design, system integration, and technical supervision. Mazagon Dock Shipbuilders would handle production in India. mwb estimates TKMS's share of the contract at approximately EUR 3.5 billion. The project's structure could even enable above-average margins, as TKMS bears fewer construction and manufacturing risks and focuses on higher-margin engineering, integration, and, later, potentially service activities.
According to mwb's assessment, the India contract is at a very advanced stage. A formal signing and initial advance payments could occur as early as the current fiscal year and positively impact free cash flow. As of the end of June, TKMS already had a firm order backlog of EUR 20.1 billion. Upon signing the contract, the company described the India project as potentially the largest single order in its history. Including additional framework agreements and projects not yet firmly booked, mwb estimates a potential order volume of around EUR 64 billion—roughly 30 times the annual revenue expected by analysts.
Revenue is expected to rise by 11.1% to EUR 2.69 billion in 2027. In 2028, growth is projected to accelerate to 17.1%, with revenue rising to EUR 3.15 billion. EBITDA is projected to climb from EUR 303 million in 2027 to EUR 385 million in 2028. For net income, mwb expects an increase from EUR 154 million to EUR 189 million. This would mean that TKMS would not only achieve double-digit revenue growth but also further expand its profitability.
Renk: Analysts Sound the Alarm
While Almonty and TKMS are performing well operationally and the main question regarding their stocks is when the next rally will begin, alarm bells are ringing at Renk. The stock recently slipped below the EUR 40 mark and is thus clearly struggling from a technical perspective. So far this year, the defence stock has lost around 30% and has more than halved from its all-time high in October 2025.
JPMorgan sparked fresh concern on Monday. Analysts have warned of a potentially disappointing third quarter of 2026. Renk will report its earnings on November 9; tension is likely to remain high in the run-up.
Just how sensitive investors are right now was already evident in their reaction to JPMorgan's price target cut. Analysts lowered their target from EUR 75 to EUR 62. That sounds significant at first glance, but even the new price target is still well above the current market price of EUR 38. One trading day earlier, Berenberg had confirmed its "Buy" recommendation with a price target of EUR 72. This aligns with current market sentiment that investors largely ignored the announcement.
The Bottom Line
Buying Renk shares is not a priority right now. The outlook for Almonty and TKMS is significantly more positive. Almonty benefits from what is likely a unique position in the market for the critical raw material tungsten. Revenue and profits are expected to rise sharply. TKMS has a huge order backlog. However, the complexity of shipbuilding should not be underestimated.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.