November 12th, 2026 | 05:32 CET
Tungsten rally: Who really profits – Kennametal, Sandvik, Rheinmetall or Almonty?
Tungsten is more expensive than almost ever before – but who actually profits from it? The price of the intermediate product ammonium paratungstate (APT) has multiplied since September 2023 and at times exceeded USD 3,200 per MTU in Rotterdam in the summer of 2026. S&P Global puts the gap between demand outside China and mine supply there for 2026 at around 21,000 tonnes WO₃. The result is paradoxical: Western tool manufacturers are reporting record profits, while the few producers outside China are being punished on the stock market. We take a look along the supply chain – from the mine to armour-piercing ammunition.
time to read: 4 minutes | Author: Nico Popp
ISIN: Almonty Industries Inc | CA0203987072 , SANDVIK AB | SE0000667891 , RHEINMETALL AG | DE0007030009
Table of contents:
Author
Nico Popp
At home in Southern Germany, the passionate stock exchange expert has been accompanying the capital markets for about twenty years. With a soft spot for smaller companies, he is constantly on the lookout for exciting investment stories.
Tag cloud
Shares cloud
Kennametal and Sandvik: Record profits with an expiry date
When prices for intermediate goods rise, tool manufacturers should really suffer from shrinking margins. The opposite is the case. On November 4, Kennametal reported revenue of USD 768 million for the first quarter of its 2027 financial year, up 54% from a year earlier. Operating profit rose to USD 379 million. According to the company, around USD 323 million of this is attributable to selling prices running ahead of raw material costs. Kennametal has already raised prices, while tungsten purchased at higher prices feeds through to costs only with a delay. The outlook shows how temporary the effect is. For the current second quarter, Kennametal expects adjusted earnings per share of just USD 1.20 to USD 1.50, compared with USD 3.48 in the first quarter. Sandvik also recorded an additional profit of SEK 104 million from tungsten price developments in the third quarter. In the long term, Sandvik is focusing on the circular economy and aims to achieve 90% circularity by 2030, including through the buyback of used carbide tools.
Rheinmetall: Full order books, high cash outflows
No sector demonstrates the importance of tungsten as clearly as defence. The metal is the material of choice in armour-piercing ammunition. Rheinmetall uses it for the KE2020Neo kinetic energy projectile, for example, because, unlike the US, the Bundeswehr and other European armed forces do not use depleted uranium. Rheinmetall reported an order backlog of EUR 78.0 billion after the first nine months of 2026, while revenue in the Weapon and Ammunition segment rose by 34% with an operating margin of 23.4%. Nevertheless, the shares fell sharply following the results in early November. Operating free cash flow was minus EUR 1.698 billion, mainly due to the inventory build-up for the planned growth. The group also lowered its 2026 revenue forecast to around EUR 13.2 billion, partly because the order for the Bundeswehr's Arminius project is being pushed back to next year. For the tungsten market, something else matters: Tungsten that has been fired is lost and must be replaced with new material from mines.
Almonty Industries: Production starts with a tailwind from Washington
While buyers have to contend with high prices, Almonty Industries, one of the few Western producers, is pushing into the market. On October 13, the Nasdaq-listed company now based in Montana announced commercial operations at its Sangdong mine in South Korea – the first tungsten production there in more than 30 years. In its first expansion phase, the facility is designed to process 640,000 tonnes of ore per year, with a second phase set to double throughput to 1.2 million tonnes. The demand is there: according to estimates by the US Geological Survey, China produced around 67,000 of the world's 85,000 tonnes of tungsten in 2025. It limits mining through quotas – the first allocation for 2025 stood at 58,000 tonnes – and has also controlled exports since February 2025. From January 1, 2027, suppliers to the US Department of Defense will no longer be permitted under the DFARS procurement regulations to supply tungsten powder or tungsten heavy alloys mined or processed in China, Russia, Iran or North Korea. On July 14, 2026, Almonty extended its offtake agreement with Pennsylvania-based Global Tungsten & Powders (GTP) from 15 to 21 years, increased the volume by 40%, and improved prices by around 6.3%. The agreement covers around 90% of concentrate production from the first expansion phase.
The valuation paradox: Why investors are punishing producers
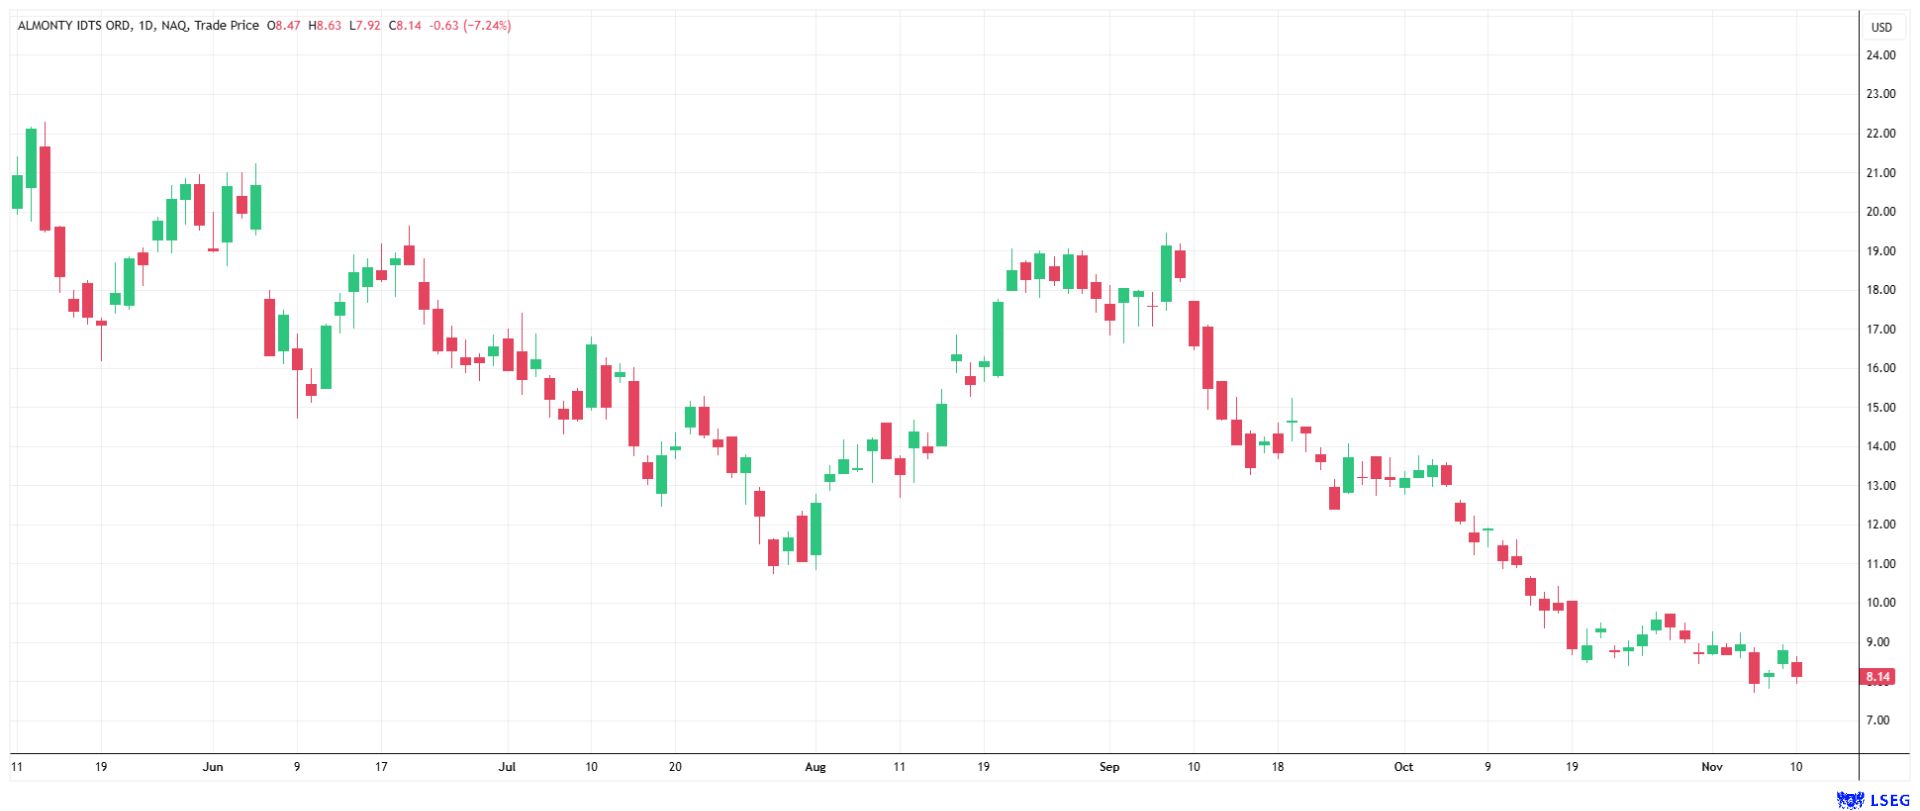
Despite the start of production, Almonty shares were trading around two-thirds below their 52-week high of USD 24.41 in early November. Although the second-quarter 2026 report showed a net profit of CAD 181.8 million, CAD 173.1 million of this consisted of non-cash valuation gains on derivatives and warrants, mainly linked to a USD 800 million convertible senior notes offering. For mines, investors pay less attention to such paper profits than to production and cash flow – and to potential dilution if the bond is converted into shares. There were also concerns about the ramp-up. On the Investor Day, October 19, the shares fell by around 10%. Financially, however, Almonty is well equipped: at the end of June, it had around CAD 1.2 billion in cash. With the Panasqueira mine in Portugal, the company has also been operating a tungsten mine for years and brings the corresponding expertise. This experience is an advantage in mining, as new projects in particular often fail at the implementation stage. With Panasqueira, Almonty brings years of operating experience to a phase when that matters most.
Conclusion: Value creation is shifting to the mine
The tool manufacturers' exceptional profits are likely to run out once the expensive tungsten is fully reflected in their costs. With the new US procurement rules, however, those who mine tungsten outside China are gaining in importance. Those who can reliably supply tungsten from beyond China's sphere of influence are likely to have the stronger negotiating position in future. On October 21, 2026, Bank of America analysts reiterated their Buy recommendation for Almonty with a price target of USD 24. They regard the recent share price weakness as unjustified by fundamentals and expect Almonty to increase its tungsten production more than ninefold between 2025 and 2029, while production costs per MTU almost halve. Other firms, such as Oppenheimer, B. Riley, and Stifel, lowered their price targets in October but continue to recommend buying the shares. Almonty shares are currently going through a challenging phase, but fundamentally the company appears very well positioned to emerge stronger from this market phase.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.