July 3rd, 2026 | 08:15 CEST
The Spark in the Portfolio: How Milestones Unlock the True Value of Desert Gold, Siemens, and Mutares!
The stock market trades on the future. Yet a stock's most rewarding phases often begin when future promises turn into tangible milestones. Whether it is the transition to gold production in West Africa, strategic carve-outs in industry, or successful turnarounds in the private equity sector, reaching a key milestone can mark the beginning of a fundamental re-rating. In particular, the transformation from gold explorer to producer—as Desert Gold Ventures is currently pursuing—has historically been associated with higher valuations. Project-specific risks decline significantly, while the prospect of future cash flows supports a fundamentally different valuation framework. The latest developments at all three companies are noteworthy—and well worth a closer look.
time to read: 3 minutes | Author: Carsten Mainitz
ISIN: DESERT GOLD VENTURES | CA25039N4084 | TSXV: DAU , OTCQB: DAUGF , SIEMENS AG NA O.N. | DE0007236101 , MUTARES KGAA NA O.N. | DE000A2NB650
Table of contents:
Author
Carsten Mainitz
The native Rhineland-Palatinate has been a passionate market participant for more than 25 years. After studying business administration in Mannheim, he worked as a journalist, in equity sales and many years in equity research.
Tag cloud
Shares cloud
Desert Gold Ventures: Historic Turning Point
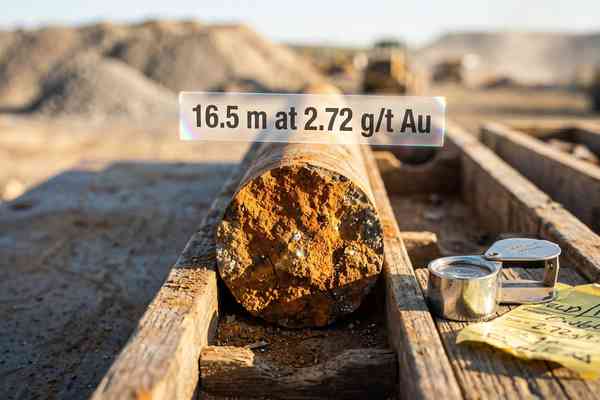
The Canadian company is at a historic turning point that could soon lead to a significant revaluation of its share price. The explorer operates in the West African nation of Mali. The flagship SMSZ (Senegal-Mali Shear Zone) project covers an area of 440 km². The property lies directly on one of the world's most productive gold structures, in the immediate vicinity of Tier-1 mines operated by industry heavyweights such as Barrick Mining and B2Gold.
Until now, the company has been viewed as a pure-play explorer and thus associated with high risks and ongoing capital requirements. Now, however, the picture could change dramatically. The Canadians have announced that gold production is set to begin this month. To take the final steps toward production, a capital increase of more than CAD 7 million was completed at the beginning of the year at a price of CAD 0.08.
Desert Gold has a resource base of 1.1 million ounces of gold. However, these deposits are based on only about 10% of the total area. The recently updated preliminary economic assessment (PEA) underscores the enormous potential. At a gold price of USD 2,850 per ounce, the project value is USD 61 million, with an internal rate of return (IRR) of 57%. At a gold price of USD 4,070 per ounce, roughly the current level, the project value doubles to around USD 124 million.
In contrast, the market capitalization at a share price of CAD 0.10 is only around CAD 36 million, or USD 25 million. GBC analysts see potential for significant growth based on their price target of CAD 0.95. Given the current gold price and low production costs, high margins and strong cash flows are on the horizon. In addition, the Canadian company plans to reinvest the proceeds into further project expansion, which avoids dilution for existing shareholders.
In the medium term, the company has another ace up its sleeve: the Tiegba Gold project in Côte d'Ivoire. The 297 km² property is located in the high-grade Birimian Belt, home to a number of deposits containing several million ounces of gold. The same potential could lie dormant in Tiegba.
CEO Jared Scharf in conversation with IIF host Lyndsay Malchuk.
Siemens: A Model Company
No other German publicly traded company has demonstrated as clearly as Siemens how radical structural changes can unlock value. Its consistent spin-off strategy has produced many success stories, including Infineon, Siemens Healthineers, and Siemens Energy. Siemens Energy, in particular, has staged a breathtaking rally on the stock market in recent quarters, driven by the enormous energy demand of global AI data centers.
Thanks to its spin-off strategy, Siemens has successfully transformed itself into a highly profitable, digital technology group and shed its conglomerate discount. Today, Siemens is one of the world's largest players in the fields of industrial automation, digitalization, infrastructure, and smart energy technology.
Shares are currently trading at around EUR 276. Investors are eagerly awaiting the third-quarter report, which is scheduled for release on August 6. Analysts at JPMorgan recently reaffirmed their bullish outlook for the company, setting a price target of EUR 345.
Mutares: A Good Harvest
Mutares' business model is based on acquiring underperforming corporate spin-offs (carve-outs), turning them around operationally, and then selling them at a substantial profit or taking them public. The private equity investor has impressively demonstrated this in the past and allows its shareholders to benefit through an attractive dividend policy with a minimum payout of EUR 2 per share.
At Mutares, milestones are virtually institutionalized. The company operates in three phases: acquisition, operational turnaround, and exit. To further accelerate the pace of expansion, particularly in the US and China, a capital increase of approximately EUR 100 million was recently carried out. The medium-term targets have been significantly raised. The company is projecting annual profit growth for the holding company of at least 25% through 2030.
For the current fiscal year, the company has forecast earnings in the range of EUR 165 million to EUR 200 million. At a current share price of EUR 28, the company is valued at approximately EUR 700 million. In their latest report, analysts at Warburg Research set a price target of EUR 41.
The countdown for Desert Gold is on. With gold production set to begin in the coming weeks, the stock should see a revaluation. The project's value and analyst ratings point to several hundred percent upside potential. Experts also see upside potential for the "value-creating" stocks of Siemens and Mutares.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.