September 25th, 2026 | 07:30 CEST
Sell Hensoldt? Copper at Record Highs! Power Metallic Mines Set to Benefit; Nordex Keeps the News Flow Coming!
Supply concerns are colliding with growing demand driven by power grids, electrification, and the expansion of AI infrastructure. This is pushing copper prices to record highs. One potential beneficiary with catch-up potential is Power Metallic Mines. The Canadian company is developing a world-class project with a high copper content. Analysts and the CEO believe the stock is undervalued. The latest resource estimate impressed, and the project's potential is likely even greater. Hensoldt, by contrast, offers no further upside, according to analysts. They question the company's long-term growth prospects and believe its valuation premium over Renk and Rheinmetall is not justified. Nordex is also considered ambitiously valued. However, the German wind-turbine maker continues to generate fresh share-price momentum through a steady stream of news.
time to read: 6 minutes
|
Author:
Fabian Lorenz
ISIN:
HENSOLDT AG INH O.N. | DE000HAG0005 , POWER METALLIC MINES INC. | CA73929R1055 | TSXV: PNPN , OTCBB: PNPNF , NORDEX SE O.N. | DE000A0D6554
Table of contents:
Author
Fabian Lorenz
For more than twenty years, the Cologne native has been intensively involved with the stock market, both professionally and privately. He is particularly passionate about national and international small and micro caps.
Tag cloud
Shares cloud
Power Metallic Mines: When Will the Stock Take Off?
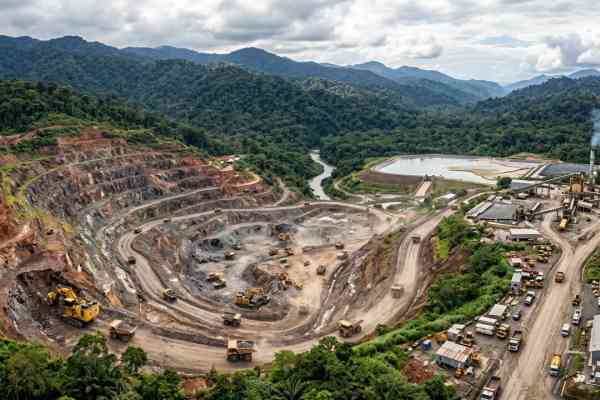
Power Metallic Mines' stock has gained about 23% over the past six months. Analysts and the CEO believe there is much more potential. A look at the copper market reinforces these assessments. Power Metallic Mines is developing one of the world's most exciting polymetallic exploration projects in Québec, Canada. The high-grade Nisk, Lion, and Tiger areas contain, among other things, copper, nickel, and platinum and palladium mineralization.
A recent milestone was reached with the resource estimate for the Lion Zone of the Nisk project. In an interview with Lyndsay Malchuk of the IIF, CEO Terry Lynch explained that this resource comprises 4.75 million metric tons with an average copper equivalent grade of approximately 3.9%. About 87% is classified as "indicated" and is therefore geologically well supported. About 59% of the resource is located within the area delineated for potential open-pit mining. According to Lynch, the near-surface location and high metal grades could enable a cost-effective start to production.
The CEO sees significant expansion potential through ongoing drilling. The resource estimate only takes into account results up to April 19 and extends to a depth of approximately 610 m. Meanwhile, massive sulphides have been encountered at around 900 m; the corresponding assay results were still pending at the time of the interview. Drilling is expected to reach 1,200 m by the end of November. In addition, the company plans to target ore bodies that have not yet been adequately explored. Lynch considers an increase to approximately 10 million metric tons possible, but this must be substantiated through further exploration. A preliminary economic assessment (PEA) is planned for the first half of 2027 to evaluate the project's economic viability.
Lynch paints an extremely positive picture of the copper market. In addition to AI infrastructure, he sees robotics in particular as a previously underestimated driver of future metal demand. For years, he notes, too little capital has flowed into exploration, while new discoveries have become increasingly expensive. Consequently, the pipeline of sufficiently advanced mining projects is quite thin. Added to this are protracted development processes and resistance to new mining projects, which could block even economically attractive deposits for years. Consequently, the gap between copper demand and available supply could widen significantly starting in 2027. The result would be rising prices.
Lynch also believes the commodities boom has not yet run its course on the stock market. In his assessment, it has primarily been specialized mining investors who have built positions so far, while more broadly diversified investors are only gradually taking notice of the sector. Stronger capital inflows from these investors could further boost the stock. In the case of Power Metallic, he already considers a significantly higher valuation to be justified based on the discoveries made to date. Analysts at GBC Research share this assessment. Their price target for Power Metallic Mines is CAD 3. The stock is currently trading at CAD 1.25. The planned Nasdaq listing could become a key driver for the share price. This is expected to improve access to US investors and facilitate financing.
https://youtu.be/UROPYAq3umM?si=ttpVBn4yio__GTWb
Nordex: News Flow Provides Tailwind
Nordex's stock has lost nearly 20% of its value from its yearly high. Nevertheless, it is trading 39% higher than at the start of the year. The recent price weakness should therefore not be overemphasized, even though analysts at mwb research, for example, have criticized the high valuation. In their view, a surprisingly strong US business performance is needed to drive further price gains.
In any case, the positive news flow at Nordex continues. Most recently, the wind turbine manufacturer unveiled a new large-scale turbine. The company has expanded its Delta4000 series to include the N193/7.X wind turbine, designed for sites with low to moderate wind speeds. The turbine has a capacity of 7.3 MW and a rotor diameter of 193 m. According to the company, it enables up to 14% higher energy yield than the N175/6.X at typical low- to medium-wind sites. In Germany, it will initially be offered with a maximum capacity of 6.6 MW to align project economic viability with permit and grid-connection requirements. Series production is scheduled to begin in 2029.
In its development, Nordex is relying on key components from its existing platform, including the nacelle, control system, and electrical architecture. This is intended to enable a rapid market launch and leverage proven production and installation processes. Different operating modes, tower variants, and hub heights allow for adaptation to local regulations and operator objectives, such as noise emissions, energy yield, and service life.
In addition, Nordex has received an order for 91 MW from TEUT Energieprojekte, along with a 20-year service contract. For the Schönermark-Passow wind farm near Schwedt/Oder in Brandenburg, the company is supplying 13 N163/6.X turbines with a hub height of 164 m. Construction, delivery, and installation are scheduled to begin in September 2027, with the first turbine set to go into operation in January 2028. TEUT is developing the wind farm in partnership with the Austrian energy provider Salzburg AG. This marks the developer's tenth joint project with Nordex.
Hensoldt: Potential for Further Setbacks?
So far this year, investors have made money on Hensoldt stock only through trading. The stock is currently trading at EUR 77, which is the same level as in early 2026. According to analysts at mwb research, this is significantly overvalued. They estimate Hensoldt's fair value at EUR 62 and recommend "Sell".
In particular, the analysts question the valuation premium relative to defence companies more closely associated with armoured vehicles, such as Renk. According to their analysis, the share of vehicle-related orders in total order intake will rise from approximately 12% in 2023 to over 25% in 2025 and is expected to exceed approximately 32% in 2026. The optronics business stands to benefit most from this. Since about half of the orders cannot be clearly categorized, these figures may still underestimate the actual distribution.
Nevertheless, mwb expects Hensoldt to achieve strong growth through 2028. Revenue is expected to rise from EUR 2.82 billion in the current year to EUR 3.22 billion in 2027 and EUR 3.77 billion in 2028. For EBITDA, analysts forecast an increase from EUR 546 million to EUR 764 million over these three years. Net income is expected to climb from EUR 209 million in 2026 to EUR 257 million in 2027 and EUR 344 million in 2028. This would mean earnings would grow significantly faster than revenue.
The skepticism primarily concerns the period following the current procurement boom. mwb sees indications of a shift in German defence spending starting in 2029 and projects a decline following a revenue peak in the early 2030s. Even the high-performance radar systems would, after delivery, generate too little recurring revenue to sustain the high level over the long term. While the analysts at Hensoldt acknowledge that Hensoldt has good prospects for building a digitally networked battlefield, the estimated potential for recurring software revenue of EUR 500 million annually is not sufficient in their model to offset the expected decline.
It is, of course, not unusual for a CEO to see upside potential in their own company's stock. However, there is more to support the case that Power Metallic Mines is currently undervalued and therefore presents a buying opportunity. The resource estimate was convincing, and the project still appears to have significant additional potential. At the same time, copper prices are in rally mode, and the underlying drivers are likely to remain in place. Buying Hensoldt shares does not currently appear particularly compelling. The entire sector is struggling. Nordex, meanwhile, is certainly not cheap, but the news flow remains positive.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.