November 5th, 2026 | 05:35 CET
Power Shift in the US! Why Bayer Is Booming, TeamViewer Is Plunging and Almonty Industries Could Be on the Verge of a Major Rally!
Power shift in Washington! The Democrats have recaptured the Senate in the US midterm elections and probably the House of Representatives too. For Donald Trump, this means sharing power for the rest of his term, as legislation, taxes and indirectly tariffs will no longer pass quite so easily without the Democrats. The question for the stock market now is whether investors see the setback for the Trump agenda as a threat or a relief. Sectors that depend on regulation, government spending and trade policy in particular could now see greater volatility. Developments in international financial markets are coming thick and fast these days! While Bayer is sending a strong signal with surprisingly strong quarterly results and raised full-year targets, software provider TeamViewer is causing alarm in the SDAX with a sharp slump and a lowered outlook. Meanwhile, an exciting story looks set to unfold in the tungsten sector with Almonty. Following a rapid rise, the shares are undergoing a strong and intense consolidation, which savvy investors could nevertheless see as a rare and attractive buying opportunity. Find out below which stocks have genuine recovery potential following the latest news, where the potential risks lie in detail and how best to position your portfolio for the coming weeks and months. A look behind the scenes suggests markets may be undergoing a complete reassessment right now.
time to read: 4 minutes | Author: Matthias Schomber
ISIN: Almonty Industries Inc | CA0203987072 , BAYER AG NA | DE000BAY0017 , TEAMVIEWER AG INH | DE000A2YN900
Table of contents:
Author
Matthias Schomber
Raised in Giessen, Hesse, Matthias Schomber discovered his passion for the financial markets as early as the 1990s—at a time when stock trading was still largely the domain of true, die-hard traders. After completing his banking apprenticeship, he worked for a private bank there and witnessed the rise and fall of the Neuer Markt firsthand on the trading floor of the Frankfurt Stock Exchange, drawing lessons from the experience that continue to shape his thinking as a trader, author, and trading system developer to this day.
Tag cloud
Shares cloud
Bayer: Pharmaceuticals division fires up the turbo and leaves legacy burdens (partly) behind
The Leverkusen-based company spent years under heavy stock market fire over litigation tied to the weedkiller that came with the Monsanto takeover, but now the DAX group is making a comeback with a genuine breakthrough. The long-awaited operational turning point in the pharmaceuticals segment is finally here. CEO Bill Anderson is driving the internal transformation forward with palpable determination and proving to market participants that the long-established company has far more substance than its share price has shown in recent years.
In the third quarter just ended, group revenue climbed 4.1% to EUR 10.05 billion, while adjusted EBITDA rose 6.9% to EUR 1.62 billion, exceeding average analyst estimates. The pharmaceuticals division drove this performance, with adjusted EBITDA surging almost 24% thanks to strong growth in the modern blockbusters Nubeqa and Kerendia. Although impairments and ongoing legal costs continue to weigh on unadjusted group earnings, operating profitability in the core business recently delivered a positive surprise. This prompted management to raise its full-year forecast for adjusted EBITDA to EUR 9.8 to 10.3 billion.
With an improved EBITDA margin of 25 to 27% in the pharmaceuticals division and falling net debt, the balance sheet is in a significantly stronger position than a few months ago. Despite technical hurdles – the price would need to make a sustained breakout above EUR 54 - and the still-simmering glyphosate issue, the share offers an exciting risk-reward profile at a price of around EUR 52.20 and a moderate valuation. Investors looking to buy in here could be rewarded, provided a sustainable turnaround succeeds. This could gain further momentum in the coming quarters through pharmaceutical successes and gradual legal relief.
TeamViewer: Share price shock and slashed outlook
TeamViewer was once a celebrated pandemic winner. The Göppingen-based remote support specialist is now battling significant headwinds and, after this week's heavy blow, has likely left shareholders deeply disappointed. A dramatic share price plunge of over 25% in just one trading day has wiped out months of hard-fought recovery attempts in one fell swoop. When even solid operating margins and the expansion of new niche products can no longer reassure investors, confidence is pretty much shot.
In the third quarter, revenue fell 3.9% to EUR 184.5 million, equivalent to a 2.2% decline at constant currency. Delayed contract signings with large corporate customers in the Enterprise division, in particular, along with a noticeable reluctance to invest in Europe, forced management to lower its forecast. Instead of the slight growth previously targeted, the group now expects a full-year revenue decline at constant currency of 1% to 2% against the pro forma figure. Although the company is maintaining its adjusted EBITDA margin of around 43%, the loss of growth momentum is prompting shareholders to flee the stock, as is immediately apparent from the share price.
Following its sharp plunge to around EUR 5.20, the share is badly damaged from a technical perspective and now risks entering a new downward spiral. Without a swift and reliable return to solid growth rates in the Enterprise business, the share remains a high-risk bet for speculative market participants for now. For investors, this likely means staying on the sidelines until management provides concrete proof that the postponed major orders can be secured in the near term. Buying now could be the proverbial "catching a falling knife".
Almonty Industries: Historic mine launch and poised for the next rebound
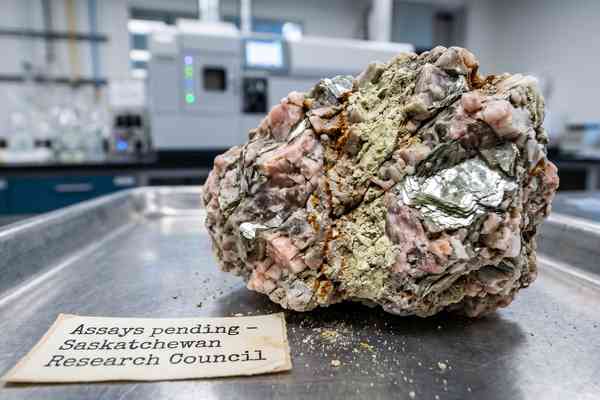
Amid the shadow of wars and commodity crises, Almonty is currently making genuine industrial history on a global scale. After more than three decades of silence, high-grade tungsten is finally flowing again from Sangdong in South Korea, helping to meet the urgent needs of Western supply chains. Through his unwavering entrepreneurial discipline, CEO Lewis Black is demonstrating that building independent supply chains for high-tech industries and strengthening defence readiness are no longer distant aspirations, but a clear reality.
Almonty Industries shares are currently in a sharp, nerve-racking consolidation phase for existing shareholders, following a strong rally that took the stock from just under USD 11.00 to an interim high of around USD 19.50. Although the share price has continued to decline since the sharp pullback began in September, the correction could lose momentum in the coming days, as substantial horizontal support sits around USD 8.00. The operational foundation is relatively solid, supported by the successful start of commercial operations at Sangdong, long-term offtake agreements and robust project safeguards. The shares are currently trading around USD 8.70 and are awaiting a decisive catalyst to trigger a reversal.
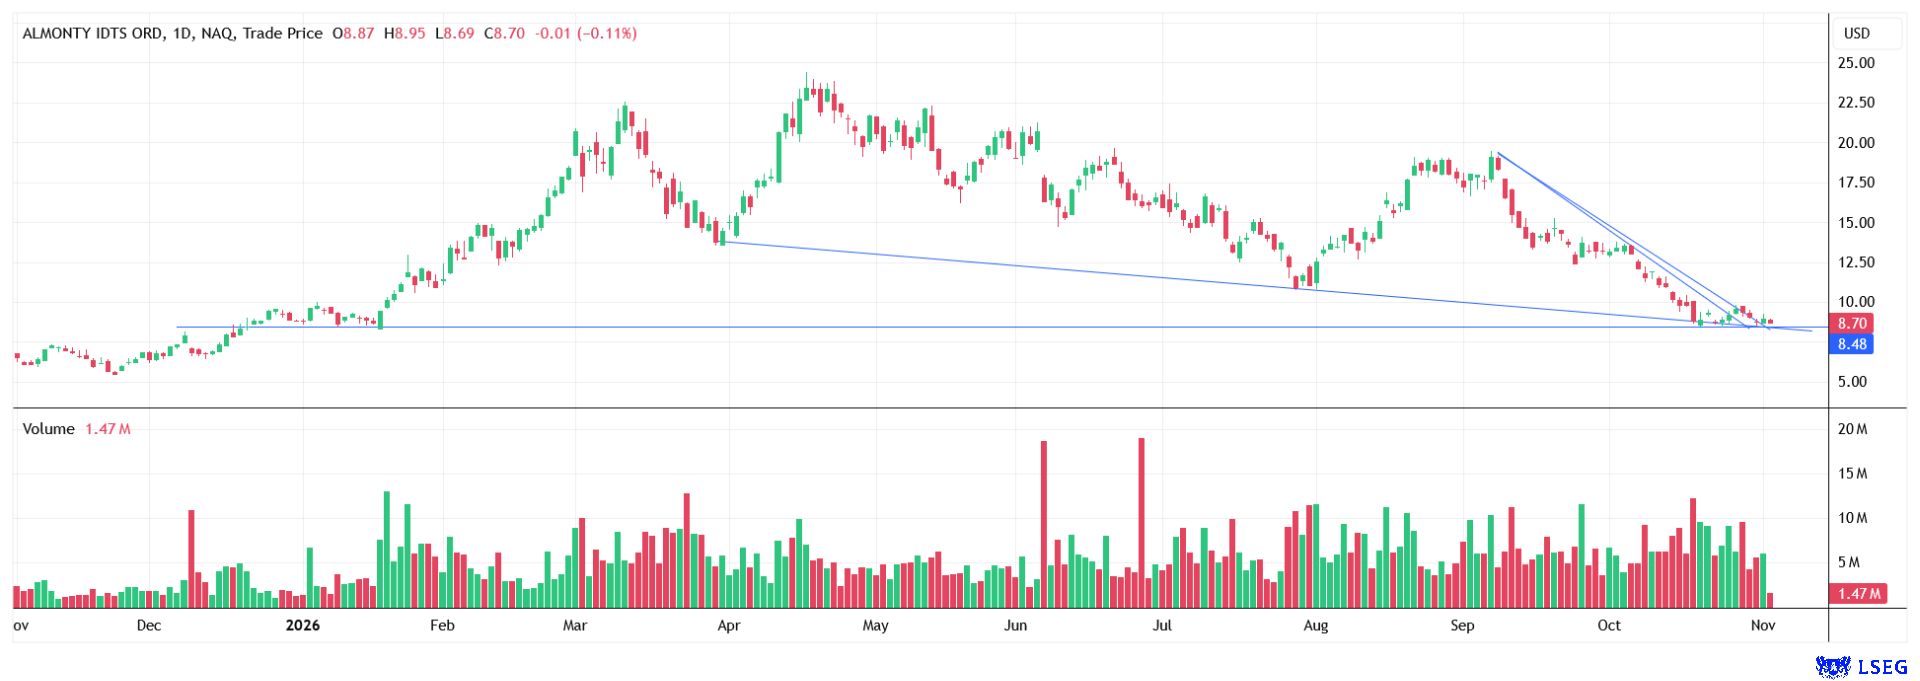
A technical rebound could now give the share fresh momentum and take it straight to the open gap at around USD 12.90 as its first important target. If a sustained upward breakout succeeds there, the price could move fairly quickly towards USD 15.00 to 16.00, while the broader chart picture even points to potential upside to USD 19.00 or 20.00.
Almonty Industries has become a little more attractive in valuation terms even after the decline, or precisely because of it. The company is now, more than ever, an exciting, strategically well-positioned commodities play. Overall, it appears well placed and now also offers the attraction of a technical rebound.
Conclusion
Bayer impresses with raised targets following operational progress in its pharmaceutical segment and may be on the verge of a sustained turnaround. TeamViewer, meanwhile, first needs to find a floor after significant forecast cuts and disappointing major customer deals. Almonty Industries presents itself as a strategically important, or rather indispensable, tungsten specialist in a currently lucrative consolidation phase with rebound potential.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.