July 13th, 2026 | 07:45 CEST
HOT AIR AND HARD FACTS: WHAT SETS SPACEX APART FROM ALMONTY AND THYSSENKRUPP
USD 2 trillion for dreams of Mars? While SpaceX is valued on expectations of its long-term growth and ambitious space exploration plans, Almonty Industries supplies tungsten—and soon molybdenum—critical raw materials used in a wide range of high-performance industrial and aerospace applications. These metals are also important for manufacturers such as thyssenkrupp, the long-established industrial group from Essen that is currently undergoing a major transformation. This analysis compares one company valued largely on future expectations with two businesses positioned at the heart of real-world industrial supply chains.
time to read: 5 minutes | Author: Jens Castner
ISIN: ALMONTY INDUSTRIES INC. | CA0203987072 | TSX: AII , NASDAQ: ALM , ASX: AII , SPACE EXPLORATION TECHNOLOGIES CORP | US84615Q1031 | NASDAQ: SPCX , THYSSENKRUPP AG O.N. | DE0007500001
Table of contents:
Author
Jens Castner
The Nuremberg native brings over three decades of capital markets experience, backed by a career shaped by deep market insight and a genuine passion for investing. His journey began in 1994 through an investment club among colleagues – a formative experience that sparked a lifelong dedication to identifying compelling investment opportunities.
Following senior editorial roles at Nürnberger Nachrichten, €uro am Sonntag, and €uro, he went on to serve as Editor-in-Chief of the renowned investor magazine Börse Online from 2014, where he played a key role in shaping high-quality financial journalism for a broad investor audience.
Tag cloud
Shares cloud
SpaceX: Strong Words from a Stock Market Expert
In the latest monthly report from the Frankfurt-based fund management firm Acatis, the firm's founder, Dr. Hendrik Leber, uses unusually harsh language to describe SpaceX's initial public offering. His assessment: Rarely has an IPO prospectus contained so much "hot air". And especially when this hot air sells well to retail investors, it is a warning sign of an impending market shift. Leber draws historical parallels to speculative excesses such as John Law's Mississippi Company in Louisiana, which drove the French state to the brink of ruin, and other episodes in which fantasies of immeasurable wealth in distant worlds ended in disaster. Now, according to Leber, investors are being promised riches on Mars.
He also offers a very specific assessment of the company's valuation: in his view, SpaceX is not purely a pipe dream. Its Falcon rockets and Starlink satellite network have established the US company as a dominant force in the commercial space industry. However, he argues that the company's market capitalization of around USD 2 trillion is not primarily based on these existing businesses, but rather on what he describes as an "almost mythical treasure hunt"—expectations surrounding asteroid mining and the colonization of Mars. According to Leber, such mega-IPOs have historically often marked the peak of a market bubble, as insiders become increasingly inclined to cash out at astronomical valuations and distribute their shares to the public. His conclusion: disappointment is almost inevitable. His team prefers to stay grounded and steer clear of what it sees as overly speculative space-related narratives.
After a brief spike above USD 200, SpaceX's share price has since settled near its initial listing price of USD 150—yet the company is still "light-years away" from a reasonable valuation. If well-intentioned studies prove correct, Elon Musk's space project could indeed break even next year. However, with a valuation of more than 25 times annual revenue and a price-to-earnings (P/E) ratio of about 200, it remains well outside the stratosphere.
Almonty: Heavenly Prospects on Earth
A much more down-to-earth company, one without which SpaceX could not even exist, is Almonty Industries. The Canadian-founded company is on its way to becoming the leading Western supplier of tungsten, a metal indispensable not only for the defense industry in armour and ammunition, but also for the civilian aerospace sector, where it is used in engines and structural components for its extreme hardness and heat resistance. Without tungsten suppliers like Almonty, the rockets on which SpaceX's business model is based simply would not exist. Here, the valuation leaves significantly more room to grow than in the case of the "Star Explorer". Based on consensus estimates, the 2027 P/E ratio stands at 11.5, given a current share price of about USD 16.50 (around EUR 14.50 in Germany), and is thus by no means at an out-of-this-world level.
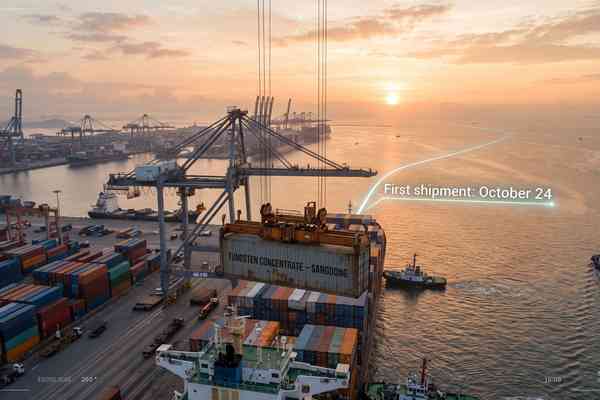
Following its recent relocation to the US state of Montana to be closer to potential customers in the American industry and a local tungsten project, Almonty reached another crucial milestone in early July: at the Sangdong Mine in South Korea's Gangwon Province, the plant that processes ore into marketable tungsten concentrate is now coming online. According to the company, the ore stockpile of approximately 139,700 metric tons already on site corresponds to an illustrative gross value of about USD 68 million. Sangdong, historically one of the world's largest and highest-grade tungsten deposits, is thus transitioning from the development phase to the production phase—at a time of historically high tungsten prices and Western efforts to become independent of Chinese supply chains.
But Almonty has its sights set on a second raw material: molybdenum. A large-scale drilling program is underway at the neighbouring Sangdong Molybdenum Project, confirming historical resource estimates of high-grade deposits. All molybdenum production from Sangdong has already been contracted under a purchase agreement to SeAH M&S, the world's second-largest molybdenum oxide smelter, which is in turn investing in Texas to directly supply the aerospace industry, including SpaceX, and the US defense sector with specialty alloys. Together with a planned tungsten oxide plant, this is set to create what Almonty calls the "Korean Trinity": an integrated value chain for two strategic metals.
thyssenkrupp: From Problem Child to Lean Holding Company
Molybdenum is indispensable for the production of high-quality flat steel for the automotive industry. Above all, it increases the corrosion and acid resistance of the alloys, which is why thyssenkrupp is also becoming a potential customer of Almonty. As part of its transition to sustainable supply chains, the long-established Essen-based conglomerate is gradually removing molybdenum from countries with critical environmental or social standards from its portfolio, while expanding long-term contracts with ESG-compliant producers, primarily in North and South America as well as South Korea. The name SeAH M&S comes up repeatedly in this context; the company has secured Almonty's entire molybdenum production at Sangdong.
Since the sale of its stainless steel plants, tungsten has played only a minor role for the MDAX-listed company, but it remains a focus for the materials trading division TK Accelis (formerly thyssenkrupp Materials Services). Following the spin-off of the hydrogen subsidiary thyssenkrupp Nucera in 2023 and the initial public offering (IPO) of the marine division TKMS last fall, TK Accelis is now also set to be spun off. Shareholders are therefore invited to an extraordinary general meeting on August 7. If the green light is given there, the IPO is set to take place before the end of this year—the next step in transforming the once-cumbersome conglomerate into a lean holding company modeled after Siemens.
The stock market is responding positively to these plans. In less than two years, thyssenkrupp's stock has risen from a historic low of under EUR 2.00 to EUR 11.70 most recently. With an estimated 2027 P/E ratio of 10.7, its valuation is the lowest among the trio, though there are reasons for this. The automotive supplier division, Automotive Technology, known, among other things, for steering and suspension systems, needs to be restructured urgently before a spin-off can be considered. The second major challenge is the Duisburg steel mill, which is facing a billion-euro investment for the conversion to green hydrogen and is currently suffering from high energy costs. Previously, a joint venture with the EP Group, owned by Czech billionaire Daniel Křetínský, was under consideration for this purpose; however, the investor withdrew from the talks in October 2025. Only once these problems are resolved is the stock market likely to assign thyssenkrupp shares a significantly higher valuation again.
Of Alien Worlds and Real Price Prospects
SpaceX's valuation is fueled by a treasure hunt in alien worlds, not by real fundamentals. Almonty and thyssenkrupp represent the opposite: real raw materials, real industrial demand, real supply chains—for defense, civil aviation, and high-quality steel production. Both stocks are undervalued, though Almonty currently has the better chance of rebounding quickly, as positive news is being released one after another. thyssenkrupp is particularly interesting for investors with a long-term perspective.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.