October 27th, 2026 | 05:38 CET
Environmental Liabilities as a Goldmine: Zefiro Methane Builds a Strong Order Book, Analysts See 200% Upside
Created and published on behalf of Zefiro Methane Corp.
Investors subscribing to new share issues normally expect a discount. At Zefiro Methane, however, investors were willing to pay more than the stock's market price. The market promptly responded to this vote of confidence by pushing the share price higher. The order books of the Canadian specialist in remediating environmentally hazardous oil and gas wells are filled through 2029, and its price-to-earnings (P/E) ratio stands at around 11. GBC Research analysts see more than 200% upside potential.
time to read: 5 minutes | Author: Jens Castner
ISIN: Zefiro Methane Corp | CA98926D1069
Table of contents:
Author
Jens Castner
The Nuremberg native brings over three decades of capital markets experience, backed by a career shaped by deep market insight and a genuine passion for investing. His journey began in 1994 through an investment club among colleagues – a formative experience that sparked a lifelong dedication to identifying compelling investment opportunities.
Following senior editorial roles at Nürnberger Nachrichten, €uro am Sonntag, and €uro, he went on to serve as Editor-in-Chief of the renowned investor magazine Börse Online from 2014, where he played a key role in shaping high-quality financial journalism for a broad investor audience.
Tag cloud
Shares cloud
Paying a premium as a vote of confidence
Capital increases at smaller companies usually follow the same pattern. New shares are offered at a discount to the market price, which usually falls ahead of the capital raise. At Zefiro Methane, it was the other way round. Last Friday, the specialist in plugging orphaned oil and gas wells announced the completion of a private placement worth around CAD 5.0 million. Just over 7.5 million units were issued at CAD 0.66 each. On the stock market, the share price was at times below CAD 0.60 at the time of the capital increase. Investors therefore paid a premium of around 10%. However, each share came with half a warrant, entitling holders to buy a further share at CAD 0.80 within 30 months. The market viewed the transaction as a vote of confidence: on Monday, the share price rose to CAD 0.64.
The fresh funds will go into ongoing operations, with some potentially used for acquisitions. In May, Zefiro acquired equipment from drilling services provider Viking Well Service for USD 4.3 million. According to the company, five additional drilling rigs increase annual revenue capacity by around USD 10 million. CEO Catherine Flax had already indicated at a September investor meeting in Munich that further acquisitions could follow. The reason is simple: Demand is growing faster than the company's own capacity.
Vast amounts of legacy contamination in the ground
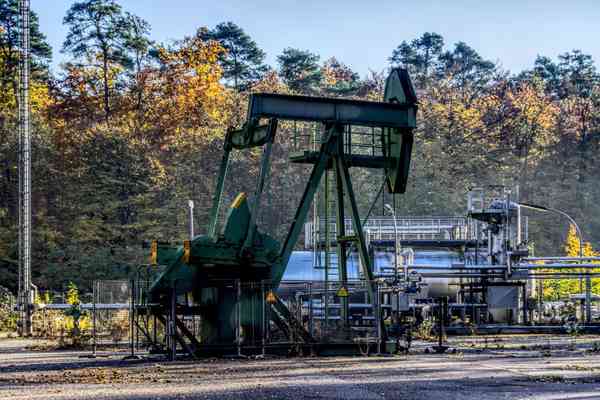
The business model addresses a problem the US has long ignored. More than 2 million orphaned oil and gas wells were never properly plugged – and that is a conservative estimate. Zefiro CEO Flax believes there could even be as many as 3 million. The former operators are often bankrupt or untraceable. Many of these wells leak methane, a gas about 80 times as damaging to the climate as CO₂ over a 20-year period. Washington allocated USD 4.7 billion for remediation, but that is just a drop in the ocean. The think tank Carbon Tracker estimates the total cost at around USD 280 billion.
New demand is coming from the construction of data centres for artificial intelligence (AI). If excavators encounter an abandoned well, work stops until the legacy hazard is secured. With investments running into billions, every day's delay costs real money. Anyone with crews readily available and suitable equipment then has an advantage. That is precisely what the industry lacks: specialist providers are rare, and drilling rigs and skilled workers are scarce. Prices per well have therefore risen significantly in recent years.
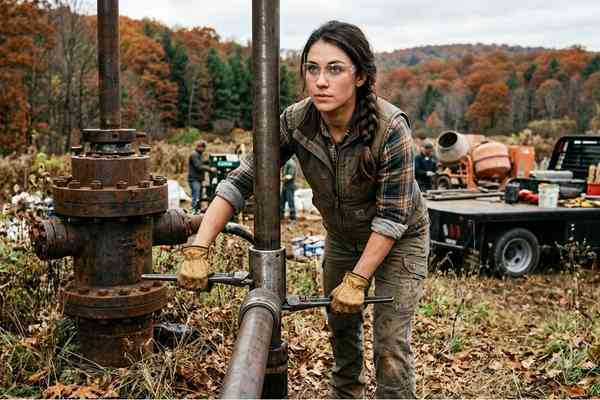
Zefiro is well positioned for this market. The Canadian company's operating arm is its subsidiary, Plants & Goodwin, a drilling services provider based in Pennsylvania, with more than 50 years of experience. With 25 drilling rigs and around 150 skilled workers, Plants & Goodwin operates in 15 US states. Its services range from methane measurement and cement plugging to site remediation. Added to this is the sale of carbon credits, certificates for each tonne of greenhouse gas emissions avoided. Zefiro has already sold credits for around 93,000 tonnes of CO₂ equivalent, including to commodities trader Mercuria. Hardly any other provider covers the life cycle of a well so comprehensively.
Orders through mid-2029
The order book shows how much demand there is for these services. Zefiro has around USD 40 million from government-funded projects alone, due for completion by June 2029. The largest item is a three-year contract worth USD 19.6 million for around 200 wells in Ohio. In addition, there is an order worth USD 11.5 million from the Great Lakes region. About USD 4.9 million is due for completion by the end of December. The USD 40 million does not include orders from oil and gas producers, which are usually awarded at short notice. Also new is an exploration contract in Ohio, under which wells are examined before being plugged. "It brings Zefiro into an earlier phase of the remediation process, using the same teams we deploy every day", explains CEO Flax. Her colleague Luke Plants, responsible for corporate development, emphasises the predictability this provides: "Knowing where our drilling rigs and crews will be deployed through mid-2029 allows us to plan projects efficiently".
High-profile projects also strengthen the company's reputation. In Ohio's Cuyahoga Valley National Park, Plants & Goodwin has already completed its second contract. In US national parks alone, an estimated 1,800 wells emit the climate-killing gas. To learn more about the environmental problem of orphan wells and Zefiro's business model, watch the documentary "The Hazard Below".
Operationally, Zefiro has long since achieved a turnaround. In the 2025/26 financial year ended in late June, revenue rose 31% to USD 42.5 million. Adjusted operating earnings before interest, taxes, depreciation and amortisation (EBITDA) swung from minus USD 4.0 million to plus USD 3.8 million. For the current financial year, management is targeting revenue of more than USD 50 million, while GBC Research forecasts as much as USD 57.9 million. The Augsburg-based analysts estimate earnings per share at USD 0.04. This equates to an attractive price-to-earnings (P/E) ratio of around 11. Their price target is USD 1.50, currently about CAD 2.11. That is more than three times the current share price.
Plenty of upside potential
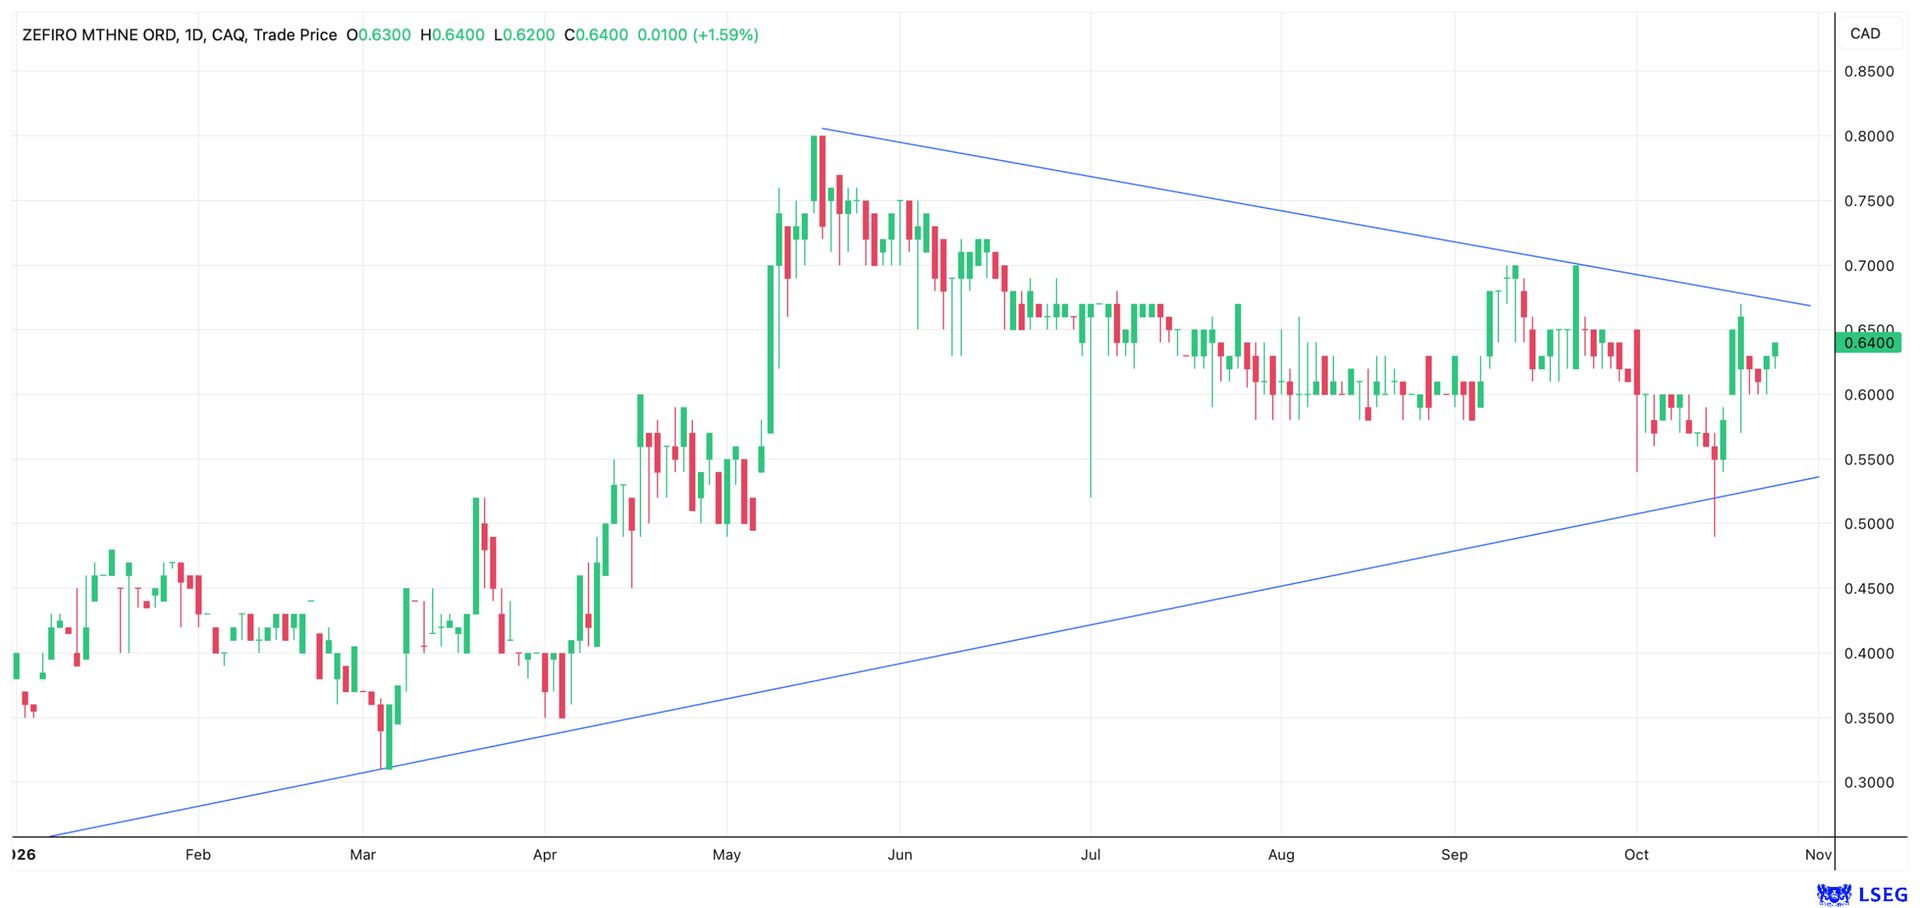
Despite the recent recovery, the share price remains well below its annual high of CAD 0.80 reached in May. Figures for the first financial quarter will follow in mid-November. However, Zefiro gaining further market share and becoming better known on the stock market is likely to be more important for the share price. Investors who participated in the capital increase have already signalled their confidence by paying a premium. The technical chart indicators suggest that their decision may prove justified.
A 100% rally between early April and mid-May was followed by an extended consolidation phase. In mid-October, even the long-term uptrend briefly threatened to break down, but it held. With fresh support from new investors, the share is now well on its way to leaving behind the medium-term downtrend established since the May high, which currently runs at around CAD 0.67. If it breaks above this level, at least the annual high of CAD 0.80 should be within reach again, and the warrants issued as part of the private placement would then also move into the money. On German trading venues, Zefiro shares currently cost around EUR 0.40. If GBC Research's price target proves correct, gains of more than 200% are possible.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.