October 26th, 2026 | 05:29 CET
Share prices are falling, business is growing: What opportunities do Almonty, Rheinmetall and Renk shares offer investors?
The euphoria has apparently faded. Following sharp share price declines, Almonty, Rheinmetall and Renk are increasingly back in focus. With demand trends intact, are these new entry opportunities? After all, without raw materials there is no ammunition; without drive systems there are no mobile armed forces. Almonty has commenced commercial operations at the Sangdong tungsten mine, marking a historic milestone. Rheinmetall and Renk are under scrutiny for how quickly and profitably they can fulfil orders. Wait or buy?
time to read: 3 minutes | Author: Carsten Mainitz
ISIN: Almonty Industries Inc | CA0203987072 , RHEINMETALL AG | DE0007030009 , RENK AG | DE000RENK730
Table of contents:
Author
Carsten Mainitz
The native Rhineland-Palatinate has been a passionate market participant for more than 25 years. After studying business administration in Mannheim, he worked as a journalist, in equity sales and many years in equity research.
Tag cloud
Shares cloud
Almonty: Historic milestone reached
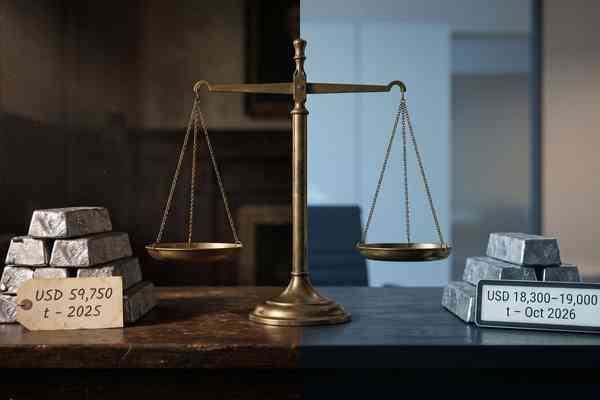
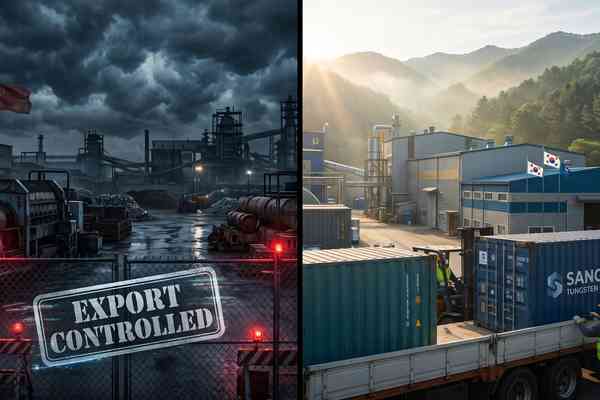
The company is marking a decisive milestone with its first commercial tungsten shipment from the Sangdong mine in South Korea. This ends a production hiatus of more than 30 years. Almonty sells tungsten as a critical raw material in concentrate form, which is further processed and used in carbide tools, electronics and military applications, among other things. Alongside price, customers value a reliable source.
In parallel, Almonty is driving the second expansion stage forward and expects to complete Phase II in 2027. Processing capacity is set to rise to up to 1.2 million tonnes of ore annually, equivalent to around 40% of global tungsten demand outside China. A contract with Global Tungsten & Powders, a Plansee Group company, which runs for 21 years following the latest amendment, makes sales more predictable. According to the company, the contract covers more than 90% of Phase I production.
In addition to mining, Almonty plans a facility to process tungsten concentrate into ammonium paratungstate and tungsten oxide. These intermediate products are needed by industrial customers. In management's assessment, the bottleneck in the West lies not only in extraction, but increasingly also in available processing capacity. Construction is targeted to begin in 2027.
At the half-year, liquidity totalled around CAD 1.2 billion. A key source was an USD 800 million convertible senior notes offering, carrying interest of 2.25% and maturing in 2031. The funds were initially used to repay expensive loans and buy back shares. The shares are currently trading at USD 8.85, meaning the stock has surrendered all its gains since the start of the year. The market capitalisation stands at USD 2.55 billion. Bank of America analysts most recently set a price target of USD 24, signalling substantial upside potential.
Rheinmetall: Outlook in focus
Rheinmetall is expanding its defence business to include satellite-based reconnaissance. Series production of SAR satellites, manufactured jointly with Finnish partner Iceye, recently began at the Neuss site. The company plans around 50 satellites per year, with the first launch scheduled for early 2027. Strategically, this opens up an attractive growth area for Rheinmetall with long-term potential in military reconnaissance and networked combat systems.
The shares have been under pressure for some time and are currently trading at around EUR 1,000. Experts at major Swiss bank UBS recently lowered the price target from EUR 1,600 to EUR 1,360. With the group's Capital Markets Day on November 26 and 27, analysts expect Rheinmetall to set more conservative targets.
In the first half of 2026, revenue grew 39% to EUR 5.23 billion, while operating profit rose much more sharply, 74% to EUR 786 million. The operating margin reached 15%. Following the decision on the F126 frigate programme, Rheinmetall reduced its revenue expectations by EUR 300 million. The group now expects annual revenue of EUR 13.7 to 14.2 billion and an operating margin of around 19%. The quarterly report on November 5 provides the next test. Further project delays or weak cash flow could lead to disappointment.
Renk: Focus is progressing
The group is selling its civilian plain bearing business to Austria's Miba AG. The purchase price is in the low- to mid-hundreds of millions of euros. Completion remains subject to regulatory approvals. For 2026, the specialist in transmissions and drive systems expects revenue of around EUR 1.4 billion and adjusted EBIT of EUR 240 to 255 million from continuing operations. A new order from KNDS worth around EUR 130 million provides additional support, covering, among other things, transmissions including control systems for the Leopard 2 tank and other vehicles. Delivery is planned for 2029 to 2032.
In the first half, order intake rose to around EUR 1.2 billion. Revenue rose by just 2.7% to EUR 637.2 million, while adjusted EBIT grew disproportionately by 10.1% to EUR 98.2 million. On November 5, the nine-month report must show whether the order situation and operational execution remain aligned. US bank JPMorgan recently lowered its price target from EUR 62 to EUR 50. The experts now expect a slower ramp-up of German armoured vehicle programmes and have reduced their earnings estimates for 2027 to 2030.
Conclusion
Almonty offers strong leverage to additional tungsten supplies and high prices. The Sangdong mine also carries geopolitical weight. Analysts believe the shares are significantly undervalued. With the upcoming Q3 results and the Capital Markets Day, investors should gain a clearer view of Rheinmetall's medium-term targets. Analysts are bullish on Renk, and they have priced in a slower production ramp-up and the associated scepticism.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.