July 21st, 2026 | 07:55 CEST
M&A in Financials: Is PayPal's 100% Upside Just the Beginning? What Comes Next for Allianz, Commerzbank, RE Royalties, and Munich Re?
Rising interest rates and excessive government borrowing. The financial sector is back in the spotlight. In response to public interest, the sector has been required for some time now to ensure compliance with ESG lending guidelines. After all, no one in the EU, and certainly not in the US, wants to see a banking scandal like the recent one involving Credit Suisse in Switzerland. As a result, the global financial sector is increasingly aligning itself with sustainability criteria. As a result, innovative ESG financing now accounts for around 30% of the strategic core allocation among leading industry players. The insurance group Allianz is playing a pioneering role in this regard by using blended finance structures through its fund subsidiary, AllianzGI, to channel private capital into green projects in emerging markets via a climate fund worth billions. Munich Re, the world's largest reinsurer, also relies on a strict, independent green bond framework to support a low-carbon economy. Payment service provider PayPal takes a different, strongly socially oriented approach to ESG, focusing on the social pillar and global financial inclusion. A takeover could be on the horizon here—one that has long been anticipated, even by the very affordable green finance specialist RE Royalties. We are digging even deeper!
time to read: 4 minutes | Author: André Will-Laudien
ISIN: RE ROYALTIES LTD | CA75527Q1081 | TSXV: RE , OTCQX: RROYF , ALLIANZ SE NA O.N. | DE0008404005 , PAYPAL HDGS INC.DL-_0001 | US70450Y1038 , COMMERZBANK AG | DE000CBK1001 , MUENCH.RUECKVERS.VNA O.N. | DE0008430026
Table of contents:
Author
André Will-Laudien
Born in Munich, he first studied economics and graduated in business administration at the Ludwig-Maximilians-University in 1995. As he was involved with the stock market at a very early stage, he now has more than 30 years of experience in the capital markets.
Tag cloud
Shares cloud
Allianz and Munich Re: Two Powerhouses from Bavaria
It is not just the ESG programs that are impressing shareholders of Allianz and Munich Re, the internationally better-known name for Münchener Rück, but also the core insurance and investment businesses. Both companies narrowly met their expectations in their core business areas in 2026, with Allianz even selectively exceeding them. In purely technical terms, Allianz's share price of EUR 425 in July even surpassed the very long-standing high set in 2000. At one point, the stock even fell below EUR 50 due to the 2008 financial crisis; since then, it has risen by 800%. Munich Re's share price has undergone a noticeable consolidation over the past 12 months and has lost about 8% of its value since the beginning of the year, after the stock had previously traded near its all-time high. A major drag was the increasing price pressure in the global reinsurance market, as prices softened noticeably during the most recent renewal rounds in the spring and summer. In addition, significant negative currency effects resulting from the temporarily weaker US dollar weighed on insurance revenues reported in euros. Despite an overall solid earnings picture, costs in the billions from severe natural disasters, such as the devastating wildfires in Los Angeles at the beginning of 2026, also weighed on the company. Currently, there are severe wildfires in Canada, which are raising further concerns among investors. Both companies are currently buying back shares in the amount of more than EUR 2 billion, so the price targets on the LSEG Refinitiv platform of EUR 418 and EUR 557, respectively, may not be so far-fetched. While Munich Re still has 7% upside potential, Allianz has already traded significantly higher. Due to their low volatility, both stocks are suitable for long-term portfolio stabilization.
RE Royalties: Will the energy transition financier become a takeover target?
From big to small! The energy transition is becoming one of the largest capital projects of the coming decades. To achieve climate neutrality by 2050, hundreds of billions must be mobilized annually in Europe alone. The key bottleneck is increasingly not technology, but financing. This is where RE Royalties comes in. The Canadian company finances developers of renewable energy projects but could itself become a takeover target as a result of its ongoing strategic review. RE Royalties has adapted a successful business model from the commodities sector to the energy transition. Instead of operating its own wind or solar farms, the company provides capital and receives long-term, revenue-based payments in return. The model combines recurring cash flows with the growth of solar energy, wind power, battery storage, hydropower, and biogas. The portfolio now includes more than 130 projects in several regions, including North America, Mexico, Chile, South Asia, and Puerto Rico.
According to the company, over CAD 80 million has been invested since its founding in 2016. The internal rate of return achieved to date exceeds 19%, and approximately 41% of revenue comes from existing customer relationships. Its niche positioning is particularly attractive. RE Royalties frequently finances projects in the range of CAD 10 to 20 million, a segment that is often too small for large banks or private equity investors but enables high returns for a specialist. The strategic review being conducted in collaboration with the auditing firm PwC is fueling speculation. Various options are being examined—ranging from strategic partnerships and co-investments to a potential sale of the company. A similar pattern emerged, for example, with Chevron Corporation's acquisition of the Renewable Energy Group in 2022, when a specialist in sustainable energy was acquired by a global energy conglomerate to accelerate its own transformation strategy.
The valuation also offers scope. RE Royalties most recently paid out CAD 0.04 per share, corresponding to a dividend yield of over 10%. At the same time, the project pipeline continues to grow. Approximately CAD 20 million in short-term investments are ready to go, and additional opportunities totaling about CAD 200 million are being evaluated. The combination of a double-digit dividend yield, a valuation of just CAD 17 million, and an expected significant transaction premium makes the stock an exciting niche play in the global energy transition market. Investors should therefore consider all possible scenarios!
COO Peter Leighton outlined his strategy for the current year at the 19th International Investment Forum.
PayPal: USD 53 billion still is not enough
Finally, we turn to PayPal, the former eBay subsidiary. After some back-and-forth, an improved takeover offer has now been submitted by competitor Stripe and private equity firm Advent. It amounts to USD 53 billion, or USD 60.50 per share. "Not enough!" exclaims CEO Enrique Lores, as he first wants to complete his recently launched restructuring program and anticipates a significantly higher market capitalization afterward. To financially back this massive transaction, the two major US banks, JPMorgan and Morgan Stanley, have already committed to a comprehensive credit facility totaling USD 50 billion. In addition to financial disagreements, however, a potential merger between the two industry giants, Stripe and PayPal, is likely to face massive antitrust hurdles due to their enormous global market power. Industry analysts share the CEO's view and point to PayPal's strong free cash flow, which is why the offer is viewed as insufficient by the market. Currently, the stock is trading at just under USD 57—a slight discount to the public offer. Extremely exciting!
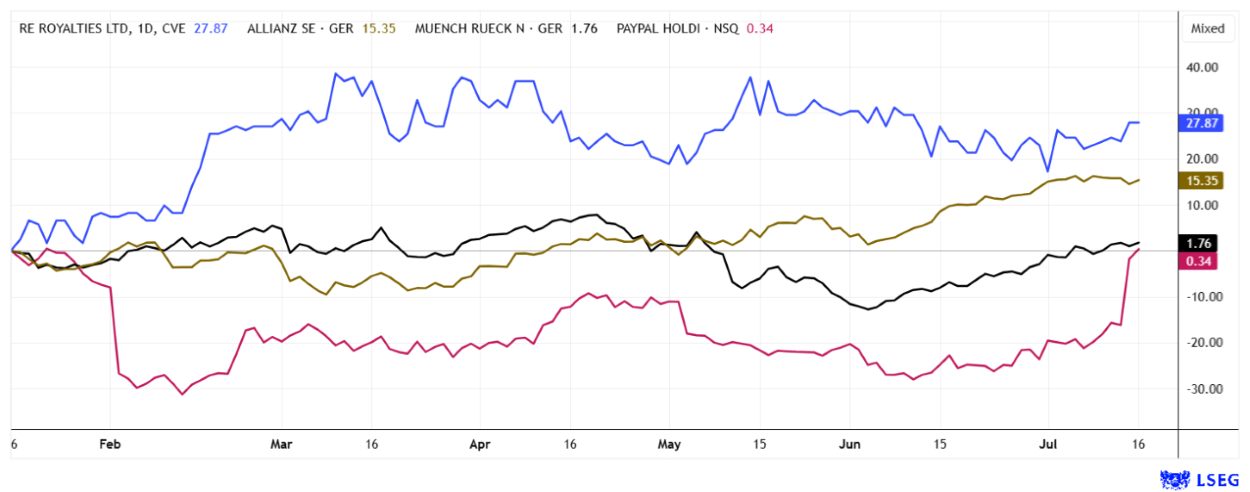
The M&A merry-go-round is picking up speed again. Now the spotlight is on the well-known PayPal, and Commerzbank will likely soon find itself under UniCredit's wing. What the financial sector no longer wants to see are upheavals like the one at Credit Suisse, which found a balance-sheet rescuer in UBS. Allianz and Munich Re are carrying on with "business as usual," and at RE Royalties, the suspicious silence could signal significant behind-the-scenes activity.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.