October 2nd, 2026 | 09:55 CEST
Heading South or Heading Higher? TUI and Lufthansa in a Fuel Crisis, RE Royalties and HelloFresh Under Scrutiny
Extremely high volatility — and almost every day. Iran threatens escalation, pushing oil prices higher, while Donald Trump publicly dreams of a quick peace deal, which could, in turn, push oil prices lower. Yesterday, however, Brent crude was trading at nearly USD 107 per barrel. Billions of dollars are being made in this back-and-forth by trading desks that operate largely outside the public eye, while questionable market activity is, of course, scrutinized mainly when it involves the average retail investor. The stock market has become a mirror reflecting just how much the world has changed. Autocratic rulers dictate the direction of attention and increasingly shape how societies interact. In the past, wars were waged over religious differences and territorial claims; today, economic interests clearly dominate, with everything else often serving as a pretext. After all, only countries close to the oil reserves have a direct interest in keeping oil prices high. Interestingly, over the past four years, the United States has risen to become the world's largest oil producer, ahead of Russia, Saudi Arabia, and Canada. Several stocks have significant exposure to these developments, particularly in the aviation and travel sectors. As always, the issue comes down to steadily rising costs. For speculative investors, some of the key players are worth a closer look.
time to read: 5 minutes
|
Author:
André Will-Laudien
ISIN:
RE ROYALTIES LTD | CA75527Q1081 | TSXV: RE , OTCQX: RROYF , LUFTHANSA AG VNA O.N. | DE0008232125 , TUI AG NA O.N. | DE000TUAG505 , HELLOFRESH SE INH O.N. | DE000A161408
Table of contents:
Author
André Will-Laudien
Born in Munich, he first studied economics and graduated in business administration at the Ludwig-Maximilians-University in 1995. As he was involved with the stock market at a very early stage, he now has more than 30 years of experience in the capital markets.
Tag cloud
Shares cloud
TUI and Lufthansa: Back and Forth in a Kerosene-Unfriendly Environment
The persistently weak performance of TUI and Lufthansa, with share prices down about 25% from their annual highs, stems mainly from major geopolitical tensions in the Middle East. These conflicts are forcing costly route diversions while simultaneously fueling concerns about an extreme oil price rally, which would drastically increase the companies' kerosene costs. In addition, TUI is facing a shift in consumer behaviour toward unpredictable last-minute bookings, typically at reduced prices and margins. At Lufthansa, previous costly strikes have caused significant financial damage in the hundreds of millions. Furthermore, the sector's capital-intensive nature is straining cash flows and causing the recently reduced net debt to rise again.
Among analysts, a very mixed picture is emerging for the two European tourism heavyweights. Optimism clearly prevails for TUI, as most experts consider the problems manageable. Major firms such as JPMorgan emphasize the company's operational resilience and set a price target of around EUR 9.54; the consensus on the LSEG Refinitiv platform, at EUR 9.81, is not nearly as low as one might expect given the difficult situation. This means that, in the best-case scenario, the stock of the European tourism market leader offers over 40% upside potential. At Deutsche Lufthansa, however, skepticism prevails due to ongoing margin pressure. Institutions such as Bernstein Research and JPMorgan primarily rate the airline group as "Hold" or "Sell". With 7 out of 23 "Buy" ratings, the average on LSEG still stands at EUR 9.74, leaving 28% upside potential here as well. The key factor driving both companies' medium-term performance should remain the travel budgets available to package tour travellers, as they must be able to afford the passed-on energy and crisis surcharges. However, given inflation rates of over 3%, some reservations are certainly warranted here.
HelloFresh: What Is Going On Here?
In high demand since its 2017 IPO at EUR 10.25 per share, HelloFresh's stock soared to over EUR 95 during the COVID-19 year of 2021. During the period of "social distancing" amid the pandemic, meal kits delivered to the doorstep were, of course, a real boon in the food industry. But then the decline began, resulting in a drop of about 97% from its peak to date. The situation is currently worsening further, as the former pandemic high-flyer is experiencing a dramatic and sustained loss of confidence in the capital markets. At the end of September, management issued a drastic profit warning, causing the stock to plummet to a new record low in the range of EUR 2.17. For the full year 2026, the company now forecasts a currency-adjusted revenue decline of 9 to 11% compared to the previous year. Adjusted EBITDA has also been significantly revised downward and is now expected to range between EUR 350 and 370 million.
The main cause of this massive drop in demand is the fact that the company is simply running out of new customers. In times of high inflation, consumers are cutting back on expensive food subscriptions and returning to traditional supermarkets for their weekly grocery shopping instead. To curb costs, HelloFresh previously slashed marketing spending, which further slowed new-subscriber acquisition. Analysts reacted harshly: Major firms like Deutsche Bank drastically lowered their price targets in response to the shrinking core business. Only 5 out of 16 analysts are still giving the platform a thumbs-up on the LSEG platform. Although the company is trying to turn things around, the stock remains an extremely risky turnaround candidate until its operations stabilize.
RE Royalties: How the Company Is Rocking the Green Energy Transition
Although the share price of this masterful financier of renewable energy projects has more than doubled since December 2025, the capital market has yet to really spotlight the RE Royalties story. Yet its "ESG-friendly business model" is certainly exciting. While the financial world keeps its eyes fixed on the industry giants, the Canadians are igniting the next stage of growth. The underlying concept is ingenious and cleverly borrowed from the commodities sector: The team provides developers of green energy projects with quick loans and, in return, secures a long-term stake in the electricity revenues. RE Royalties collects a share of the ongoing revenue for decades but is completely shielded from construction and operational risks. As soon as a loan is repaid, the money immediately goes toward the next project. This clever cycle has already catapulted the company past the magic mark of USD 100 million in financed projects.
Vice President Talia Becket speaks with IIF host Lyndsay Malchuk about the future of financing in the renewable energy sector.
The mega-deal with Solaris Energy demonstrates just how spectacularly this strategy can scale. Following a successful start with just under USD 5 million, a letter of intent is now on the table for a total volume of up to USD 67.5 million. With this, the company is not just buying into solar parks—it is securing access to a massive project pipeline of over 80 additional solar plants. The proceeds are partially secured for a quarter-century through minimum returns, which lends the entire venture a high degree of security. To optimally finance this growth spurt, management is working with PwC to explore strategic options ranging from co-investments to a full acquisition.
The current environment for such a business model could hardly be better, as the global demand for security of supply is driving the energy transition forward inexorably. Because government funding is far from sufficient, RE Royalties is closing a critical financing gap with private capital. It is bringing to fruition medium-sized projects that are too specialized for banks and too small for large investors. The visible impact ranges from solar installations at luxury resorts in Mexico to powering a hospital in the Maldives. Because it reinvests earnings directly into new contracts rather than distributing them quickly, revenue continues to flow steadily. On the stock market, this model, which has been tried and tested for 10 years, is still completely undervalued. Risk-conscious investors still have an opportunity to get in at RE Royalties' current valuation of around CAD 16 million. Extremely exciting!
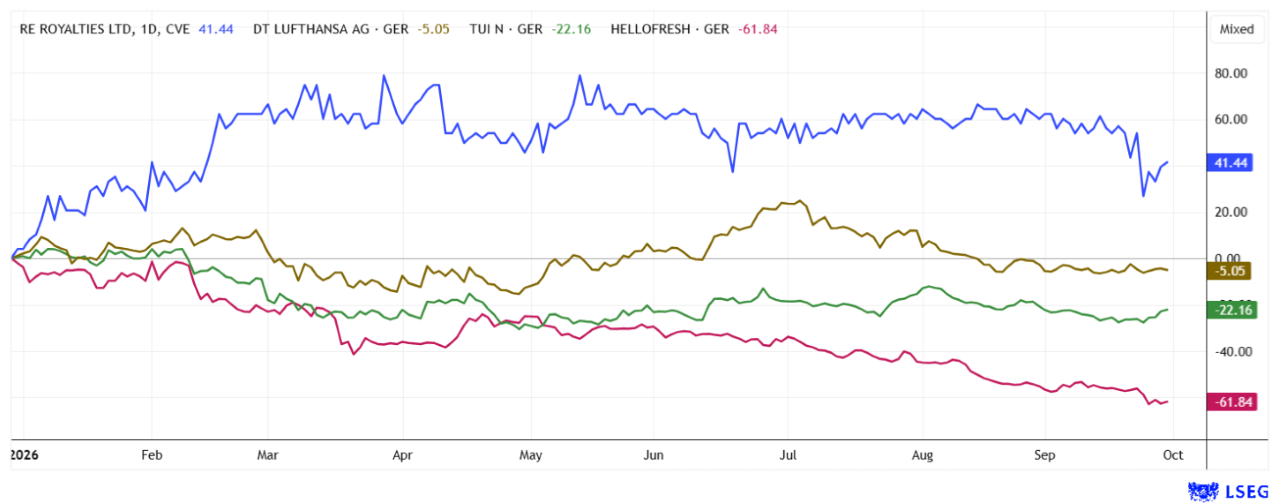
The stock market environment is challenging and requires risk-conscious investors to take a clear medium-term view. After all, daily volatility above 5% is no longer uncommon for individual stocks. Within our selection group, RE Royalties is well positioned thanks to its clearly focused financing approach, while TUI and Lufthansa are hoping for a return to high-margin tourism. As for HelloFresh, it remains to be seen whether its exclusive business model is viable in a highly inflationary environment.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.