November 6th, 2026 | 05:35 CET
Gold potential, pharma comeback and AI boom: Lahontan Gold, Bayer and AMD in Focus
A gold project with enormous return potential, a pharmaceutical group with fresh tailwinds and a chip designer on course for records: Lahontan Gold, Bayer and AMD are currently delivering exciting news. The leverage is particularly strong at the Canadian gold developer, whose Santa Fe project promises enormous growth potential according to the PEA. Bayer, meanwhile, recently raised its earnings targets, while AMD is benefiting from the expansion of data centres. We examine where the opportunities now lie and where investors need to look more closely - three interesting stocks under review.
time to read: 6 minutes | Author: Lars Winter
ISIN: Lahontan Gold Corp | CA50732M1014 , BAYER AG NA | DE000BAY0017 , US0079031078
Table of contents:
Author
Lars Winter
A native of North Hesse, he has over 25 years of experience in financial journalism and active portfolio management and is regarded as a proven expert on German small-cap stocks and special situations.
After studying law at the University of Göttingen with a focus on banking and capital markets law, he began his career in Frankfurt's financial scene at the turn of the millennium. As a stock market and business journalist, the passionate amateur golfer wrote for leading investment newsletters, financial newspapers, and business magazines, including PLATOW Börse, Capital Depesche, BÖRSE ONLINE, Capital, and the Financial Times Deutschland.
Tag cloud
Shares cloud
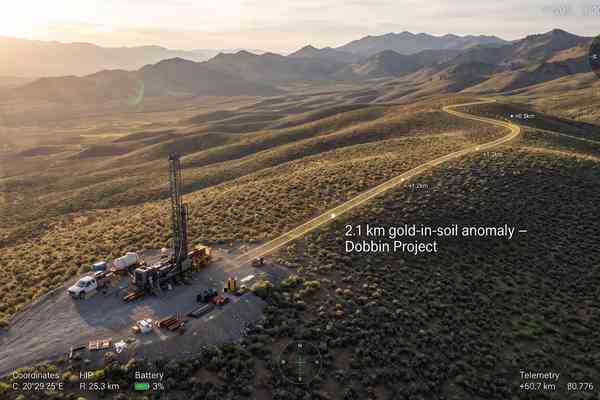
Lahontan Gold: Significant potential beneath Nevada's desert floor
At Lahontan Gold, the planned revival of the Santa Fe mine is taking concrete shape. In mid-October, the company presented an updated preliminary economic assessment (PEA). It puts the after-tax net present value (NPV) at a discount rate of 5% at around USD 820 million. Compared with the USD 56.5 million in the 2024 PEA, this represents more than a fourteenfold increase. The internal rate of return (IRR) exceeds 40%. This gives the story surrounding the gold and silver project in Nevada a new economic dimension.
The calculation uses prices of USD 3,600 per ounce of gold and USD 49 per ounce of silver as its basis. Over 11 active production years, Santa Fe could, under the model assumptions, generate an after-tax cash flow of around USD 1.3 billion. Such amounts explain why the project is of interest to speculative commodity investors. However, the decisive factor remains which assumptions the company can subsequently substantiate in actual operations.
An open-pit mine with heap leaching is planned. The process is proven in Nevada and fits the site's history. Between 1988 and 1995, the site already produced around 359,000 ounces of gold and 702,000 ounces of silver. Lahontan is therefore advancing a former producing mine site. This provides a different starting point from a completely undeveloped deposit, but it does not eliminate the need for new permits or the necessary financing.
On average, the study assumes an annual production of around 91,900 ounces of gold equivalent. From the fourth year of operation, average annual output is expected to increase to around 112,500 ounces. In the fourth year of the mine plan, production is projected to exceed 120,000 ounces. Against the assumed metal prices, all-in sustaining costs (AISC) are estimated at USD 2,250 per ounce. In the model, this leaves considerable scope for earnings.
The sensitivity analysis shows how strongly the calculation responds to precious metal prices. Under the higher-price scenario of USD 4,166 for gold and USD 59 for silver used in the study, the after-tax NPV rises to around USD 1.13 billion, and the IRR to 50.4%. Even at USD 3,000 for gold and USD 30 for silver, the calculated project value remains around USD 476 million. These scenarios are from the study and do not reflect prevailing precious-metal market prices.
Initially, around USD 172 million will be needed to build the mine. Over its life, around USD 158 million in sustaining capital expenditure will be added. A financing mix of equity, loans and possibly streaming or royalty agreements therefore remains a central issue.
The existing resource base is impressive: Santa Fe has around 1.195 million ounces of gold equivalent in the indicated category and a further 1.190 million ounces in the inferred category. There is also the prospect of additional discoveries in the surrounding area and at greater depth. The residual material on historical leach pads and stockpiles could also become economically attractive. Drilling and technical studies will need to show whether, and to what extent, this creates additional value.
There will certainly be further news. According to the company update of October 27, a total of 13,334 m of drilling has already been completed at Santa Fe and West Santa Fe this year. Numerous laboratory results are still outstanding. High exploration activity in Nevada is delaying the analyses. Once the results are available, the project could gain fresh momentum.
West Santa Fe, only around 13 km away, offers additional upside potential. There, 9 of the 19 planned drill holes had been completed by the end of October. The programme aims to define known mineralisation more precisely and test possible extensions. The first resource estimate is now targeted for early 2027.
According to the company, the environmental baseline studies have been completed. The operations plan is intended to form the basis for the further permitting process with the US land agency BLM. Lahontan is targeting 2027 for the permits required to begin construction. Alongside drilling results, concrete development decisions are therefore increasingly coming to the fore. If management succeeds in bringing permits and financing together, the market could revalue the project. For investors willing to take risks, Lahontan remains a promising, albeit highly speculative, gold bet.
Bayer: The pharmaceuticals business offers renewed hope
At Bayer, the third quarter offers fresh arguments for a share price comeback. Revenue rose 4.1% to EUR 10.05 billion, while EBITDA before special items increased 6.9% to EUR 1.62 billion. The pharmaceuticals business, particularly with Nubeqa and Kerendia, is inspiring confidence. Chinese approval of the stroke drug provides an additional tailwind for Asundexian. For the full year, Bayer now expects currency-adjusted EBITDA before special items of EUR 9.8 to 10.3 billion, rather than EUR 9.6 to 10.1 billion.
However, the bottom line still showed a quarterly loss of EUR 672 million. Adjusted earnings per share fell from EUR 0.49 to EUR 0.31. Net financial debt of around EUR 31.1 billion also remains substantial. At least Bayer improved its free cash flow forecast by EUR 1 billion to between minus EUR 1.5 billion and minus EUR 0.5 billion.
Operationally, the direction is therefore increasingly positive. For a sustainably higher valuation, however, the progress must also be visible after financing costs, exceptional charges and legal payments. The latest figures strengthen hopes of a recovery; however, comprehensive financial relief has yet to materialise.
Most analysts nevertheless continue to recommend buying Bayer shares. In total, there are currently 18 Buy recommendations against 3 Hold ratings and 1 Sell recommendation. On average, the experts see fair value at slightly below EUR 60 – that is now only around 7% above the current price. With estimated P/E ratios of 11.3 for 2026 and 10.8 for 2027, the share is trading at roughly the same level as its peers. Bayer offers bold long-term investors with staying power an interesting turnaround opportunity.
AMD: Data centres drive growth
AMD is making its mark in the chip business. In the third quarter, revenue rose 45% to around USD 13.4 billion. Adjusted earnings per share increased by 74% to USD 2.09. The data centre business is the growth engine: revenue climbed 97% to USD 8.5 billion. Demand for EPYC processors and Instinct accelerators shows how deeply AMD is involved in expanding AI infrastructure.
For the final quarter, management forecasts revenue of around USD 17 billion, with a range of plus or minus 3%. This signals further acceleration. Quarterly profit under GAAP accounting standards reached around USD 2.4 billion. AMD is thus delivering substantial profits alongside strong growth.
Many international analysts believe AMD still has considerable potential. Currently, 47 Buy recommendations compare with just 9 Hold ratings, with no Sell recommendations. On average, the experts see fair value at just under USD 631 – around 30% above the current price. The share's valuation remains demanding, however. Based on consensus earnings estimates for 2026 and 2027, the resulting P/E ratios are over 67 and 32, respectively. This means AMD shares are valued at substantial premiums to global peers.
The key question for the share remains how much future success is already priced in. Those backing the company are betting on further market share gains and continued high investment needs among customers. Delays in data centre expansion or unmet margin expectations could have a correspondingly strong impact. Operationally, AMD is currently impressing with its pace and rising profitability. The stock is interesting for growth-oriented investors, and a phased entry can reduce the risk of unfavourable timing.
Conclusion
Of the three, Lahontan Gold offers the most direct leverage to the development of a single major project and the greatest share price upside. The PEA shows considerable growth potential, but unlocking it still requires permits and substantial capital. Bayer scores points with an improved operational outlook and raised targets, but must translate the recovery into a stronger balance sheet. AMD is delivering the strongest ongoing growth, while remaining dependent on high expectations for its AI business. Lahontan is the focus for speculative commodity investors. Bayer is the turnaround bet and AMD the high-growth addition.
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") may hold shares or other financial instruments of the aforementioned companies in the future or may bet on rising or falling prices and thus a conflict of interest may arise in the future. The Relevant Persons reserve the right to buy or sell shares or other financial instruments of the Company at any time (hereinafter each a "Transaction"). Transactions may, under certain circumstances, influence the respective price of the shares or other financial instruments of the Company.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.