November 10th, 2026 | 05:39 CET
Zefiro Methane accelerates growth
Created and published on behalf of Zefiro Methane Corp.
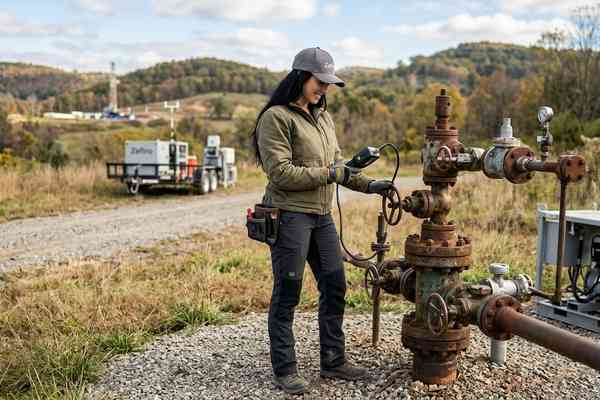
Zefiro specialises in the remediation of orphaned oil and gas wells and the reduction of methane emissions. While economic uncertainty holds back many small-cap stocks, government environmental regulations and funding budgets worth billions open up lucrative niches. Specialist service providers for the remediation of legacy industrial contamination report full order books and are increasingly attracting the attention of institutional investors. Where, then, do potential opportunities and risks lie?
time to read: 3 minutes | Author: Stefan Bode
ISIN: Zefiro Methane Corp | CA98926D1069
Table of contents:
Author
Stefan Bode
A native of the Eichsfeld region in the heart of Germany, he has more than 30 years of experience in the capital markets, with broad expertise spanning financial markets, history, and geopolitics. He founded his own business more than 20 years ago while still a student and today advises clients, foundations, and asset managers across four continents.
Tag cloud
Shares cloud
Orders improve predictability
The government-funded order backlog of Zefiro Methane Corp. most recently stood at around USD 40 million and extends through June 2029. According to GBC, approximately USD 4.9 million of this backlog is expected to be completed in the second quarter of the 2026/27 financial year, taking the total completed by the end of 2026 to that amount. The bulk of the contract volume will therefore be executed in 2027 and 2028, generating revenue accordingly. However, contracts with private oil and gas customers are not included in this and are therefore the driver of additional business potential in the coming quarters. The company's presence in 15 US states also broadens its access to customers.
Earnings turnaround and cash flow
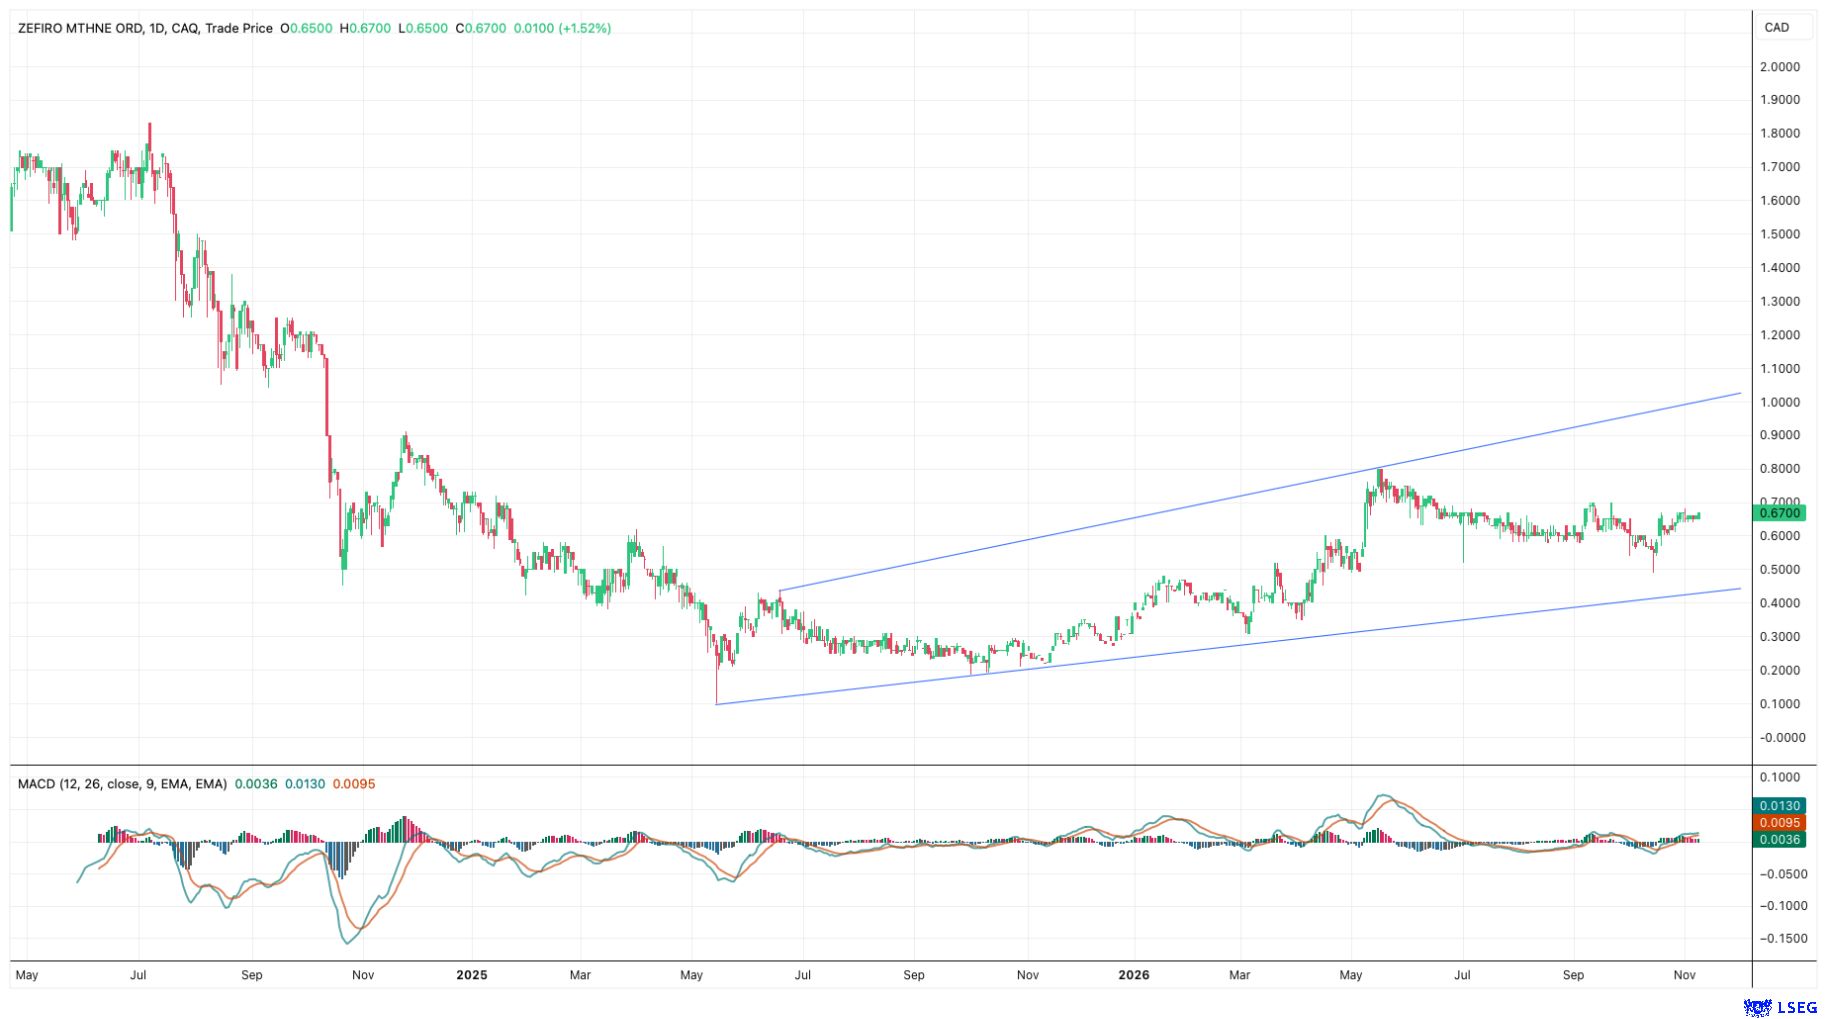
In the 2025/26 financial year ended June 30, 2026, revenue rose by 31.1% to USD 42.5 million. Adjusted EBITDA improved from minus USD 4.0 million to plus USD 3.8 million, representing a margin of around 8.9%. Due to investments and acquisitions, free cash flow was negative at USD 1.85 million, and the net loss was USD 3.2 million. To accelerate the company's growth and pre-finance project orders, the company was able to raise fresh equity above the share price at the time. This resulted in less dilution for existing shareholders and, at the same time, demonstrates the market assessment and outlook of the equity investors, who subscribed for a total of 7.58 million shares at CAD 0.66 each for CAD 5 million. This strengthens working capital against cash of just USD 1.09 million at the financial year-end. However, because of the dilution, GBC slightly lowered its DCF price target from USD 1.50 to USD 1.42, which should be reached by June 2027. Its Buy rating has nevertheless remained unchanged.
Credits and provisions open up new revenue potential
The London-based emissions registry Isometric has developed and published an OWP (Orphaned Well Plugging) protocol for orphaned wells. The associated public consultation process is still ongoing and runs through November 14, 2026. However, if the new crediting protocol is adopted and credits are issued, several process steps must be completed. In addition to the necessary methane measurements and independent verification of the measurement results, it must also be demonstrated that the wells would not have been plugged without the issuance of credits. A permanence assessment of the plugged wells must also be carried out after 12 to 18 months. If the results are positive, the credits withheld until then will be released. While this does not yet translate into rapid revenue in the short term, new plugging projects involving methane-emitting orphaned wells would gradually establish a new, predictable revenue pipeline.
Remediating legacy wells is significantly less dependent on the oil price than developing new deposits. However, the geopolitical energy uncertainties of recent quarters also show that the high oil price has significantly increased the investment budgets of small and large oil companies. These companies are therefore likely to increasingly begin addressing existing legacy liabilities and releasing the provisions set aside for depleted oil and gas wells by awarding contracts to specialist firms such as Zefiro Methane.
Conclusion
Compared with the past six months, Zefiro has a more visible revenue base, and its liquidity position has also strengthened significantly. The forthcoming credit business broadens the prospects for new revenue streams over the next few years. The company must now consistently continue on its chosen growth path and generate new orders at the same pace as before so that the order book fills even faster for the coming quarters. Based on execution to date, the growth plan and economies of scale, research firm GBC assigns Zefiro a Buy rating and a price target of USD 1.42 (approximately CAD 2.00).
Conflict of interest
Pursuant to §85 of the German Securities Trading Act (WpHG), we point out that Apaton Finance GmbH as well as partners, authors or employees of Apaton Finance GmbH (hereinafter referred to as "Relevant Persons") currently hold or hold shares or other financial instruments of the aforementioned companies and speculate on their price developments. In this respect, they intend to sell or acquire shares or other financial instruments of the companies (hereinafter each referred to as a "Transaction"). Transactions may thereby influence the respective price of the shares or other financial instruments of the Company.
In this respect, there is a concrete conflict of interest in the reporting on the companies.
In addition, Apaton Finance GmbH is active in the context of the preparation and publication of the reporting in paid contractual relationships.
For this reason, there is also a concrete conflict of interest.
The above information on existing conflicts of interest applies to all types and forms of publication used by Apaton Finance GmbH for publications on companies.
Risk notice
Apaton Finance GmbH offers editors, agencies and companies the opportunity to publish commentaries, interviews, summaries, news and the like on news.financial. These contents are exclusively for the information of the readers and do not represent any call to action or recommendations, neither explicitly nor implicitly they are to be understood as an assurance of possible price developments. The contents do not replace individual expert investment advice and do not constitute an offer to sell the discussed share(s) or other financial instruments, nor an invitation to buy or sell such.
The content is expressly not a financial analysis, but a journalistic or advertising text. Readers or users who make investment decisions or carry out transactions on the basis of the information provided here do so entirely at their own risk. No contractual relationship is established between Apaton Finance GmbH and its readers or the users of its offers, as our information only refers to the company and not to the investment decision of the reader or user.
The acquisition of financial instruments involves high risks, which can lead to the total loss of the invested capital. The information published by Apaton Finance GmbH and its authors is based on careful research. Nevertheless, no liability is assumed for financial losses or a content-related guarantee for the topicality, correctness, appropriateness and completeness of the content provided here. Please also note our Terms of use.